
Published: | Last reviewed:
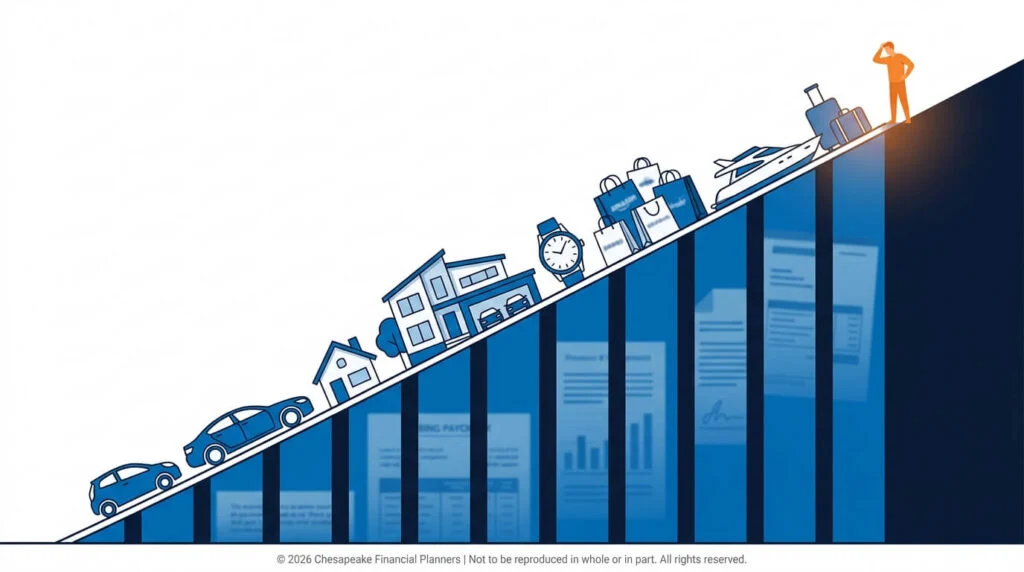
Lifestyle creep is the slow rise in spending that follows every raise, bonus, or promotion until your higher income funds a more expensive life instead of a stronger balance sheet. It is why a household earning $300,000 can feel just as stretched as one earning $90,000. The income went up, the lifestyle went up to match, and the savings rate never moved. For high earners, this is the single quietest reason wealth never accumulates the way the paycheck suggests it should.
Key Takeaways
- Lifestyle creep is rising spending that absorbs every income increase, leaving your savings rate flat despite a growing paycheck.
- High earners are most vulnerable because each raise feels like permission to upgrade housing, cars, and recurring subscriptions.
- The personal saving rate sat at just 4.5% in early 2026, showing how little income converts to wealth.
- Hedonic adaptation means lifestyle upgrades stop feeling special within months, so spending rises but lasting satisfaction does not.
- Banking a fixed share of every raise before it hits checking is the simplest defense against spending creep.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate spending and savings behavior since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the most dangerous money problem he sees is not a bad investment, it is a great income quietly spent on a life that no longer feels like a luxury.
About Jeff Judge, CFP®: meet Jeff and the Chesapeake Financial Planners team.
What Is Lifestyle Creep and How Does It Start?
Lifestyle creep, sometimes called lifestyle inflation, is the gradual increase in discretionary spending that tracks rising income. It rarely arrives as one big decision. It shows up as a string of small, reasonable upgrades: a nicer apartment after the promotion, a car with the better trim, a few more subscriptions, dinners out twice a week instead of twice a month. Each step feels earned. Together they reset your baseline cost of living to a higher number that now feels normal and non-negotiable.
The mechanism is well documented. The Consumer Financial Protection Bureau describes how spending habits anchor to current income, which means a raise that should have widened the gap between earning and spending often closes it instead. The trap is that nothing here looks like overspending. No single purchase is reckless. The problem is the pattern, and patterns are nearly invisible while they happen.
Jeff has watched this play out with new clients who earn well into the top tax brackets yet have shockingly little liquid net worth. The income tells one story. The bank statement tells another.
Lifestyle creep tends to develop in three stages, and recognizing which one you are in shows how much room you have to course-correct. Stage one is the reasonable upgrade: your first real raise arrives, and you make a few genuine quality-of-life improvements, like a private bedroom instead of roommates or a reliable car. Nothing is wrong here. Stage two is normalization: within two or three years those upgrades become your baseline, and you start upgrading the upgrades. Stage three is the trap: your expenses match your income, so every new raise is absorbed by recurring costs before you see it. Your quality of life has improved, but your wealth-building pace has not. This is a planning framework, not a research finding.
Consider a hypothetical, for illustration only: suppose lifestyle creep absorbs an extra $7,000 a month that could have been invested. Over five years that is $420,000 spent rather than invested. You traded potential future savings for incremental comfort today without making a conscious decision to do it.
Why Does Lifestyle Creep Hit High Earners the Hardest?
High earners are uniquely exposed because their raises are larger, their social environment is more expensive, and their spending capacity rarely runs out. A $20,000 raise on a $250,000 salary can disappear into a single housing upgrade without ever triggering the alarm a tighter budget would set off. There is always room for one more upgrade, so the natural stopping point that constrains lower earners never appears.
The data backs this up. The U.S. personal saving rate was roughly 4.5% in early 2026 according to the Bureau of Economic Analysis, historically low and a sign that across income levels, more money in tends to mean more money out. High earners are not exempt. They often have the most lifestyle to inflate.
There is also a psychological driver: hedonic adaptation. Humans normalize new comforts fast. The first month in the bigger house feels incredible. By month four it feels ordinary, and the brain starts scanning for the next upgrade. This is why spending creep is self-perpetuating, and why a higher income so rarely buys lasting satisfaction. The lifestyle floor keeps rising while the contentment ceiling stays put. Many of the same forces show up in the behavioral biases that hurt your portfolio, and the fix is similar: build a system that does not rely on willpower in the moment. Jeff Judge notes: "Hedonic adaptation is the reason I tell clients not to rely on feeling wealthy to control spending — the brain resets to the new normal in a few months, so without a savings rate locked in before the raise hits the account, the raise tends to vanish."
How Do You Recognize Lifestyle Creep in Your Own Finances?
The clearest signal is a savings rate that stays flat or falls while your income climbs. If you made $150,000 three years ago and $230,000 today but you still save roughly the same dollar amount, lifestyle creep has absorbed every dollar of that increase. Another tell: recurring monthly commitments that have quietly multiplied, from car payments to streaming services to club memberships you forgot you had.
A useful test is to total your fixed monthly obligations and compare them to your take-home pay. When fixed costs consume most of your income, you have less flexibility than your salary implies, and you are one disruption away from financial stress. According to the Federal Reserve's 2024 Survey of Household Economics, a meaningful share of higher-income households would still struggle to cover an unexpected expense, which is exactly what creep produces: a big paycheck and a thin cushion. Jeff frames this in his practice through the R.U.D.D.E.R. Method™, the firm's six-step planning process, where the Review and Recognize step is built specifically to surface spending patterns clients have stopped noticing.
Fidelity's retirement savings guideline assumes saving 15% of your income each year, including any employer match, starting at age 25. Treat it as a benchmark rather than a rule. When lifestyle creep absorbs your raises, your savings rate as a percentage of income can fall even as the dollar amount rises. Our guide to whether you are on track for retirement can help you see where you stand.
What Is the Best Way to Stop Lifestyle Creep?
The most effective defense is automating savings increases before the money ever reaches your checking account. When a raise hits, route a fixed share of it straight into retirement accounts, taxable investments, or your emergency fund before you adjust your spending. What you do not see, you do not spend. This turns each raise into a wealth event instead of a lifestyle event. Whatever you leave unassigned becomes a phantom raise: it shows up on the pay stub, gets taxed, gets deposited, and disappears into spending before you ever decide what it was for. A small automatic bump rarely solves this, because a one percent 401(k) increase captures only a sliver of a large raise and leaves most of the new money with no rule attached. Treat auto-escalation as a floor, then give the rest of the raise a deliberate job.
Bonuses deserve the same rule, since they arrive as a lump sum and people tend to treat them more loosely than salary, a quirk of mental accounting. Decide the split before the deposit lands and route a fixed percentage into a brokerage account or an IRA before it touches checking; the IRS 2026 IRA limit is $7,500. Our guide on how high earners build wealth without lifestyle creep shows what this looks like in practice.
A simple rule Jeff uses with clients: bank at least half of every raise. Live on the rest. You still get to enjoy a meaningful lifestyle improvement, but you also widen the gap between earning and spending every single time your income grows. Over a decade of raises, that habit is the difference between a comfortable retirement and a stressful one. The goal is not to deny yourself, it is to make sure your spending reflects your actual values rather than the default of upgrading because you can. That mindset connects directly to why your money values drive better outcomes than your investment picks.
If your pay includes equity compensation, lifestyle creep can become a bigger risk. RSUs that vest, stock options you exercise, and ESPP shares can feel like bonus money, which makes them easy to spend. They are real compensation. A practical defense is to decide, before the cash lands, what percentage of every raise and every equity event goes straight to investing. Start with your tax-advantaged accounts: the IRS set the 2026 employee 401(k) contribution limit at $24,500, with an additional catch-up contribution for those age 50 and older. For high earners managing vesting schedules, coordinating sales with tax planning matters as much as the saving itself. See our guides on RSU tax planning and tax bracket management for high earners.
For the full guide, see HENRY Finance: A Money Roadmap for High Earners Not Rich Yet.
Related services: financial planning for tech and SaaS professionals · stock option, buyout and severance planning
More in this guide:
Frequently Asked Questions
What is the difference between lifestyle creep and lifestyle inflation?
There is no meaningful difference; lifestyle creep and lifestyle inflation are two names for the same behavior. Both describe spending that rises to match increasing income, which keeps your savings rate flat even as your paycheck grows. Some people use "creep" to emphasize how gradual and unnoticed the process tends to be.
Is lifestyle creep always bad?
Lifestyle creep is not automatically bad if your savings rate still rises alongside your spending. The danger is spending that grows faster than your savings, which leaves you with a larger income but no greater financial security. A modest, intentional lifestyle upgrade you genuinely value is fine. The problem is unconscious upgrading that quietly consumes every raise you earn.
How much of a raise should I save to avoid spending creep?
A practical target is saving at least half of every raise before adjusting your spending. If you receive a $10,000 raise, direct $5,000 toward retirement or investments and let yourself enjoy the rest. This approach lets you improve your lifestyle while still widening the gap between what you earn and what you spend over time.
What is hedonic adaptation and how does it fuel lifestyle creep?
Hedonic adaptation is the tendency to quickly return to a baseline level of happiness after a positive change, including a lifestyle upgrade. A new car or larger home feels exciting at first, then becomes ordinary within months. This drives lifestyle creep because the brain keeps seeking the next upgrade to recapture that fading satisfaction, raising spending without lasting payoff.
Why do high earners struggle with lifestyle creep more than others?
High earners struggle more because their raises are larger, their social circles are more expensive, and they rarely hit a spending limit that forces them to stop. A big income absorbs upgrades without triggering the warning signs a tight budget creates. As a result, many high earners build a costly lifestyle while accumulating surprisingly little wealth.
Can a financial planner actually help with lifestyle creep?
Yes, a financial planner helps by making spending patterns visible and building systems that protect your savings before you can spend the money. A planner can automate raise-based savings, set targets tied to your values, and review fixed commitments that have crept up over time. The value is structure and accountability, not just budgeting advice you already know.
How much of my income should I be saving?
Fidelity's retirement savings guideline assumes saving 15% of your income each year, including any employer match, starting at age 25. People with equity compensation may need to save more, especially in years with large vesting events. The key is protecting your savings rate as a percentage of income even as your earnings climb.
How does equity compensation make lifestyle creep worse?
Equity compensation such as RSUs and stock options can feel like bonus money, which makes it easy to spend rather than invest. When vesting events are treated as found money, large sums can get absorbed into your lifestyle, and each absorbed dollar loses the chance to compound over time.
Will bumping my 401(k) by one percent fix lifestyle creep?
Bumping your 401(k) by one percent helps a little but rarely matches the size of a real raise. On a large raise, a one percent increase can capture only a few percent of the new money, leaving most of it unassigned. Treat auto-escalation as a useful floor, then attach a deliberate rule to the rest of every raise.
What should I do the week a bonus lands?
Decide the bonus's split before it arrives, then set up the transfer the same week so it runs automatically the day the deposit posts. Route a fixed percentage into savings, investments, or an IRA before the money reaches checking, and treat the remainder as fully yours.
Sources
- 4.5% in early 2026 (bea.gov)
- Consumer Financial Protection Bureau (consumerfinance.gov)
- Federal Reserve's 2024 Survey of Household Economics (federalreserve.gov)
- IRA limit is $7,500 (irs.gov)
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.


