

Sale of Business
Selling Was Just Step One.
You’ve spent years building your business. Now it’s time to build a life that works just as well.
See if You’re a Fit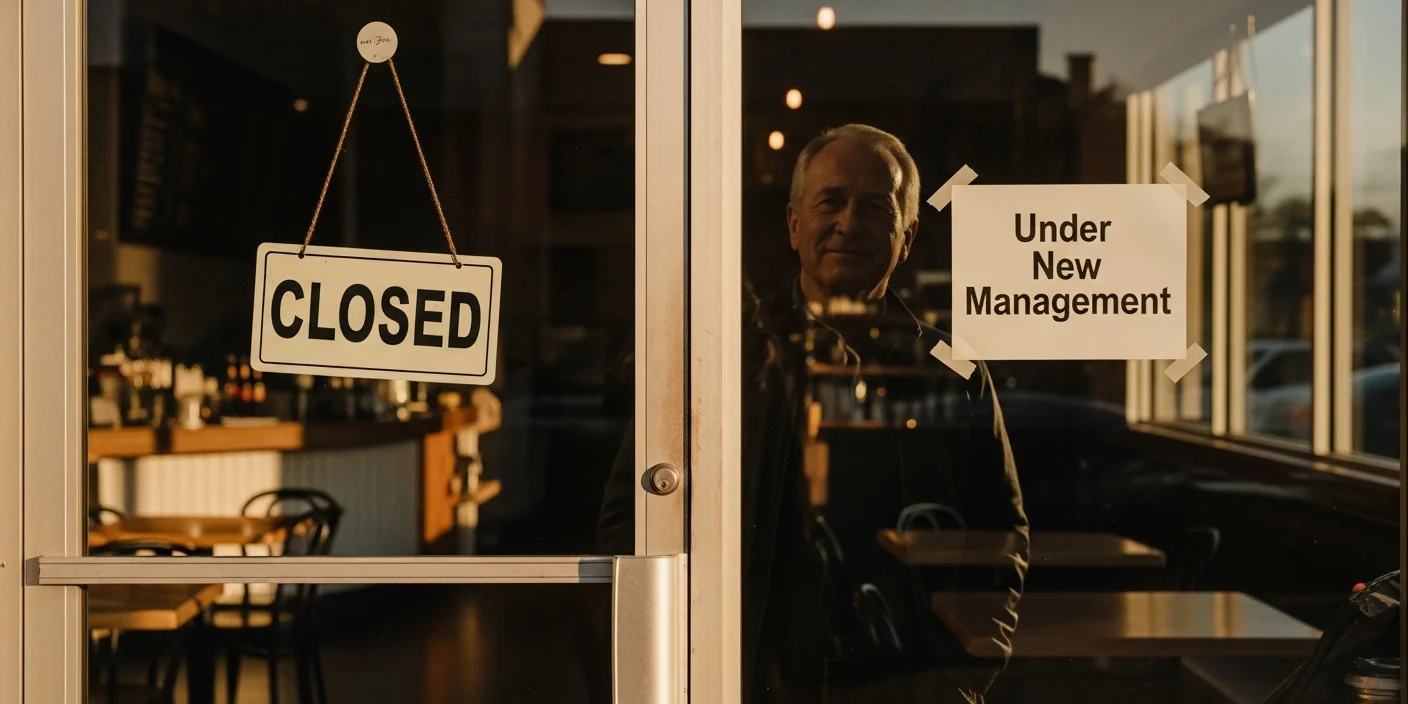
Featured In











Selling a business isn’t just a financial transaction, it’s a full-blown identity shift. You’ve gone from decision-maker to wealth-holder, from building something to managing everything. And even though the liquidity is real, so is the complexity.
Maybe you’re still finalizing the deal, trying to make smart moves without triggering massive tax consequences. Maybe it’s already closed, and you’re wondering how to turn proceeds into lasting security, or what to do next with your time, your energy, or your legacy.
This isn’t the moment for DIY or one-size-fits-all. It’s time for a thinking partner who speaks fluent business owner and entrepreneur, understanding the intricacies of life after a liquidity event.

Thomas Cowley
6 days ago
Mark and Jeff have handled my finances for over a decade. They have been great stewards for my investments which have grown substantially. They listen to my goals and give me recommendations and options to carry them out. I highly recommend them.
Jane Towery
3 months ago
I have been extremely pleased with Mark’s services over the last 15 years and would very highly recommend. Mark has taken the time to get to know my needs, interests, long and short term goals. We evaluate my portfolio yearly for any adjustments, reevaluation, or study trends. Mark objectively presents the pros and cons of options, answers questions, and leaves the final decision to me. I have never felt pressured and always appreciate how understood and listened to I have felt. More recently I have had some opportunity to work with Jeff as well. Mark and Jeff present a unified team who want to make your investments work for your needs.

Joyce Ducksworth
5 months ago
I have had the pleasure of entrusting my finances with Jeff and Mark for many years. Their expertise and advice are invaluable. My portfolio has grown significantly and has allowed me to retire comfortably with tremendous financial security. Mark is always available to answer my questions and provide solutions. I highly recommend Chesapeake Financial Planners.
stephen kinsley
5 months ago
Mark and Jeff have been my retirement advisors since 2011 and I could not be happier with them. They are knowledgeable and easy to talk with. They respond quickly to any questions and clearly explain all my options. I have been retired for 5 years and am fully confident that my financial future will continue to improve as it has so far with them. I would recommend them to anyone, and I only wish that I had met them sooner.
Bob Burris
6 months ago
I have been working with Mark and Jeff for 10+ years. I recently asked for a review of my financial plan and was provided outstanding feedback that provided me a much better solution.

Kim Wright
7 months ago
I am delighted with LPL. They've stayed with me for years and Jeff Judge has been exceptionally helpful. I've gotten good advice. He's managed my assets professionally and has always been available answer my questions.
He helped me consolidate several accounts into one manageable asset. He took the guesswork out of what could have been a complicated process.
I trust him to be there and guide me through issues in which I have no expertise. But he does this all the time and has proven to be trustworthy.
I do recommend Mr. Judge. You will not be disappointed.
Sharon Lewis
7 months ago
My husband and I met Mark and Jeff in 2014 when my husband left his job after 23 years. We met with Mark and Jeff to decide where to invest his retirement money. Before that decision was made, they took their time to understand our entire financial picture and based on that they gave us several options on where we could invest. They were very easy to talk with and made the conversation easy to understand. They are easy to get in touch with if you have questions and provide answers quickly. When it came time for me to retire, I also rolled my retirement investments into accounts managed by Mark and Jeff. We have also setup our estate planning as well as long term health planning based on advice we have had in review meetings in the years following our initial meeting. We have even referred our daughter and son in law to them. Highly satisfied with the investment service and customer service.

Andrew Benner
7 months ago
I check in with Mark a couple times a year and he always helps me keep my money that he manages growing. He also helps us with general advise regarding the type of places our 401k money should be (growth vs value, etc)

Mark Gray
9 months ago
Jeff has been helping me since 2014 with life insurance and retirement investment products. After a bad experience with a big insurance company, I found Mark and I’ve been working with him ever since. I’m successfully retired now and will begin drawing on my investments this year. I highly recommend Chesapeake Financial Planners for your retirement planning. – Mark G.
David Carrington
10 months ago
Jeff has been my financial advisor/ planner for several years. He has always guided me in the right direction and I have seen my retirement account continuously moving in the right direction. During the current uncertainty of the financial world right now Jeff has given me peace of mind that I continue to be in a safe and secure position with my finances. Jeff is very professional and quick to respond to my emails. As I approach my retirement years it is comforting to know my finances will be there when I need them.
Matt Hurson
11 months ago
I have been working with Jeff Judge and Chesapeake Financial Planners for about 3 years. Jeff has provided timely and well considered advice and acted promptly when I've needed access and changes to my portfolio. Highly recommend their services.

John Komoroski
12 months ago
We have worked with Jeff at Chesapeake Financial Planners for over 10 years. Throughout that time he has provided valuable investment and retirement information. Our investments have navigated this turbulent market far better than expected. Thank you Jeff.
Charles Gaither
12 months ago
I've been working with Chesapeake Financial Planners for a little over six years, and it's been an outstanding experience. They're knowledgeable, responsive, and consistently provide clear, personalized advice that aligns with my financial goals. Their long-term commitment and reliability have given me real peace of mind.
At Chesapeake, we don’t lead with products or formulas. We start with you, your goals, your risks, your vision for this next chapter. Then we help you build a strategy that protects what you’ve built, aligns with what matters, and flexes as your life evolves.
Whether you want to slow down or start something new, support your family or support causes you care about, our job is simple: help you use this wealth wisely, so you can move forward with confidence, not question marks.
Frequently Asked Questions
How much is my business worth if I want to sell?
Your business value is driven by cash flow, not just revenue. Most buyers use a multiple of EBITDAEarnings Before Interest, Taxes, Depreciation, and Amortization — a measure of a company's core operating profitability before financing and accounting decisions are factored in. In the context of a business sale, your EBITDA multiplied by an industry multiple is typically the starting point for valuing what your company is worth to a buyer. (earnings before interest, taxes, depreciation, and amortization), adjusted for your industry, growth potential, and how dependent the business is on you personally. A business that runs without you commands a higher multiple than one that can't.
Seven factors shape the final number:
1. Normalized earnings and profit margins
2. Industry benchmarks and transaction multiples
3. Owner dependency (the lower, the better)
4. Clean, organized financial records
5. Customer diversificationSpreading investments across multiple asset classes, sectors, and geographies so a loss in one area doesn't devastate your entire portfolio. It's the financial equivalent of not putting all your eggs in one basket — and it's one of the few strategies that can reduce risk without necessarily reducing expected returns. and recurring revenue
6. Tangible assets, IP, and market positioning
7. Market timingAttempting to buy and sell investments based on predictions about future market direction. Decades of research show that consistently timing the market is extraordinarily difficult — even for professionals — and attempts to do so usually result in worse returns than simply staying invested. and current buyer demand
A certified business appraiser can give you a formal number for legal or tax purposes. Before you get there, it's worth understanding which of these drivers you can still improve.
What will I pay in taxes when selling my business?
What you pay in taxes when selling your business depends on three things: how your business is structured, how the deal is structured, and how well you plan ahead.
C corporations may face double taxation unless they qualify for the Section 1202 QSBS exclusionThe Qualified Small Business Stock exclusion allows investors in certain early-stage companies to exclude up to 100% of capital gains — up to $10 million — when selling qualifying shares held for more than five years. It's one of the most powerful tax breaks available to investors in startups and early-stage private companies.. S corporations, LLCs, and sole proprietors pay tax only at the individual level. Capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. from the sale are typically taxed at lower long-term rates; ordinary income rates apply to recaptured depreciation, inventory, and service contracts.
Buyers typically prefer asset sales (better depreciation benefits for them, but a higher tax bill for you). Sellers usually prefer stock sales for cleaner capital gains treatment. How the purchase price is allocated among assets like goodwill, equipment, and non-competes also affects your final liability.
Timing matters too. If the sale spikes your income in one year, installment sale structures can spread the tax burden. QSBS exclusions, Opportunity Zone reinvestments, charitable trusts, and retirement plan contributions can all reduce what you owe.
Can I retire after selling my business?
You can retire after selling your business, but the sale price isn't your answer. What matters is what you net after taxes and fees, how much your lifestyle actually costs, what other income sources you have, and how long the money needs to last.
If you're exiting in your 50s or early 60s, proceeds may need to support 30 or more years. That math requires a real retirement income plan, not just a lump sum in the bank. Social Security, investment accounts, and your spouse's income all factor in.
Many owners also find they're not emotionally ready to stop entirely. Knowing your number matters. Knowing what comes next matters just as much.
Do I need a professional business valuation?
Yes, in most cases. If you're planning to sell, going through a divorce, bringing on a partner, seeking financing, or doing estate planning, a ballpark estimate won't protect you. A professional valuation from a Certified Valuation Analyst (CVA) gives you a credible, defensible number.
Even when you're not required to get one, a valuation helps you understand what actually drives your company's value, set realistic timelines for a sale, and spot weaknesses worth fixing before you go to market. The right level of detail depends on your stage and goals.
How do I invest the proceeds from selling my business?
Investing business sale proceeds well starts with one rule: don't rush. A large, sudden liquidity event creates the temptation to act fast. The owners who protect wealth best tend to pause first.
Park the funds in high-yield cash or short-term instruments while you build a complete picture of what you need the money to do. Then work through these priorities:
1. Replace the income your business provided with a reliable withdrawal or income strategy
2. Diversify across asset classes, since your wealth was concentrated in one company for years
3. Coordinate with your CPA on capital gains, Roth conversions, and charitable strategies
4. Update your estate plan and beneficiary designations to reflect your new net worth
5. Build a portfolio allocation that balances growth, stability, and liquidity for your timeline
The investment strategy should serve the life you want next, not just maximize a return number.
How do I prepare my business for a strong sale?
A strong sale starts years before you list. Buyers pay premiums for businesses that are clean, documented, and capable of running without the owner. The preparation work you do now directly affects the multiple you command at the table.
Start with your financials: three years of organized statements, clear separation of personal and business expenses, and consistent bookkeeping. Then look at whether the business can operate without you. Well-documented processes, a capable team, and delegated responsibilities all increase buyer confidence and your valuation.
Beyond the books, reduce reliance on any single customer or revenue source, get corporate documents and contracts organized before due diligence begins, and think through what deal structure serves your tax situation. An asset sale and a stock sale carry very different tax outcomes.
Most owners who achieve strong exits begin preparing two to three years out, not two months out.
How long will it take to sell my business?
Most small to mid-sized business sales take 6 to 12 months from listing to closing, and often longer if the business isn't prepared. The total timeline from start to signed deal typically runs 12 to 24 months when you include preparation.
The four main phases:
1. Preparation (3 to 12 months): Getting financials organized, valuation drivers identified, and documentation in order
2. Time on market (3 to 9 months): Finding a buyer who fits on price, financing, and culture
3. Negotiation and due diligence (1 to 3 months): Legal review, financial scrutiny, and offer finalization
4. Closing and transition (1 to 3 months): Final filings, approvals, and handoff
Deal complexity, industry seasonality, and whether you're selling to an outside buyer, a family member, or employees all affect timing. Owners who start preparing 2 to 3 years before their target exit date consistently have better outcomes than those who try to rush it.
What are my options besides selling outright?
Selling to an outside buyer is one option, not the only one. Business owners have a range of exit paths depending on what matters most: liquidity, legacy, control, or continuity.
Seven alternatives worth evaluating:
1. Family or employee buyout: Gradual transition with seller financing or a structured buyout plan
2. Management buyout: Existing leadership acquires the business, often with outside financing
3. Employee Stock Ownership Plan (ESOPAn Employee Stock Ownership Plan — a retirement plan in which employees own shares of the company they work for, often used as a business succession strategy when an owner wants to sell to their team. For business owners, it can offer significant tax advantages; for employees, it creates a tangible stake in the company's success.): Employees acquire ownership over time, often with meaningful tax advantages for the seller
4. Partial sale or recapitalization: Sell a stake to a private equity firm, take liquidity, and retain a role in the company's growth
5. Phased retirement: Step back to an advisory or board role while keeping equity
6. Lifestyle wind-down: Shift to a lower-overhead operation that generates income until you're ready to close
7. Charitable exit: Donate the business or integrate it into a charitable trust for tax and legacy benefits
Each path carries different legal, tax, and planning implications. The right choice depends on your goals.
Should I tell my employees I’m selling the business?
Yes, but timing is everything. Telling employees too early creates anxiety, rumors, and potential turnover that can actually undermine the deal. Telling them too late damages trust and morale at a moment when the buyer needs stability.
The standard practice: wait until a signed Letter of Intent or near-final terms are in place. That way you can answer their core questions: Will my job be safe? Who's the new owner? What's changing? A clear, confident message at the right moment protects both the transaction and your relationship with the people who helped build the business.
Key employees may need to know earlier if their retention is part of the deal structure. If so, coordinate that conversation with your buyer and have a retention plan ready.
What legal documents are required to complete a sale?
Selling a business requires a specific set of legal documents to transfer ownership, protect both parties, and satisfy regulatory requirements. The exact list varies by deal type, but most sales involve the following:
1. Letter of Intent (LOI): A non-binding document outlining price, structure, and key terms before the formal agreement
2. Purchase Agreement: The core binding contract covering what's being transferred, representations and warranties, liabilities, indemnities, and closing conditions
3. Bill of Sale or Assignment Agreements: Transfers specific assets or intellectual property
4. Non-Compete or Non-Solicitation Agreement: Restricts the seller from competing or recruiting after the sale
5. Employment or Consulting Agreement: Documents any post-sale role you or key employees will play
6. Promissory Note: Required if the buyer is making installment payments to you
7. Corporate Resolutions: Board or shareholder authorization to complete the sale
8. Closing Statement: Final accounting of all funds transferred at closing
Depending on your situation, you may also need lease assignments, franchise agreements, or tax clearance certificates.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
Ready to stop second-guessing and start feeling in control?
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.