Maryland Estate and Inheritance Tax Calculator
What Would Maryland Estate and Inheritance Tax Cost?
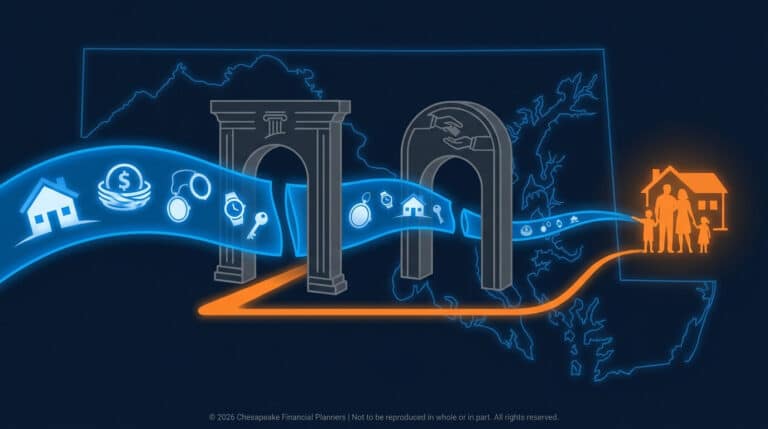
Maryland taxes estates two ways. Its inheritance tax is 10% of what nieces, nephews, friends and other non-exempt heirs receive (Maryland Tax-General 7-204). Its estate tax applies above a $5,000,000 exclusion, capped at 16% (Maryland Tax-General 7-309). Inheritance tax paid is credited against the estate tax. Federal estate tax starts above $15,000,000 for 2026 (IRS 2026 inflation adjustments).
What Does the Maryland Estate and Inheritance Tax Calculator Estimate?
Maryland has two separate death taxes, and they work differently. Maryland inheritance tax is a tax on certain people who receive property, at 10% of what they receive (Maryland Tax-General 7-204), no matter how large the estate is. Maryland estate tax is a tax on the estate as a whole, but only on the amount above a $5,000,000 exclusion for 2026 (Maryland Tax-General 7-309). The two interact: inheritance tax paid is credited against the Maryland estate tax. The federal estate tax is separate again, with a $15,000,000 exclusion for deaths in 2026 (IRS 2026 inflation adjustments).
The results show the estimated inheritance tax, the Maryland estate tax after the inheritance tax credit, the federal estate tax, whether returns may be required, and when the Maryland estate tax is due. It opens in a Quick estimate mode with group totals by kind of heir; a Detailed mode lets you name each beneficiary, apply a will’s tax clause, add an exclusion inherited from a late spouse, illustrate growth, and include property outside Maryland, gifts to grandchildren and business interests. Assumptions and the tax year are shown with every result. It is an educational estimate, not legal or tax advice; wills, trusts and titling are covered in estate planning for Maryland residents.
How Is Maryland Estate and Inheritance Tax Calculated?
What it estimates: Maryland inheritance tax by type of heir, Maryland estate taxA federal (and sometimes state) tax on the transfer of assets to heirs at death, assessed on the total estate value above the applicable exemption. The federal exemption is $15 million per person in 2026: the 2025 law known as the One Big Beautiful Bill Act set it at that level, indexed for inflation after 2026, with no scheduled sunset. before and after the inheritance tax credit, federal estate tax after deducting the Maryland taxes, the combined total, and whether a Maryland or federal estate tax return is likely required.
What you enter: Quick estimate (the mode the calculator opens in): Total Estate Value; Debts and Expenses (optional); Lifetime Taxable Gifts (optional); Marital Status at Death; Left to Spouse (shown when Marital Status at Death is Married); Left to Nieces and Nephews; Left to Other People (Friends, Cousins, Partners); Left to Charity; Maryland Exclusion Inherited From Late Spouse (shown when Marital Status at Death is Married or Widowed); Where the Person Who Died Lived; and Real Estate and Tangible Property Located in Maryland (shown when Where the Person Who Died Lived is Not a Maryland Resident). Detailed adds the year of death, whether everything passes through probate, gift taxA federal tax on transfers of money or property to another person exceeding the annual exclusion — $19,000 per recipient in 2026. Gifts above this threshold count against your lifetime estate and gift tax exemption, and while most people never actually owe gift tax, tracking large gifts matters for estate planning. already paid, heirs entered by group totals or by named beneficiary, a federal exclusion inherited from a late spouse and Maryland QTIP elections, a growth illustration, property outside Maryland, the surviving spouse’s later estate, and gifts to grandchildren and business interests.
1. Inheritance tax first
10% of the clear value passing to nieces, nephews, and other non-exempt people. A person whose total taxable share is $1,000 or less owes none (Maryland Tax-General 7-203). Transfers to a spouse, lineal family, parents, siblings, and qualifying charities are exempt. In Detailed mode, named beneficiaries are taxed person by person, and a will that has the estate pay the tax on a gift is grossed up.
2. Maryland taxable estate
Estate value minus debts and expenses, the amount left to a spouse, and charitable bequests.
3. Maryland estate tax before credit
Capped at 16% (Maryland Tax-General 7-309) of the taxable estate above the exclusion ($5,000,000, plus any Maryland exclusion inherited from a late spouse). The calculator follows the Maryland estate tax return, and in practice the 16% cap is the amount that applies.
4. Inheritance tax credit
Inheritance tax paid is subtracted from the Maryland estate tax, but not below zero. The combined Maryland amount is therefore generally the larger of the two taxes, not their sum.
5. Federal estate tax
The federal taxable estate deducts debts, spousal and charitable bequests, and the Maryland taxes paid. Lifetime taxable gifts are added back, the federal rate schedule is applied, and the credit for the $15,000,000 exclusion (plus any inherited federal exclusion) and gift tax payable on lifetime gifts are subtracted. Above the exclusion, the federal rate is 40% (26 U.S.C. 2001).
6. Filing and portability notes
Whether a Maryland or federal return is likely required, when the Maryland estate tax is due (9 months after death, per Maryland Tax-General 7-306), and, for a married person, how much unused exclusion could pass to a surviving spouse if portability is elected on a timely return.
What you see: Estimated Total Death Taxes first, then the Maryland and federal amounts side by side, followed by detail groups for the inheritance tax, the Maryland estate tax, the federal estate tax, and filing and planning notes.
What Assumptions and Sources Does It Use?
- Year of death: 2026 in the example (Detailed mode lets you choose among the years the calculator has data for). A Maryland resident, with all property taxable in Maryland unless you enter property outside Maryland or choose nonresident.
- Maryland inheritance tax: 10% of clear value for non-exempt heirs; exempt heirs include a spouse, lineal heirs and their spouses, parents, grandparents, step relations, siblings, and a registered domestic partner (Maryland Tax-General 7-203 and 7-204; Register of Wills).
- Maryland estate tax: $5,000,000 exclusion for deaths in 2019 and later, plus any inherited Maryland exclusion; capped at 16% of the excess (Tax-General 7-309; Comptroller of Maryland).
- Inheritance tax credit: inheritance tax paid reduces Maryland estate tax, not below zero (Tax-General 7-304; Comptroller of Maryland).
- Federal estate tax: $15,000,000 basic exclusion for 2026 and a 40% top rate (26 U.S.C. 2001 and 2010; IRS Revenue Procedure 2025-32). Maryland taxes are deducted on the federal return (26 U.S.C. 2058); Maryland does not deduct federal or state death taxes.
- Lifetime gifts: added to the federal tax base; gift tax on any part above the federal exclusion is credited at the rates in effect at death.
- Small estates and life insurance: no inheritance tax on property from a probate estate of $50,000 or less ($100,000 when the surviving spouse is the only heir, per Maryland Estates and Trusts 5-601), applied only when you say everything passes through probate. Life insurance paid to a named beneficiary other than the estate is exempt from inheritance tax but still counts toward estate tax if the person who died owned the policy.
- Simplifications: bequests not entered are treated as passing to exempt heirs. A nonresident’s inheritance tax is held back. Out-of-state property, Maryland-only QTIP elections and nonresident apportionment follow Form MET 1, and counsel should confirm them.
- Held back, not estimated: a credit for death tax paid to another state, qualified agricultural property and conservation easement rules, and the federal QTIP election and QDOT for a spouse who is not a U.S. citizen.
Worked Example
The example
This is the calculator’s built-in example (the “Reset to example” values). Every figure below is the calculator’s own output for these inputs. Inputs marked (Detailed) are entered in Detailed mode. In Quick estimate, the amounts left to exempt family and to brothers and sisters are not entered, so Exempt Transfers reads $300,000 instead of $4,800,000. Every other figure, including the total, is the same.
Inputs
| Input | Example value |
|---|---|
| Total Estate Value | $7,000,000 |
| Debts and Expenses | $200,000 |
| Lifetime Taxable Gifts | $0 |
| Marital Status at Death | Single or Divorced |
| Left to Children, Grandchildren, Parents, and Other Exempt Family (Detailed) | $4,000,000 |
| Left to Brothers and Sisters (Detailed) | $500,000 |
| Left to Nieces and Nephews | $1,500,000 |
| Number of Nieces and Nephews Sharing This (Detailed) | 3 |
| Left to Other People (Friends, Cousins, Partners) | $500,000 |
| Number of Other People Sharing This (Detailed) | 1 |
| Left to Charity | $300,000 |
| Where the Person Who Died Lived | Maryland Resident |
Results
| Result | Estimate |
|---|---|
| Estimated Total Death Taxes | $240,000 |
| Maryland Inheritance Tax | $200,000 |
| Maryland Estate Tax (After Credit) | $40,000 |
| Maryland Total | $240,000 |
| Federal Estate Tax | $0 |
| Share of Estate | 3.4% |
| Taxed Inheritances (10%) | $2,000,000 |
| Inheritance Tax | $200,000 |
| Exempt Transfers | $4,800,000 |
| Maryland Taxable Estate | $6,500,000 |
| Exclusion Applied | $5,000,000 |
| Estate Tax Before Credit | $240,000 |
| Less Inheritance Tax Credit | $200,000 |
| Net Maryland Estate Tax | $40,000 |
| Maryland Taxes Deducted | $240,000 |
| Federal Taxable Estate | $6,260,000 |
| Federal Exclusion Applied | $15,000,000 |
| Estimated Federal Estate Tax | $0 |
| Maryland Return Likely Required | Yes |
| Federal Return Likely Required | No |
| Maryland Estate Tax Due | 9 months after death |
The calculator summarizes it this way: “The estimated $200,000 inheritance tax is credited against the $240,000 Maryland estate tax, for an estimated Maryland total of $240,000. No federal estate tax is estimated.” Results for your own inputs will differ.
Reviewed by Jeff Judge, CFP®, AEP®, ChFC®, CLU®, Managing Partner, Chesapeake Financial Planners. Last updated November 2, 2026. Tax year 2026.
Frequently Asked Questions
Does Maryland have both an estate tax and an inheritance tax?
Yes. The inheritance tax depends on who receives property; the estate tax depends on the size of the estate. Inheritance tax paid is credited against the estate tax, so the Maryland total is generally the larger of the two.
Who pays Maryland inheritance tax, and who is exempt?
Spouses, children and other lineal descendants and their spouses, parents, grandparents, stepchildren and stepparents, and brothers and sisters are exempt. Most others, including nieces, nephews, cousins, aunts, uncles, and friends, pay 10% of the clear value they receive. A person whose taxable share is $1,000 or less owes nothing.
Do nieces and nephews pay Maryland inheritance tax?
Yes. Nieces and nephews generally pay 10% of the clear value they receive, meaning its value minus their share of expenses. Wills often direct the estate to pay this tax. In the worked example, $2,000,000 of taxed inheritances to nieces, nephews and one other person owes $200,000 of inheritance tax.
How much can a Maryland estate pass tax-free in 2026?
$5,000,000 for deaths in 2026, plus any unused Maryland exclusion inherited from a spouse who died first. The tax is capped at 16% of the amount above the exclusion. In the worked example, a $6,500,000 Maryland taxable estate owes $240,000 before the inheritance tax credit and $40,000 after it.
Does Maryland allow portability between spouses?
Yes. Since 2019, a surviving spouse can use the unused Maryland exclusion of a spouse who died first if the first estate filed a timely Maryland estate tax return electing portability. The federal portability election is separate and is made on a federal Form 706.
How does the federal exemption interact with Maryland’s?
They are separate. For 2026, the federal exclusion is $15,000,000 and Maryland’s is $5,000,000, so many estates owe Maryland estate tax but no federal estate tax. When both apply, the Maryland taxes paid are deducted in figuring the federal tax.
Related planning services: Inheritance, Sale of Business, Financial Planning for Retirees and Pre-Retirees, Financial Planning for Business Owners.
Related calculators: Federal Estate and Gift Tax Calculator, Life Insurance Needs Estimator and Donor-Advised Fund and Charitable Bunching Calculator.
See all financial planning calculators
Want to talk through your own numbers with an adviser?
Important disclosures
This calculator is for educational purposes only and provides a simplified, hypothetical estimate of Maryland inheritance tax, Maryland estate tax, and federal estate tax based on the information you enter and on tax rules for the year shown. It does not consider all factors that may affect your situation, such as asset valuations, deductions, elections, beneficiary designations, and changes in law. It is not tax, legal, or investment advice and is not a substitute for advice from a qualified estate planning attorney or tax professional. Results are not guaranteed.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor. All investing involves risk including loss of principal. No strategy assures success or protects against loss. There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. DiversificationSpreading investments across multiple asset classes, sectors, and geographies so a loss in one area doesn’t devastate your entire portfolio. It’s the financial equivalent of not putting all your eggs in one basket — and it’s one of the few strategies that can reduce risk without necessarily reducing expected returns. does not protect against market risk.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group and Chesapeake Financial Planners are separate entities from LPL Financial.