
What are the best tax strategies for high net worth individuals?
Last reviewed: July 2026
The best tax strategies for high net worth individuals go well beyond maxing a 401(k): coordinated tax-loss harvesting, charitable tools like qualified charitable distributions and donor-advised funds, strategic Roth conversions, backdoor Roth contributions, and systematic gifting. Once your income and wealth cross certain thresholds, the tax code changes in ways that punish ordinary planning, with higher marginal rates, an investment income surtax, and phaseouts. Families with one to five million dollars in net worth routinely leave tens of thousands in tax savings unclaimed each year because they use strategies built for a different income level.
Key Takeaways
- High earners face higher marginal rates, the 3.8% Net Investment Income Tax, and deduction phaseouts that basic planning ignores.
- The 3.8% NIIT applies once modified AGI exceeds $250,000 married filing jointly or $200,000 single.
- Charitable tools like QCDs and donor-advised funds can cut taxable income, not just provide a deduction.
- The biggest gains come from coordinating strategies across multiple years, not optimizing a single tax return.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. As an Accredited Estate Planner®, he has guided high net worth Harford County and Baltimore-area families through advanced tax and estate strategy since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: above a certain level of wealth, the difference between reactive tax preparation and proactive multi-year tax planning is routinely six figures over a lifetime, and almost none of it comes from the strategies people read about first.
Why is tax planning different for high net worth individuals?
Tax planning is different for high net worth individuals because crossing certain income thresholds triggers rules that ordinary strategies were never designed to handle. The same advice that works at moderate incomes can leave large sums on the table once you are in the top brackets.
Several forces stack up. Federal ordinary income tax tops out at 37% above $768,700 for married couples filing jointly in 2026, and adding state tax can push a marginal rate toward or past 50%. The Net Investment Income Tax adds a 3.8% surtax on investment income, interest, dividends, capital gains, and rental income, once modified adjusted gross income exceeds $250,000 for married couples or $200,000 for single filers. As the IRS describes it, "The NIIT applies at a rate of 3.8% to certain net investment income of individuals, estates and trusts that have income above the statutory threshold amounts." On top of that, many deductions and credits phase out at higher incomes, and the Alternative Minimum Tax can pull high earners into a parallel calculation.
The result is that minimizing taxes at this level is less about a single deduction and more about managing income, gains, and timing across years and account types. Standard advice does not address NIIT, phaseouts, or AMT, so high net worth families need strategies built specifically for their situation. As Jeff Judge puts it, "The goal is not to win April 15 but to win the next two decades, which usually means accepting some tax now to avoid much more later."
What advanced tax strategies do high net worth families use?
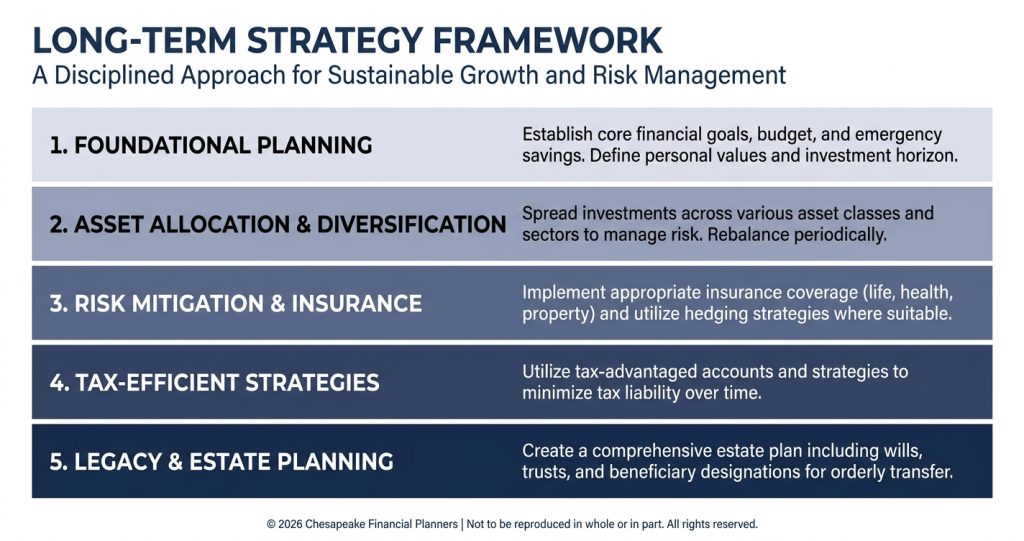
High net worth families use a layered set of strategies that, individually, save modest amounts but together compound into substantial lifetime savings. Each targets a different part of the tax code.
The core tools include:
- Tax-loss harvesting throughout the year. Selling investments that have declined realizes losses that offset capital gains without limit and up to $3,000 of ordinary income annually, with the rest carried forward. Harvesting opportunistically during volatility, rather than only at year-end, captures more, and direct indexing (owning individual stocks instead of a single fund) allows harvesting on individual positions while keeping overall market exposure.
- Qualified charitable distributions (QCDs). Retirees subject to required minimum distributions can direct up to $111,000 per year for 2026 from an IRA straight to qualified charities, satisfying the RMD without the distribution counting as taxable income. Avoiding income is more powerful than taking a deduction, because it lowers adjusted gross income and can keep you under NIIT and Medicare premium thresholds.
- Donor-advised funds for bunching. With the 2026 standard deduction at $32,200 for married couples, many high earners no longer clear it with annual giving. Contributing several years of gifts to a donor-advised fund in one year creates a large itemized deduction that year while you take the standard deduction in others, and funding it with appreciated securities also avoids capital gains tax.
- Strategic Roth conversions. Converting pre-tax IRA money to Roth during temporarily lower-income years, such as between retiring and claiming Social Security, pays tax now at a lower rate to avoid higher rates once RMDs begin, and Roth accounts have no lifetime RMDs.
- Backdoor Roth contributions. Above the Roth income limits (the 2026 phase-out runs $242,000 to $252,000 of modified AGI for married couples), a nondeductible traditional IRA contribution converted to Roth can work, though the pro-rata rule makes professional guidance essential if you hold other pre-tax IRA money.
- Systematic gifting. The 2026 annual gift tax exclusion is $19,000 per recipient, and gifting appreciating assets moves future growth out of your estate.
These strategies are powerful individually but transformative in combination, which is exactly what the R.U.D.D.E.R. Method™ is designed to orchestrate. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and advanced tax strategy lives in Design and Develop, sequenced across years alongside your CPA.
How does coordinating strategies compound the savings?
Coordinating strategies compounds the savings because the tools interact, and sequencing them across years captures benefits that no single move can. The whole is meaningfully greater than the sum of the parts.
Consider a recently retired couple in their early 60s holding several million dollars across pre-tax IRAs, taxable accounts, and cash, with a comfortable annual spending level. In the years before Social Security begins, they can execute Roth conversions up to the top of a target bracket, harvest losses to offset the conversion income, make a large donor-advised fund contribution in a high-conversion year to offset the tax, and begin systematic annual gifting. Once they reach the age for required distributions, they can switch to QCDs instead of ordinary charitable giving, manage RMDs to stay below Medicare premium surcharge thresholds, and continue harvesting and gifting.
Run reactively, year by year, these same tools produce a fraction of their potential. Sequenced deliberately as one multi-year plan, they can shift a substantial amount of lifetime tax, often well into six figures for families at this level, though the exact result depends entirely on the individual's income, holdings, and timing. The point is not any single tactic but the coordination, which is why this work belongs in a comprehensive plan rather than a year-end scramble.
What are the most common high net worth tax mistakes?
The most common high net worth tax mistakes come from short-term thinking, letting taxes drive bad decisions, and going it alone on complex strategies. Avoiding them is as valuable as executing the strategies themselves.
The recurring errors are focusing only on the current year, since minimizing this year's bill can raise your lifetime taxes, so the right frame is multi-decade rather than a single April; letting tax strategy drive investment decisions, because a bad investment is still bad even with a tax benefit attached; waiting until tax season, by which point December 31 has already closed many opportunities that require year-round, quarterly attention; and attempting complex strategies without help, because pitfalls like the backdoor Roth pro-rata rule and multi-year conversion planning genuinely require professional coordination.
The throughline is that advanced tax planning rewards being proactive and integrated. Calculate your effective and marginal rates, project future income and liability, build a multi-year strategy, set quarterly reviews with your CPA and advisor, and integrate tax, investment, and estate planning so the pieces reinforce rather than undercut each other. Once you have built real wealth, the basics are simply not enough.
Related Topics Worth Reading
High net worth tax planning connects to charitable, estate, and Roth strategy. These related topics go deeper.
- How QCDs let retirees give directly from an IRA. How Can I Donate From My IRA Tax-Free?
- Using a donor-advised fund to bunch deductions. How Do Donor-Advised Funds Work for Tax Savings?
- Timing Roth conversions in the pre-RMD window. How do you use the years between retirement and RMDs to reduce lifetime taxes?
- The step-by-step backdoor Roth, including the pro-rata trap. How does a backdoor Roth IRA work, and what is the pro-rata rule?
- How to keep retirement income below the IRMAA thresholds. How does my Social Security claiming decision affect my Medicare premiums?
Frequently Asked Questions
What are the best tax strategies for high net worth individuals?
The best strategies combine tax-loss harvesting, charitable tools like qualified charitable distributions and donor-advised funds, strategic Roth conversions, backdoor Roth contributions, and systematic gifting, all coordinated across multiple years. At higher incomes, basic moves like maxing a 401(k) are not enough because of higher marginal rates, the Net Investment Income Tax, and phaseouts. The largest gains come from sequencing these tools deliberately rather than reacting at year-end.
What is the Net Investment Income Tax?
The Net Investment Income Tax is an additional 3.8% Medicare surtax on investment income, including interest, dividends, capital gains, and rental income, that applies once modified adjusted gross income exceeds $250,000 for married couples filing jointly or $200,000 for single filers. It is a key reason high net worth families work to manage adjusted gross income, since strategies that reduce reportable income, like QCDs, can help keep you below the threshold.
How do donor-advised funds reduce taxes for high earners?
A donor-advised fund lets you contribute several years' worth of charitable giving in a single year, creating a large itemized deduction that year while you take the standard deduction in other years, a technique called bunching. With the 2026 standard deduction at $32,200 for married couples, many high earners cannot clear it with annual giving alone. Funding the donor-advised fund with appreciated securities also avoids capital gains tax while supporting a fair-market-value deduction.
When should high net worth individuals do Roth conversions?
The best time for Roth conversions is usually a temporarily lower-income year, such as between retiring and claiming Social Security or a year with unusually low income, when you can convert pre-tax IRA money at a lower tax rate than you would pay once required distributions begin. Roth accounts also have no lifetime RMDs, giving more control over future income. Converting up to the top of a target bracket, rather than all at once, helps manage the tax cost.
What is the annual gift tax exclusion for 2026?
The annual gift tax exclusion for 2026 is $19,000 per recipient, meaning you can give that amount to any number of people each year without using your lifetime exemption or filing a gift tax return. A married couple can combine to give $38,000 per recipient. Gifting appreciating assets rather than cash is often more powerful, because future growth then occurs outside your taxable estate.
Turning advanced strategy into lasting savings
For high net worth families, taxes are not a once-a-year event but a multi-year discipline, and the difference between reacting and planning is frequently six figures over a lifetime. Tax-loss harvesting, charitable tools, Roth conversions, and gifting each help, but their real power emerges when they are coordinated and sequenced as one plan, integrated with your investments and estate. Jeff Judge and the Chesapeake Financial Planners team help high net worth families across Harford County and the Baltimore metro build that kind of strategy, working alongside their CPAs and attorneys. Schedule a free fit call at chesapeakefp.com.
Please consult your tax professional regarding your specific tax situation.
Roth IRA distributions of earnings are tax-free as long as the distribution is made more than five years after your first Roth IRA contribution and you are at least 59½, or as a result of your disability or death.
A Roth IRA conversion may not be suitable for your situation. The conversion will result in taxation of the converted amount. You should consult with a tax advisor before implementing any Roth IRA conversion strategy.
Want to go deeper? Our Tax Moves for High Earners walks through this step by step.
Prefer a different starting point? Our Tax Strategy Readiness Quiz is worth a look.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


