
Divorce
This Isn’t Starting Over. It’s Taking Control.
You’ve made hard choices. Now you deserve smart guidance, so you can move forward with strength, clarity, and confidence.
See if You’re a Fit
Featured In












You're smart, capable, and have handled more than your fair share of stress lately. Divorce tends to do that; it doesn’t just untangle your relationships; it reshuffles your financial life too. And while you’ve likely tried to “just figure it out” on your own, the stakes now feel higher. You don’t want to guess. You want to get it right.
You may be juggling competing priorities: updating accounts, rethinking retirement, navigating alimony or child support, selling or keeping the house… and all while trying to hold onto a sense of stability. It’s a lot, and it’s personal.
That’s why you need more than just a financial plan. You need a calm, steady voice in the storm. Someone who doesn’t just get the numbers, but understands what’s at stake emotionally, legally, and logistically.

Thomas Cowley
6 days ago
Mark and Jeff have handled my finances for over a decade. They have been great stewards for my investments which have grown substantially. They listen to my goals and give me recommendations and options to carry them out. I highly recommend them.
Jane Towery
3 months ago
I have been extremely pleased with Mark’s services over the last 15 years and would very highly recommend. Mark has taken the time to get to know my needs, interests, long and short term goals. We evaluate my portfolio yearly for any adjustments, reevaluation, or study trends. Mark objectively presents the pros and cons of options, answers questions, and leaves the final decision to me. I have never felt pressured and always appreciate how understood and listened to I have felt. More recently I have had some opportunity to work with Jeff as well. Mark and Jeff present a unified team who want to make your investments work for your needs.

Joyce Ducksworth
5 months ago
I have had the pleasure of entrusting my finances with Jeff and Mark for many years. Their expertise and advice are invaluable. My portfolio has grown significantly and has allowed me to retire comfortably with tremendous financial security. Mark is always available to answer my questions and provide solutions. I highly recommend Chesapeake Financial Planners.
stephen kinsley
5 months ago
Mark and Jeff have been my retirement advisors since 2011 and I could not be happier with them. They are knowledgeable and easy to talk with. They respond quickly to any questions and clearly explain all my options. I have been retired for 5 years and am fully confident that my financial future will continue to improve as it has so far with them. I would recommend them to anyone, and I only wish that I had met them sooner.
Bob Burris
6 months ago
I have been working with Mark and Jeff for 10+ years. I recently asked for a review of my financial plan and was provided outstanding feedback that provided me a much better solution.

Kim Wright
7 months ago
I am delighted with LPL. They've stayed with me for years and Jeff Judge has been exceptionally helpful. I've gotten good advice. He's managed my assets professionally and has always been available answer my questions.
He helped me consolidate several accounts into one manageable asset. He took the guesswork out of what could have been a complicated process.
I trust him to be there and guide me through issues in which I have no expertise. But he does this all the time and has proven to be trustworthy.
I do recommend Mr. Judge. You will not be disappointed.
Sharon Lewis
7 months ago
My husband and I met Mark and Jeff in 2014 when my husband left his job after 23 years. We met with Mark and Jeff to decide where to invest his retirement money. Before that decision was made, they took their time to understand our entire financial picture and based on that they gave us several options on where we could invest. They were very easy to talk with and made the conversation easy to understand. They are easy to get in touch with if you have questions and provide answers quickly. When it came time for me to retire, I also rolled my retirement investments into accounts managed by Mark and Jeff. We have also setup our estate planning as well as long term health planning based on advice we have had in review meetings in the years following our initial meeting. We have even referred our daughter and son in law to them. Highly satisfied with the investment service and customer service.

Andrew Benner
7 months ago
I check in with Mark a couple times a year and he always helps me keep my money that he manages growing. He also helps us with general advise regarding the type of places our 401k money should be (growth vs value, etc)

Mark Gray
9 months ago
Jeff has been helping me since 2014 with life insurance and retirement investment products. After a bad experience with a big insurance company, I found Mark and I’ve been working with him ever since. I’m successfully retired now and will begin drawing on my investments this year. I highly recommend Chesapeake Financial Planners for your retirement planning. – Mark G.
David Carrington
10 months ago
Jeff has been my financial advisor/ planner for several years. He has always guided me in the right direction and I have seen my retirement account continuously moving in the right direction. During the current uncertainty of the financial world right now Jeff has given me peace of mind that I continue to be in a safe and secure position with my finances. Jeff is very professional and quick to respond to my emails. As I approach my retirement years it is comforting to know my finances will be there when I need them.
Matt Hurson
11 months ago
I have been working with Jeff Judge and Chesapeake Financial Planners for about 3 years. Jeff has provided timely and well considered advice and acted promptly when I've needed access and changes to my portfolio. Highly recommend their services.

John Komoroski
12 months ago
We have worked with Jeff at Chesapeake Financial Planners for over 10 years. Throughout that time he has provided valuable investment and retirement information. Our investments have navigated this turbulent market far better than expected. Thank you Jeff.
Charles Gaither
12 months ago
I've been working with Chesapeake Financial Planners for a little over six years, and it's been an outstanding experience. They're knowledgeable, responsive, and consistently provide clear, personalized advice that aligns with my financial goals. Their long-term commitment and reliability have given me real peace of mind.

This is where having the right partner makes all the difference.
Imagine having a clear, organized plan tailored to your new financial reality. One that helps you feel in control again. One that aligns your money with your values, your priorities, and the life you’re building next. We’ll walk beside you with empathy, objectivity, and strategy, helping you make decisions not from fear, but from clarity.
You don’t have to do this alone anymore.
Frequently Asked Questions
How does the state I live in affect how marital assets are divided?
Your state determines whether marital assets are split 50/50 or divided based on what's fair, and the difference is significant.
1. Community property statesNine states — including California, Texas, and Arizona — where assets and income acquired during marriage are generally considered owned equally by both spouses. This has significant implications for divorce, estate planning, and tax filing, and strategies that work in a common law state may need adjustment here.
Community property states: Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin. Alaska has an optional community property system.: Nine states including California, Texas, and Arizona treat most income and assets acquired during the marriage as jointly owned, split equally at divorce regardless of whose name is on the account.
2. Equitable distribution states: The remaining states divide marital assets based on fairness, not equality, weighing factors like income, length of marriage, each spouse's contributions, and future financial needs.
3. Separate property: In both systems, assets owned before the marriage or received as gifts or inheritances are typically treated as separate, unless they've been commingled with marital assets.
4. Estate planning implications: These same rules govern what happens when a spouse dies without a will. State law determines who inherits and how much.
Understanding your state's rules before negotiating a settlement can protect assets you didn't know were at risk. A fiduciary financial planner can help you map what's marital, what's separate, and what needs protection.
How will divorce affect my retirement plan?
Divorce directly affects your retirement accounts, timeline, and strategy. Here's what to expect and how to manage it.
1. Retirement accounts are often marital property: 401(k)s, IRAs, pensions, and other accounts built up during the marriage are typically subject to division.
2. A QDROA Qualified Domestic Relations Order — a court order that allows retirement account assets to be divided between spouses in a divorce without triggering early withdrawal penalties or taxes at the time of the split. Without a QDRO, dividing a 401(k) or pension in divorce can create unintended and costly tax consequences. is required for most employer plans: A Qualified Domestic Relations Order (QDRO) is the legal mechanism for splitting a 401(k) or pensionA defined benefit retirement plan where your employer promises a specific monthly payment for life in retirement, typically based on salary and years of service. Pensions are increasingly rare in the private sector but remain common in government and some union jobs — and if you have one, understanding your payout options is an important financial decision. without triggering taxes or early withdrawal penalties.
3. Your timeline may shift: You may need to save more, work longer, or adjust your investment strategy once the split is final.
4. Spousal Social Security may still apply: If you were married at least 10 years, you may qualify for spousal Social Security benefits even after the divorce is finalized.
5. Taxes and penalties can be avoided: Handled correctly with a QDRO and proper transfers, dividing retirement accounts doesn't trigger penalties. Errors in paperwork or timing can be costly.
6. Your retirement plan needs to reflect your new numbers: Income, expenses, and savings capacity all look different post-divorce. Build a new baseline before making any investment changes.
A fiduciary advisor can help you rebuild a retirement strategy around your actual post-divorce picture, not assumptions from a plan designed for two.
Can I keep the house and still afford my future?
Keeping the house after divorce is possible, but it's often the most expensive decision you'll make, and not always the right one. The answer depends on whether the full cost of ownership fits your post-divorce income and goals.
Run these checks before deciding:
1. Can you cover the real cost? Mortgage principal, interest, taxes, insurance, maintenance, and utilities may be higher than your current share of household expenses.
2. Does it crowd out other priorities? If keeping the house means delaying retirement savings, reducing investments, or skipping an emergency fund, the trade-off may not be worth it.
3. Will your income support it alone? Post-divorce cash flow often looks different. Model your new budget before committing to any asset.
4. What are you giving up in the settlement? Homes are illiquid. Taking the house may mean trading away retirement accounts or cash that would serve you better.
5. What do the next five years look like? Kids aging out, a job change, or a move could make the home more of a burden than an anchor.
Keeping the house can make sense. So can letting it go. The decision should be financial, not just emotional.
How do I know if I’m getting an equitable settlement in my divorce?
You'll know you have an equitable settlement when you've accounted for after-tax value, future income, and long-term financial stability, not just the dollar amounts on each side of the ledger.
Seven things to evaluate before agreeing:
1. Complete asset inventory: Make sure all marital assets and debts are on the table, including retirement accounts, equity compensation, real estate, business interests, and insurance.
2. Tax-adjusted value: Two assets may look equal but have very different after-tax worth. A pre-tax 401(k) and an after-tax brokerage account are not the same.
3. Future income capacity: A settlement that leaves you with illiquid assets and no cash flow is not equitable, even if the totals match.
4. Long-term projections: Can you afford retirement, healthcare, and housing on your post-settlement resources? Run the numbers out 10, 20, and 30 years.
5. Support structure: How does spousal or child support factor into your overall cash flow? Short-term support can mask a weak settlement.
6. Stress testing: Your plan should hold up under market downturns, unexpected expenses, or a gap in employment.
7. Emotional detachment: The house, the business, or a particular account may feel like a win. The question is whether it actually supports your financial future.
A Certified Divorce Financial Analyst can help you pressure-test the numbers before you sign.
What happens to our investments after divorce?
Investment accounts accumulated during the marriage are typically subject to division, and how they're divided has real tax and long-term financial consequences.
1. Division follows state law: Community property states split marital investments 50/50. Equitable distribution states divide based on factors like income, contribution, and financial need.
2. Pre-tax and after-tax accounts aren't equal: A traditional 401(k) and a brokerage account with the same balance have very different net values once taxes are considered.
3. Employer retirement plans require a QDRO: A Qualified Domestic Relations Order is the legal instrument needed to split a 401(k) or pension without triggering taxes or penalties.
4. Joint accounts must be retitled or closed: Leaving joint accounts open after separation creates legal and financial risk. Accounts need to be properly separated as part of the settlement.
5. Your investment strategy needs a reset: Risk tolerance, time horizon, and goals are different now. Build a new strategy around your actual situation, not the old plan.
6. Beneficiary designations must be updated immediately: Failing to update beneficiariesThe people or entities designated to receive your assets when you die — through retirement accounts, life insurance policies, or trusts. Keeping beneficiary designations current is one of the simplest but most overlooked parts of estate planning, and outdated designations can completely override what your will says. on retirement accounts and insurance can send assets to the wrong person regardless of the divorce decree.
Get the tax structure and account titling right during settlement. Fixing mistakes after the fact is expensive.
What taxes should I consider when dividing assets?
Not all assets are equal when taxes are involved. A $500,000 traditional 401(k) and a $500,000 brokerage account look identical on paper but deliver very different after-tax value.
1. Pre-tax vs. after-tax accounts: Traditional retirement account distributions are taxed as ordinary income. Brokerage account gains are often taxed at lower capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. rates. The difference matters when deciding which assets to take.
2. Capital gains exposure: Taxable accounts carry embedded gains. Receiving appreciated assets means you'll owe taxes when you eventually sell, so factor that into the settlement value.
3. Early withdrawal penalties: Taking retirement funds before age 59½ triggers a 10% IRS penalty in most cases. A properly executed QDRO avoids this when dividing employer retirement plans.
4. Roth vs. traditional accounts: Roth accounts offer tax-free withdrawals in retirement. Depending on your future tax bracket, Roth assets can be worth more than a traditional account with the same balance.
5. Real estate: Capital gains exclusions and state rules affect your exposure if you sell. If you keep the home, account for future property taxes and depreciation recaptureWhen you sell a rental property, the IRS requires you to pay tax on depreciation deductions you claimed during ownership — at a rate of up to 25%, on top of any capital gains tax. Many real estate investors are caught off guard by this additional tax, which is why planning ahead for a property sale is essential..
6. Business interests and deferred comp: RSUs, equity stakes, and deferred compensationAn arrangement where a portion of your income is set aside today and paid out at a future date — typically retirement — when you may be in a lower tax bracket. Non-qualified deferred compensation plans are common among executives, but they carry real risk: if the company goes bankrupt, you're an unsecured creditor for those funds. require CPA coordination to structure the division with minimal tax drag.
7. Divorce timing: Whether your divorce is finalized before or after December 31 affects your filing status and tax rate for the full year.
How do I protect myself financially during divorce?
Protecting yourself financially during divorce starts with getting organized and making decisions based on facts, not pressure or emotion.
Seven steps to take now:
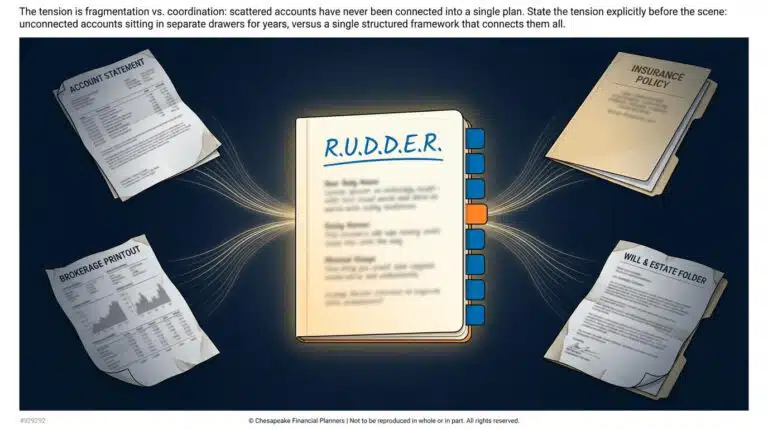
1. Gather all financial records: Collect statements for every account, debt, retirement plan, tax return, insurance policy, and property title. Do this before negotiations begin.
2. Know the real value of what you're negotiating: A $100,000 IRA is not the same as $100,000 in cash. Pre-tax accounts, illiquid assets, and appreciated investments all have different net values.
3. Build your own financial baseline: Know your income, monthly expenses, and what your cash flow looks like on your own. Don't negotiate until you have a clear picture.
4. Separate your credit and accounts: Open accounts in your name only. Close or remove yourself from joint debt. Consider a credit freeze if needed.
5. Don't let urgency drive decisions: Rushed agreements favor the party applying pressure. Slow down, review the full picture, and don't sign anything you don't fully understand.
6. Update your estate documents and beneficiaries: Wills, powers of attorney, and beneficiary designations should be reviewed and updated as the process moves forward.
7. Build the right advisory team: Your attorney handles legal protection. A fiduciary financial planner ensures the settlement actually supports what comes next.
What’s the best way to divide assets in a divorce equitably?
The best way to divide assets in a divorce equitably is to evaluate what each asset is actually worth to your future, not just its face value today. Equal splits don't always produce equal outcomes.
Seven steps to get there:
1. Build a complete inventory: List all assets and debts, including bank accounts, retirement plans, real estate, business interests, personal property, stock options, and insurance.
2. Distinguish marital from separate property: Assets acquired during the marriage are generally marital property. Gifts, inheritances, and premarital assets may be separate, unless commingled.
3. Adjust for taxes and liquidity: Two accounts with the same balance can have very different after-tax and after-liquidation values. Account for what you'll actually keep.
4. Look at income, not just net worth: An asset that doesn't generate cash flow may look good on paper but create financial strain day-to-day.
5. Balance immediate needs against long-term stability: Keeping the house or a particular account may feel like a win in the short term but limit your financial flexibility for years.
6. Use professional financial modeling: A Certified Divorce Financial Analyst (CDFA) can run settlement scenarios and show you the 5-, 10-, and 20-year implications of different splits.
7. Factor in support, Social Security, and retirement timing: The full picture includes future income sources, not just today's asset values.
Do I need a new financial approach post-divorce?
Yes, divorce requires a new financial approach. Your income, expenses, goals, and risk tolerance have all changed, so a plan built around your old life won't serve your new one.
Six areas to rebuild:
1. Cash flow and budget: Your monthly income and expenses look different now. Start with an honest picture of what comes in and what goes out on your own.
2. Savings and investment strategy: Your risk tolerance, time horizon, and account structure may all need adjustment. Don't assume the old allocation still fits.
3. Retirement timeline: Run new projections based on your assets post-settlement, your expected savings rate, and your Social Security options.
4. Insurance and legal documents: Update beneficiary designations, wills, powers of attorney, and coverage for life, disability, and health.
5. Emergency reserves: If reserves were shared, rebuild them. A solo financial plan needs a buffer sized for one income, not two.
6. Long-term goals: Career changes, housing decisions, education funding, and retirement timing may all look different post-divorce. Your plan should reflect what you actually want now.
This isn't starting over. It's building a plan that fits your current reality.
What financial documents do I need to gather before filing for divorce?
Gather these financial records before filing for divorce. Having them organized from the start gives you leverage in negotiations and protects you from surprises.
Income and employment:
- Pay stubs (last 3-6 months), W-2s and 1099s, and tax returns (last 2-3 years)
- Business income statements if self-employed
- Bonus and severance agreements
Bank and cash accounts:
- Checking, savings, money market, and CD statements
- Online or app-based account records
Retirement and investment accounts:
- 401(k), 403(b), 457(b), IRA, and pension statements
- Brokerage and taxable investment accounts
- RSUs, stock options, and deferred compensation plans
Real estate and property:
- Mortgage statements, deed and title documents, and HELOC statements
- Appraisals for primary residence and any rental or vacation properties
Debts and liabilities:
- Credit card statements, auto loans, student loans, and personal loans
- Business debts and any joint or co-signed obligations
Insurance:
- Life, disability, long-term care, health, property, auto, and umbrella policies
Legal and estate documents:
- Prenuptial or postnuptial agreements, trust documents, wills, and powers of attorney
Monthly expenses:
- Utilities, childcare, tuition, subscriptions, and estimated future living costs
The more complete your documentation, the stronger your position when negotiations begin.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
Ready to stop second-guessing and start feeling in control?
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.