

Financial Planning For Retirees & Pre-Retirees
Retirement Isn’t the End—It’s the Start of Living Life on Your Terms
When the finish line moves, the rules change. We'll help you make decisions you won't second-guess later.
See if You’re a Fit
Featured In











You’ve worked hard, made smart moves, and built a life you’re proud of. But as retirement approaches—or begins—you’re staring down a whole new kind of complexity. Questions about income, taxes, healthcare, and legacy start to pile up, and the answers aren’t always straightforward.
Maybe you've pieced together advice from HR packets, online calculators, and well-meaning friends. Maybe you’ve avoided thinking about it too much—because, let’s face it, this stuff can get overwhelming fast. You're not alone in feeling this way. This is where real clarity begins.

Thomas Cowley
1 week ago
Mark and Jeff have handled my finances for over a decade. They have been great stewards for my investments which have grown substantially. They listen to my goals and give me recommendations and options to carry them out. I highly recommend them.
Jane Towery
3 months ago
I have been extremely pleased with Mark’s services over the last 15 years and would very highly recommend. Mark has taken the time to get to know my needs, interests, long and short term goals. We evaluate my portfolio yearly for any adjustments, reevaluation, or study trends. Mark objectively presents the pros and cons of options, answers questions, and leaves the final decision to me. I have never felt pressured and always appreciate how understood and listened to I have felt. More recently I have had some opportunity to work with Jeff as well. Mark and Jeff present a unified team who want to make your investments work for your needs.

Joyce Ducksworth
5 months ago
I have had the pleasure of entrusting my finances with Jeff and Mark for many years. Their expertise and advice are invaluable. My portfolio has grown significantly and has allowed me to retire comfortably with tremendous financial security. Mark is always available to answer my questions and provide solutions. I highly recommend Chesapeake Financial Planners.
stephen kinsley
5 months ago
Mark and Jeff have been my retirement advisors since 2011 and I could not be happier with them. They are knowledgeable and easy to talk with. They respond quickly to any questions and clearly explain all my options. I have been retired for 5 years and am fully confident that my financial future will continue to improve as it has so far with them. I would recommend them to anyone, and I only wish that I had met them sooner.
Bob Burris
6 months ago
I have been working with Mark and Jeff for 10+ years. I recently asked for a review of my financial plan and was provided outstanding feedback that provided me a much better solution.

Kim Wright
7 months ago
I am delighted with LPL. They've stayed with me for years and Jeff Judge has been exceptionally helpful. I've gotten good advice. He's managed my assets professionally and has always been available answer my questions.
He helped me consolidate several accounts into one manageable asset. He took the guesswork out of what could have been a complicated process.
I trust him to be there and guide me through issues in which I have no expertise. But he does this all the time and has proven to be trustworthy.
I do recommend Mr. Judge. You will not be disappointed.
Sharon Lewis
7 months ago
My husband and I met Mark and Jeff in 2014 when my husband left his job after 23 years. We met with Mark and Jeff to decide where to invest his retirement money. Before that decision was made, they took their time to understand our entire financial picture and based on that they gave us several options on where we could invest. They were very easy to talk with and made the conversation easy to understand. They are easy to get in touch with if you have questions and provide answers quickly. When it came time for me to retire, I also rolled my retirement investments into accounts managed by Mark and Jeff. We have also setup our estate planning as well as long term health planning based on advice we have had in review meetings in the years following our initial meeting. We have even referred our daughter and son in law to them. Highly satisfied with the investment service and customer service.

Andrew Benner
7 months ago
I check in with Mark a couple times a year and he always helps me keep my money that he manages growing. He also helps us with general advise regarding the type of places our 401k money should be (growth vs value, etc)

Mark Gray
10 months ago
Jeff has been helping me since 2014 with life insurance and retirement investment products. After a bad experience with a big insurance company, I found Mark and I’ve been working with him ever since. I’m successfully retired now and will begin drawing on my investments this year. I highly recommend Chesapeake Financial Planners for your retirement planning. – Mark G.
David Carrington
10 months ago
Jeff has been my financial advisor/ planner for several years. He has always guided me in the right direction and I have seen my retirement account continuously moving in the right direction. During the current uncertainty of the financial world right now Jeff has given me peace of mind that I continue to be in a safe and secure position with my finances. Jeff is very professional and quick to respond to my emails. As I approach my retirement years it is comforting to know my finances will be there when I need them.
Matt Hurson
11 months ago
I have been working with Jeff Judge and Chesapeake Financial Planners for about 3 years. Jeff has provided timely and well considered advice and acted promptly when I've needed access and changes to my portfolio. Highly recommend their services.

John Komoroski
12 months ago
We have worked with Jeff at Chesapeake Financial Planners for over 10 years. Throughout that time he has provided valuable investment and retirement information. Our investments have navigated this turbulent market far better than expected. Thank you Jeff.
Charles Gaither
12 months ago
I've been working with Chesapeake Financial Planners for a little over six years, and it's been an outstanding experience. They're knowledgeable, responsive, and consistently provide clear, personalized advice that aligns with my financial goals. Their long-term commitment and reliability have given me real peace of mind.
We take the time to understand where you are now—not just financially, but personally. What matters to you? What keeps you up at night? Whether you’re afraid of running out of money, not maximizing what you’ve saved, or just don’t want to screw things up, that’s normal. Retirement isn't a one-time decision. It's a series of choices that deserve better than guesswork.
With the right guidance, your financial life can finally feel calm, organized, and empowering. You’ll know where your income is coming from, how to reduce unnecessary taxes, when to take Social Security, and how to protect what you’ve built. More importantly, you’ll feel confident making big life decisions—without second-guessing every move.
No judgment. Just honest answers, thoughtful planning, and an experienced partner in your corner whenever life throws a curveball.
Let’s help you stop worrying about “what if” and start enjoying “what now.”
Frequently Asked Questions
How much money do I need to retire comfortably?
Most people need roughly 25 times their expected annual spending saved before they can retire comfortably. So if you plan to spend $100,000 a year, that's a $2.5 million target — but the right number depends on your actual life. Jeff Judge often tells clients that the formula is less important than the inputs: when you want to retire, what income sources you'll have, how much healthcare will cost, and what you want to spend in your 60s versus your 80s. The real questions are what Social Security, pensions, or rental income will cover, how taxes and inflation will affect withdrawals, and whether your spending will shift over time. A detailed retirement income plan built around your real numbers will always be more useful than someone else's rule of thumb.
Should I take Social Security at 62 or wait until 70?
For most people who can afford to wait, delaying Social Security increases lifetime income — but the right answer depends on your health, income needs, and how long you expect to live. Claiming at 62 locks in a permanently reduced benefit. Waiting until 70 earns the maximum monthly amount. According to the Social Security Administration, benefits grow by roughly 8% for each year you delay past your full retirement age. That's a meaningful increase, especially for married couples where the higher earner's benefit also determines the survivor benefit. The break-even age — where waiting pays off more than claiming early — typically falls in your late 70s. If you're healthy and have other income to draw from in the gap years, waiting almost always wins. If your health is a concern or your portfolio can't bridge the gap, claiming earlier may make more sense.
Can I retire early without running out of money?
Yes, you can retire early without running out of money — but only with a plan built for a longer runway than most retirement plans assume. Retiring before 60 typically means 35 or more years of withdrawals, limited access to retirement accounts before age 59½ without penalty, and a healthcare gap before Medicare starts at 65. Sequence of returns riskThe danger that poor investment returns early in retirement — when you're actively withdrawing — can permanently damage your portfolio even if long-term average returns look fine. The years just before and just after retirement are uniquely vulnerable, which is why having a cash buffer or short-term income strategy matters. is also higher: a market drop in the first few years of early retirement can do lasting damage if you're drawing income simultaneously. Jeff Judge frequently works with clients in their early 50s who want to retire by 55 — and the ones who succeed are the ones who plan the income bridge, not just the portfolio size. A sustainable early retirement plan coordinates tax-efficient withdrawals, stress-tests for bad market years, and builds in enough flexibility to adapt as life changes.
How do I plan for rising healthcare costs in retirement?
Healthcare is consistently one of the most underestimated expenses in retirement, and it tends to grow faster than general inflation. Planning for it means more than just picking a Medicare plan. If you retire before 65, you'll need a strategy to bridge the gap — private coverage or marketplace plans can cost several hundred dollars a month per person depending on your income and health. Once you reach Medicare, the choices between Original Medicare, supplement plans, and Advantage plans carry real cost differences based on how much you travel and how often you use care. An HSA, if you've been contributing to one during your working years, is one of the most tax-efficient tools for covering healthcare costs in retirement: contributions are pre-tax, growth is tax-free, and qualified medical withdrawals are also tax-free. Long-term care is the biggest wildcard — a single extended care event can run tens of thousands of dollars per year, and most families are unprepared for it.
When should I change my investments before retiring?
Ideally, you start adjusting your investments 5 to 10 years before retirement, while you still have time to make changes gradually rather than reactively. That window is sometimes called the retirement red zone — close enough that a major loss would be hard to recover from, but far enough out that you can still reduce risk thoughtfully. There are four things worth doing in that window. First, reduce concentration in volatile assets without abandoning growth entirely, since you still need your portfolio to outpace inflation for decades. Second, segment your savings into time-based buckets so that near-term income isn't dependent on assets that could drop sharply in a downturn. Third, align your investment mix with your planned withdrawal order across taxable, Roth, and IRA accounts. Fourth, stress-test your plan against bad market scenarios — not just the average case. Jeff Judge often reminds clients that the goal isn't to be conservative by default, it's to be deliberate about where you can and can't afford a loss.
Will my money last if the market crashes during retirement?
Yes, your retirement savings can survive a market crash — if your plan was built to handle one. The biggest threat isn't the crash itself, it's sequence of returns risk: when a market downturn hits in the first few years of retirement and you're simultaneously drawing income, the damage compounds in a way that's hard to recover from. There are four structural defenses that matter. Keep one to two years of spending in conservative assets so you're never forced to sell stocks at the bottom. Use a bucket approach to separate short-term income from long-term growth assets. Build flexible withdrawal rules that allow you to reduce distributions in bad years without derailing the plan. And stress-test the plan against historical crashes — Jeff Judge runs these scenarios with clients before they retire, not after, because the decisions you make in the two years before retirement often matter more than anything else.
How can I reduce taxes on my retirement withdrawals?
Reducing taxes on retirement withdrawals comes down to controlling which accounts you draw from, in what order, and in what years. The sequence matters: drawing from taxable accounts first, then tax-deferred accounts like a traditional IRA or 401(k), and finally Roth accounts can significantly reduce your lifetime tax bill. Roth conversions in the years between retirement and when Required Minimum DistributionsMandatory annual withdrawals from tax-deferred retirement accounts — like traditional IRAs and 401(k)s — that the IRS requires starting at age 73. RMDs are taxed as ordinary income, and failing to take them triggers a steep penalty, making proactive RMD planning a critical part of any retirement income strategy. begin are often the most powerful lever — you're filling low-bracket space before Social Security and RMDs push your income higher. Qualified Charitable DistributionsDirect transfers from an IRA to a qualified charity, available to account holders age 70½ and older. QCDs can satisfy your Required Minimum Distribution while excluding that amount from your taxable income — a powerful combination for charitably-inclined retirees looking to manage their tax bracket. let people over age 70½ donate directly from an IRA, satisfying RMDShort for Required Minimum Distribution — the annual withdrawal the IRS mandates from tax-deferred accounts starting at age 73. Planning for RMDs well in advance — through Roth conversions, Qualified Charitable Distributions, or strategic income management — can meaningfully reduce your lifetime tax burden. requirements without counting the distribution as taxable income. In years with lower income, it's often worth harvesting capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. from taxable accounts at the 0% or 15% rate before other income sources kick in. Optimizing Social Security timing ties into all of this — delaying benefits while converting Roth assets in the gap years is a strategy Jeff Judge uses regularly with pre-retirees in the five years before they stop working.
How do I create reliable income from my retirement savings?
Creating reliable retirement income means building a system that replaces your paycheck — one that blends multiple sources, adapts to market swings, and stays tax-efficient over decades. The foundation is knowing what guaranteed income you have: Social Security, a pensionA defined benefit retirement plan where your employer promises a specific monthly payment for life in retirement, typically based on salary and years of service. Pensions are increasingly rare in the private sector but remain common in government and some union jobs — and if you have one, understanding your payout options is an important financial decision., or rental income form the base. Your portfolio then fills the gap between that guaranteed income and your spending needs. A bucket approach helps here: short-term income stays in conservative holdings you won't need to sell in a downturn; mid- and long-term assets stay invested for growth. The withdrawal sequence across your IRA, Roth, and brokerage accounts affects your taxes every year, not just this year. Jeff Judge builds income plans that coordinate all of these together — because in his experience, most people who run out of money in retirement don't do so because their portfolio was too small, they do so because their withdrawal strategy was too rigid to adapt when life changed.
How do I make sure my retirement savings last 30 years?
Making retirement savings last 30 years requires more than hitting a big number — it requires a plan that adapts as markets, taxes, and your life change. A rigid 4% withdrawal rule applied year after year doesn't hold up in practice; real longevity planning means adjusting withdrawals based on market conditions, spending priorities, and account balances. Minimize taxes by sequencing withdrawals across taxable, tax-deferred, and Roth accounts rather than drawing from each proportionally. Keep enough in conservative assets to cover near-term spending so you're not forced to sell at a loss in a downturn. Plan for inflation explicitly — not just today's spending, but what your costs will look like in year 20. And review the plan regularly; life changes, markets change, and what made sense at 65 may need adjustment at 75. Jeff Judge has watched clients with modest portfolios outlast clients with larger ones because they had a disciplined, adaptive income strategy rather than a static one.
What’s the 4% rule and does it still work in retirement?
The 4% ruleA retirement guideline suggesting you can safely withdraw 4% of your portfolio each year without running out of money over a 30-year retirement. It's a useful starting point, but your actual safe withdrawal rate depends on your specific situation, timeline, and market conditions. is a retirement withdrawal guideline that suggests withdrawing 4% of your portfolio in your first year of retirement, then adjusting that amount for inflation each year after. It was derived from historical market data and designed to give a portfolio at least a 95% chance of lasting 30 years. It's a useful benchmark, but it's not a plan. The rule assumes a fixed spending rate, ignores taxes, and doesn't account for income from Social Security, pensions, or part-time work. It also assumes a specific asset allocationHow you divide your investments among different asset classes — stocks, bonds, real estate, cash — to balance risk and return based on your goals, timeline, and comfort with volatility. Getting your allocation right is one of the most important investment decisions you'll make, and it should shift over time as your life changes. and a 30-year horizon — neither of which may match your situation. Today's retirees often face longer retirements, higher healthcare costs, and more tax complexity than the original research accounted for. Jeff Judge uses the 4% rule as a starting point to frame the conversation, then stress-tests each client's actual numbers with flexible withdrawal modeling and tax-coordinated planning.
What’s the safest way to withdraw from my retirement accounts?
The safest withdrawal strategy coordinates the order, timing, and amount of withdrawals across all your accounts to minimize taxes and reduce the risk of running out of money. Draw from taxable accounts first in most cases, then tax-deferred accounts like a traditional IRA or 401(k), and hold Roth accounts for last since they have no required distributions and grow tax-free. Keep one to two years of planned spending in conservative assets so you're never forced to sell growth holdings during a market drop. Use flexible guardrails rather than a fixed withdrawal rate — when markets drop, reducing distributions even slightly can meaningfully extend the life of the portfolio. Time Social Security strategically, because delaying benefits reduces how much you need to pull from the portfolio in early retirement years. Build Required Minimum Distributions into the plan from the start; they're not optional, and an unplanned RMD can push you into a higher tax bracket in a year you least expect it.
Should I do Roth conversions before I retire?
For most people approaching retirement, yes — Roth conversions are worth doing before you retire, and the window between your last paycheck and your first Required Minimum Distribution is often the best time to act. In those gap years, your taxable income typically drops before Social Security begins and before RMDs from a traditional IRA or 401(k) force distributions you didn't choose. Converting pre-tax assets to Roth during that window fills low tax brackets at today's rates rather than higher rates later. Roth balances don't have Required Minimum Distributions, which gives you more control over taxable income in retirement and can help keep Medicare IRMAAIncome-Related Monthly Adjustment Amount — a surcharge added to your Medicare Part B and Part D premiums if your income exceeds certain thresholds. Based on your income from two years prior, IRMAA can add thousands of dollars per year to your Medicare costs, making income management in the years before Medicare enrollment a critical planning opportunity. surcharges lower. For clients who want to leave assets to heirs, Roth accounts are generally more tax-efficient to inherit than traditional IRAs. Jeff Judge typically starts the Roth conversionMoving money from a traditional pre-tax IRA to a Roth IRA, paying income taxes now in exchange for tax-free growth and withdrawals in the future. Conversions make the most sense when your current tax rate is lower than what you expect in the future — making the years between retirement and RMD age a prime window for strategic action. conversation with clients in their late 50s — waiting until retirement to start planning means losing two to five years of the best conversion window available.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
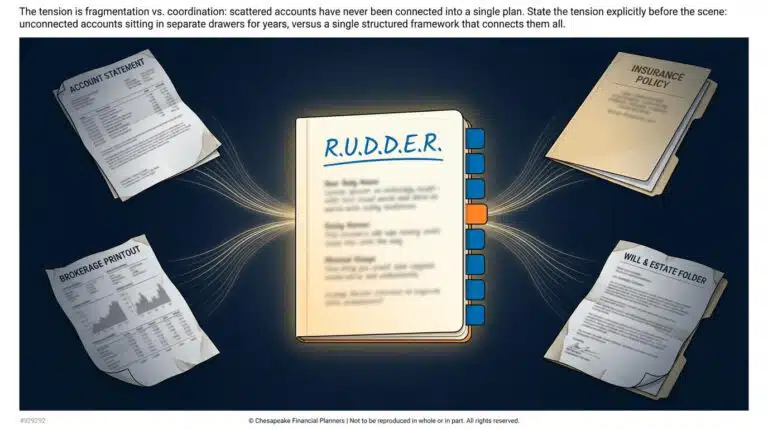
Ready to stop second-guessing and start feeling in control?
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.