
Windfall
Sudden Wealth? Let’s Turn This Moment into a Life Well Lived.
You didn’t ask for this complexity, but you deserve clarity, calm, and confidence as you navigate it.
See if You’re a Fit
Featured In












You’ve just come into a significant amount of money, maybe from an inheritance, a settlement, or an unexpected windfall like a lottery win. And while people might think it’s all joy and freedom, you know the truth: it’s also overwhelming.
Sudden wealth brings more questions than answers:
- What should I do first? What about taxes?
- Will this change how people see me or how I see myself?
- What if I make the wrong decision and it’s gone?
You’re not alone. And no, you don’t have to figure this out on your own.

Thomas Cowley
6 days ago
Mark and Jeff have handled my finances for over a decade. They have been great stewards for my investments which have grown substantially. They listen to my goals and give me recommendations and options to carry them out. I highly recommend them.
Jane Towery
3 months ago
I have been extremely pleased with Mark’s services over the last 15 years and would very highly recommend. Mark has taken the time to get to know my needs, interests, long and short term goals. We evaluate my portfolio yearly for any adjustments, reevaluation, or study trends. Mark objectively presents the pros and cons of options, answers questions, and leaves the final decision to me. I have never felt pressured and always appreciate how understood and listened to I have felt. More recently I have had some opportunity to work with Jeff as well. Mark and Jeff present a unified team who want to make your investments work for your needs.

Joyce Ducksworth
5 months ago
I have had the pleasure of entrusting my finances with Jeff and Mark for many years. Their expertise and advice are invaluable. My portfolio has grown significantly and has allowed me to retire comfortably with tremendous financial security. Mark is always available to answer my questions and provide solutions. I highly recommend Chesapeake Financial Planners.
stephen kinsley
5 months ago
Mark and Jeff have been my retirement advisors since 2011 and I could not be happier with them. They are knowledgeable and easy to talk with. They respond quickly to any questions and clearly explain all my options. I have been retired for 5 years and am fully confident that my financial future will continue to improve as it has so far with them. I would recommend them to anyone, and I only wish that I had met them sooner.
Bob Burris
6 months ago
I have been working with Mark and Jeff for 10+ years. I recently asked for a review of my financial plan and was provided outstanding feedback that provided me a much better solution.

Kim Wright
7 months ago
I am delighted with LPL. They've stayed with me for years and Jeff Judge has been exceptionally helpful. I've gotten good advice. He's managed my assets professionally and has always been available answer my questions.
He helped me consolidate several accounts into one manageable asset. He took the guesswork out of what could have been a complicated process.
I trust him to be there and guide me through issues in which I have no expertise. But he does this all the time and has proven to be trustworthy.
I do recommend Mr. Judge. You will not be disappointed.
Sharon Lewis
7 months ago
My husband and I met Mark and Jeff in 2014 when my husband left his job after 23 years. We met with Mark and Jeff to decide where to invest his retirement money. Before that decision was made, they took their time to understand our entire financial picture and based on that they gave us several options on where we could invest. They were very easy to talk with and made the conversation easy to understand. They are easy to get in touch with if you have questions and provide answers quickly. When it came time for me to retire, I also rolled my retirement investments into accounts managed by Mark and Jeff. We have also setup our estate planning as well as long term health planning based on advice we have had in review meetings in the years following our initial meeting. We have even referred our daughter and son in law to them. Highly satisfied with the investment service and customer service.

Andrew Benner
7 months ago
I check in with Mark a couple times a year and he always helps me keep my money that he manages growing. He also helps us with general advise regarding the type of places our 401k money should be (growth vs value, etc)

Mark Gray
9 months ago
Jeff has been helping me since 2014 with life insurance and retirement investment products. After a bad experience with a big insurance company, I found Mark and I’ve been working with him ever since. I’m successfully retired now and will begin drawing on my investments this year. I highly recommend Chesapeake Financial Planners for your retirement planning. – Mark G.
David Carrington
10 months ago
Jeff has been my financial advisor/ planner for several years. He has always guided me in the right direction and I have seen my retirement account continuously moving in the right direction. During the current uncertainty of the financial world right now Jeff has given me peace of mind that I continue to be in a safe and secure position with my finances. Jeff is very professional and quick to respond to my emails. As I approach my retirement years it is comforting to know my finances will be there when I need them.
Matt Hurson
11 months ago
I have been working with Jeff Judge and Chesapeake Financial Planners for about 3 years. Jeff has provided timely and well considered advice and acted promptly when I've needed access and changes to my portfolio. Highly recommend their services.

John Komoroski
12 months ago
We have worked with Jeff at Chesapeake Financial Planners for over 10 years. Throughout that time he has provided valuable investment and retirement information. Our investments have navigated this turbulent market far better than expected. Thank you Jeff.
Charles Gaither
12 months ago
I've been working with Chesapeake Financial Planners for a little over six years, and it's been an outstanding experience. They're knowledgeable, responsive, and consistently provide clear, personalized advice that aligns with my financial goals. Their long-term commitment and reliability have given me real peace of mind.

This part of your life calls for steady thinking, wise planning, and a partner who understands the emotional and financial weight of what you’re carrying.
We help people like you step back, breathe deeply, and build a thoughtful, intentional plan. A plan that protects your values, empowers your choices, and gives you back your time and peace of mind.
You’ve already made it through the big moment. Now it’s time to make it count.
Frequently Asked Questions
How can a planner help me manage sudden wealth?
A financial planner helps you turn sudden wealth into a lasting advantage by slowing you down before you make irreversible decisions, then building a tax-efficient, values-aligned plan around what the money is really for.
What that looks like in practice:
1. Pause before acting: Park funds safely while you assess your options and give yourself time to think clearly.
2. Define the purpose: Retirement? A career change? Generational wealth? Clarity here drives every other decision.
3. Manage taxes and timing: Roth conversions, charitable giving, and income spreading can reduce what you owe across years.
4. Set boundaries: We coach clients on how to respond when family or friends start asking.
5. Build a comprehensive plan: We integrate the windfall into your full financial picture, from investments to estate documents.
Sudden wealth is a chapter, not the whole story. A planner helps you write the rest of it with intention.
How can I avoid losing my inheritance?
Protecting an inheritance starts with moving deliberately, titling assets correctly, and understanding the tax treatment before you act.
1. Don't rush: Park funds in a safe, liquid account for the first 30-60 days. That window is when the most costly mistakes happen.
2. Keep inherited assets separate: Mixing inherited funds with joint accounts can convert them to marital property in a divorce.
3. Know the tax rules before selling: Inherited investments often carry a step-up in cost basis, which can reduce capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. significantly. Inherited retirement accounts have distinct distribution timelines.
4. Avoid obligation-driven decisions: Grief and family pressure are real forces. Neither should drive financial moves.
5. Update your full picture: Review titling, beneficiariesThe people or entities designated to receive your assets when you die — through retirement accounts, life insurance policies, or trusts. Keeping beneficiary designations current is one of the simplest but most overlooked parts of estate planning, and outdated designations can completely override what your will says., estate documents, and how the inheritance changes your overall plan.
Jeff often sees clients skip these steps and watch the money quietly erode over two or three years.
Should I pay off debt or invest my inheritance?
Whether to pay off debt or invest your inheritance depends on one number above all: the interest rate on your debt.
High-rate debt (credit cards, personal loans above 6-7%) almost always deserves payoff first — the guaranteed return beats most investment alternatives. Low-rate debt like a mortgage is different; investing may compound faster than what you'd save in interest. Most people end up doing a mix: pay off high-rate debt, keep a cash buffer, invest the rest.
Factor in your tax strategy too. Paying down a mortgage reduces deductions. Some investment accounts offer tax advantages that shift the math. And don't ignore the emotional side — some clients feel genuinely freer with zero debt, even when the numbers say otherwise. That clarity has real value.
We help you structure the split to reduce taxes and support your bigger goals.
What should I do first with inherited money or a windfall?
The first thing to do with inherited money or a windfall is nothing: don't make major financial moves for at least 30 days. Park the funds somewhere safe and give yourself space to think.
After that pause, work through these steps:
1. Identify what you received: Cash, real estate, a retirement account, and stock each have different tax rules and timelines.
2. Meet with a planner and tax advisor together: Does the asset have a step-up in basisWhen you inherit an asset, your cost basis for tax purposes is reset to the asset's fair market value at the date of the original owner's death. This effectively eliminates capital gains taxes on all appreciation that occurred during the decedent's lifetime — a significant benefit that shapes many estate planning strategies.? Are distributions required? Should it be retitled or sold?
3. Define what the money is for: Short-term needs, long-term goals, or generational planning — your answer shapes every decision that follows.
4. Manage the downside first: Review insurance, estate documents, and risk before you invest or give anything away.
5. Build a flexible plan: Once you have clarity, turn the windfall into a purposeful strategy that holds up over time.
Jeff regularly sees clients skip straight to investing — and the ones who pause first consistently end up in a better position.
How do I handle family expectations after a windfall?
Handling family expectations after a windfall means setting boundaries before requests arrive, not after. Clear limits are easier to hold when they're part of a financial plan rather than a reaction to an uncomfortable conversation.
A few approaches that work:
1. Get your own plan settled first: It's much easier to say no when you genuinely don't have the money allocated yet.
2. Create a giving policy: Set an annual giving cap and a 6-12 month pause before any major gifts. "My planner recommends we finalize the plan before making any commitments" is a complete sentence.
3. Stay private where you can: You don't owe anyone the details of what you received.
4. Use a third party as a filter: Your advisor can absorb some of the pressure. "My advisor has restrictions on what we can commit to right now" is not a lie.
5. Build generosity into the plan sustainably: Giving from a structured plan feels very different from giving under pressure.
The goal is protecting your financial security and your relationships at the same time.
How should I invest a windfall for long-term growth?
Investing a windfall for long-term growth starts with defining what the money is for before picking a single investment.
1. Pause and position first: Cover taxes, near-term needs, and a cash buffer before anything goes into the market.
2. Segment by time horizon: Separate the windfall into near-term funds (0-2 years), medium-term goals (2-5 years), and long-term growth (5+ years). Each bucket gets a different investment approach.
3. Build a diversified, goal-based portfolio: Index fundsLow-cost mutual funds or ETFs designed to track the performance of a specific market index, like the S&P 500. By owning the entire market rather than trying to pick winners, index funds offer broad diversification, lower fees, and historically competitive long-term returns., ETFs, and low-cost vehicles matched to your risk tolerance and tax situation.
4. Consider phasing in: If timing the market concerns you, dollar-cost averaging over 6-12 months reduces regret risk.
5. Run tax strategy alongside investing: Asset locationThe strategy of placing different types of investments in the most tax-efficient accounts — for example, putting bonds in a tax-deferred IRA and growth stocks in a taxable brokerage account. Done well, asset location can meaningfully improve your after-tax returns without changing your overall risk profile., Roth conversions, and capital gain management can add significantly to long-term returns.
6. Review annually: Markets and life both change. The portfolio should too.
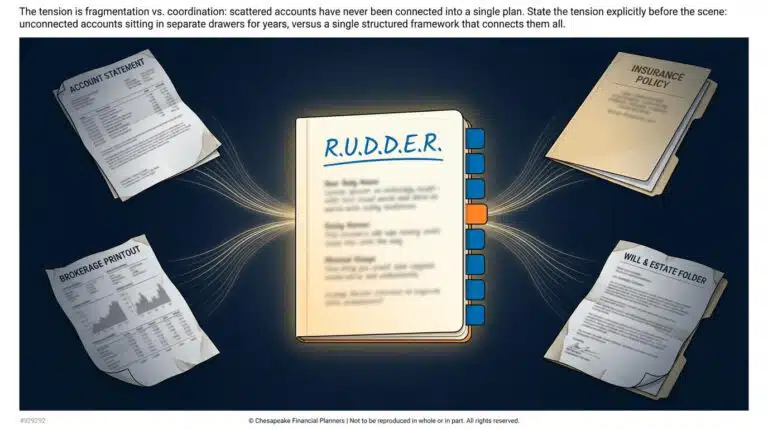
Jeff uses the R.U.D.D.E.R. Method to make sure a windfall investment plan connects to every part of your financial life, not just the account balance.
Should I change my financial plan after an inheritance?
Yes, your financial plan should be updated after an inheritance. Your financial reality has changed, and a plan built on old assumptions will underserve you.
Key areas to revisit:
1. Goals and timeline: Can you retire earlier or reduce your hours? The numbers may now support options they didn't before.
2. Cash flow and reserves: You may be able to pay down debt, build a larger emergency fund, or increase your savings rate.
3. Investment allocation: Reduce concentration, rebalance across accounts, and adjust risk tolerance now that you have more cushion.
4. Estate and legacy plan: Update wills, trusts, and beneficiaries. Consider tax-efficient giving strategies.
5. Tax strategy: New opportunities may exist for Roth conversions, charitable contributions, or capital gain planning.
6. Drift prevention: Windfalls often lead to uncoordinated decisions across accounts. A formal plan review keeps everything coherent.
The goal isn't to overcomplicate the plan. It's to make sure the inheritance is working for you, not sitting idle.
What mistakes do people make after receiving a large sum?
The most common mistake after receiving a large sum is acting before thinking: making purchases, paying off debt, or giving money away to relieve the discomfort of holding a large amount. The urgency feels real but isn't.
Eight mistakes that show up repeatedly:
1. Moving too fast: Decisions made in the first 30-60 days are rarely the best ones.
2. Ignoring the tax impact: Windfall events can trigger capital gains, income tax on inherited IRA distributions, or Medicare premium surcharges (IRMAAIncome-Related Monthly Adjustment Amount — a surcharge added to your Medicare Part B and Part D premiums if your income exceeds certain thresholds. Based on your income from two years prior, IRMAA can add thousands of dollars per year to your Medicare costs, making income management in the years before Medicare enrollment a critical planning opportunity.). Many people don't see these coming.
3. Mixing inherited funds with joint assets: This can convert separate property to marital property in a divorce.
4. Treating it as bonus money: People spend windfalls differently than earned income. It still deserves a plan.
5. Taking advice from the wrong sources: Family, friends, and internet forums are not the same as a fiduciary advisor.
6. Over-giving under pressure: Generosity without a giving strategy quickly becomes unsustainable.
7. Underinvesting or overinvesting: Cash sitting idle for years loses value. Jumping into speculative investments loses capital.
8. Skipping the full-picture update: A windfall changes your retirement plan, estate documents, insurance, and tax situation simultaneously.
Jeff regularly sees these patterns play out. Most of them are preventable with a clear plan from the start.
What taxes apply to my windfall or inheritance?
The taxes that apply to a windfall or inheritance depend on what you received and how. Most inherited cash and assets aren't subject to federal income tax at receipt, but taxes can surface when you sell, withdraw, or earn income from what you've inherited.
Here's what to know by type:
1. Inherited cash or property: No federal income tax on receipt. Capital gains may apply if you sell an appreciated asset, but most inheritances include a step-up in cost basis that reduces or eliminates that gain.
2. Inherited retirement accounts: Distributions are taxed as ordinary income. Non-spouse beneficiaries typically must distribute the account within 10 years under IRS rules.
3. Life insurance proceeds: Generally not taxable. Interest earned on delayed payouts is taxable.
4. Business sale or equity windfall: Capital gains taxes apply. The Net Investment Income Tax may also apply at higher income levels.
5. Gifts received before death: No step-up in basis for you; different gift taxA federal tax on transfers of money or property to another person exceeding the annual exclusion — $19,000 per recipient in 2026. Gifts above this threshold count against your lifetime estate and gift tax exemption, and while most people never actually owe gift tax, tracking large gifts matters for estate planning. rules apply to the giver.
6. Income spikes and surtaxes: A large windfall can push you into higher brackets and increase Medicare premiums temporarily.
A coordinated plan with your advisor and CPA can save tens of thousands and help you avoid irreversible timing mistakes.
Can an inheritance change my retirement timeline?
Yes, an inheritance can meaningfully accelerate your retirement timeline — sometimes by years. Whether it does depends on how the money is integrated into a plan, not just how much you received.
What that planning looks like:
1. Recalculate your retirement income gap: How much do you need monthly, and how much does the inheritance close that gap? Even a moderate amount can make a significant difference.
2. Stress-test different retirement ages: Side-by-side projections — retiring at 62 vs. 67, for example — show exactly what's now possible.
3. Think in income buckets: Inherited funds can serve as a cash buffer, a bridge to delay Social Security for higher lifetime benefits, a healthcare reserve, or a Roth conversionMoving money from a traditional pre-tax IRA to a Roth IRA, paying income taxes now in exchange for tax-free growth and withdrawals in the future. Conversions make the most sense when your current tax rate is lower than what you expect in the future — making the years between retirement and RMD age a prime window for strategic action. fund.
4. Account for taxes and time horizon: Inherited IRAs may increase short-term taxable income. Plan the withdrawals carefully.
5. Realign your investment strategy: You may no longer need the same growth rate. That changes your risk profile.
6. Connect the numbers to what you actually want: Earlier retirement means something specific — travel, time with family, a second career. The plan should reflect that.
Jeff regularly runs these projections with clients who've received an inheritance and didn't realize how close they already were.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
Ready to stop second-guessing and start feeling in control?
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.