QSBS Section 1202 Exclusion Calculator
How Much of Your QSBS Gain Can Be Excluded From Tax?
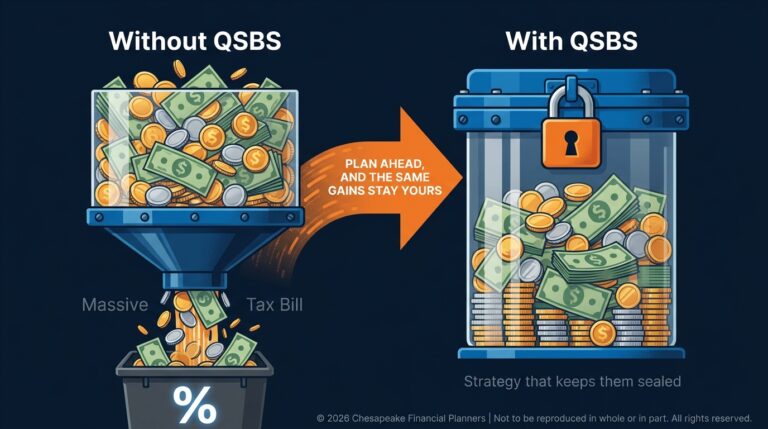
Under Section 1202, up to 100% of the gain on qualified small business stock can be excluded from federal tax, capped per company at the greater of $10 million ($15 million for stock acquired after July 4, 2025) or 10 times basis (26 U.S.C. 1202; Public Law 119-21). This calculator estimates the exclusion and the 2026 tax on the rest.
What Does the QSBS Calculator Estimate?
Qualified small business stock (QSBS) is stock in a qualifying domestic C corporation that you acquired at original issue. Section 1202 of the tax code lets a holder of qualified small business stock exclude part or all of the gain on a sale, up to a per-company cap. The 2025 tax law (Public Law 119-21) created two versions of the rules. Stock acquired on or before July 4, 2025 needs a holding period of more than five years. Stock acquired after that date can exclude 50% of the gain after three years, 75% after four years, and 100% after five years, with a higher cap.
This calculator works out which version applies to each lot you sell, the percent of gain excluded at your sale date, the per-company cap, the excluded gain, and the federal tax on the gain that is left, compared with the tax if the shares did not qualify. It shows when each higher exclusion level would be reached and how your state treats the federal exclusion where that is in the calculator’s verified data. Whether your shares qualify is a legal question for the company’s counsel and your own advisers; the calculator assumes they do and records your checklist answers. It is an educational estimate, not tax or legal advice.
How Is the QSBS Exclusion Calculated?
What it estimates: the version of the rules that applies, the years held, the percent of gain excluded, the per-company cap, the excluded gain, the taxable gain, the federal tax and state and local tax on it, and the federal tax the exclusion removes.
What you enter: Your Shares and the Sale: Sale Date, Number of Lots Sold, and for each lot the Date Acquired, Sale Proceeds and Basis, plus Eligible Gain Already Counted Against the Cap, How You Got the Shares (from the company, as a gift, or at someone’s death), and the Date You Received the Shares for a gift or inheritance. Qualification Checklist (Your Answers): The Company Was a C Corporation, You Acquired the Shares at Original Issue, Company Assets Were Within the Limit, and The Business Is Not in an Excluded Field. Your Tax Picture: How to Figure the Tax (from your income and state, or your own combined rate), Filing Status, your other income as one total or built from income lines, State Where You Live, and Local Income Tax (shown when your state has one: a Maryland county or Baltimore City, a city, county or school district in Alabama, Colorado, Delaware, Indiana, Iowa, Kentucky, Michigan, Missouri, New York, Ohio, Oregon or Pennsylvania, or a rate you enter).
Two modes: Quick estimate mode, the default, asks for Sale Date, the first lot’s Date Acquired, Sale Proceeds and Basis, the four checklist questions, Filing Status, Other Income This Year, and State Where You Live, and holds every other field at the calculator’s default; Detailed mode shows every field, including more lots and the income lines. Both modes run the same calculation.
1. Which rules apply
Stock acquired after July 4, 2025 follows the newer rules (50% at 3 years, 75% at 4, 100% at 5, per Public Law 119-21). Earlier stock follows the older rules: more than 5 years, with 100% for stock acquired after September 27, 2010 and 50% or 75% for stock acquired earlier.
2. Years held
From the acquisition date to the sale date. Shares received as a gift or at death keep the first holder’s acquisition date.
3. The cap
The greater of the dollar limit ($10,000,000 under the older rules, $15,000,000 under the newer rules, per 26 U.S.C. 1202 and Public Law 119-21), reduced by eligible gain from the same company counted in earlier years, or 10 times the basis of the shares sold this year.
4. Excluded gain
The percent excluded times the smaller of your gain and the cap.
5. Tax on the rest
Gain above the cap is taxed as long-term capital gain, stacked on your other 2026 income, with state and local tax. Excluded gain is left out of the Net Investment Income Tax. In a 50% or 75% tier, the gain that is not excluded has its own maximum rate and alternative minimum tax effect, which are not yet in the calculator’s data, so no tax figure is shown for those tiers.
What you see: Excluded Gain at Your Holding Period first, then the rules that apply, years held, percent excluded, the per-company cap, the next higher exclusion level and its date, the taxable gain, federal tax, state and local tax, the federal tax if the shares did not qualify, and the federal tax the exclusion removes, with your qualification checklist and a table of how each state treats the exclusion.
What Assumptions and Sources Does It Use?
- Law: 26 U.S.C. 1202 as amended on July 4, 2025 (Public Law 119-21, section 70431), with 2026 federal tax figures.
- Qualification: assumed. The checklist records your answers about the C corporation, original issue, gross assets ($50,000,000 for stock issued on or before July 4, 2025; $75,000,000 after, per the IRS Instructions for Schedule D) and excluded fields, but cannot confirm them.
- Cap: one per-company cap for the year, shared by every lot sold on the sale date. When lots with different exclusion levels exceed the cap, how the cap is shared is not settled in the statute text, so the excluded gain is not shown.
- State tax: a state’s treatment of the federal exclusion is used only where it is in the calculator’s verified data; other states are shown as Unknown. Where the state tax is shown, it uses the state’s own 2026 brackets for your filing status, plus the local income tax you pick: Maryland’s county and Baltimore City taxes and taxes that follow state income, such as New York City’s, apply to the gain the state taxes; a local tax on earned income only, such as a Pennsylvania or Ohio city’s, does not reach a sale’s gain, so it adds nothing here.
- Not modeled: the alternative minimum taxA parallel tax system designed to ensure high-income earners pay a minimum level of federal tax regardless of deductions. If you have significant income from stock options, depreciation, or certain other tax preferences, you may owe AMT — which is why planning ahead is essential., the separate-return cap, a rollover into new qualified stock (Section 1045), a capital loss in the same year, and whether the company and your shares actually qualify.
Worked Example
The example
This is the calculator’s built-in example (the “Reset to example” values). It describes a hypothetical founder, married filing jointly in Texas, who acquired shares from the company on March 15, 2021 with a $500,000 basis and sells them on November 16, 2026 for $12,000,000. Every figure below is the calculator’s own output for these inputs.
Inputs
| Input | Example value |
|---|---|
| Sale Date | November 16, 2026 |
| Number of Lots Sold | 1 |
| Lot 1 Date Acquired | March 15, 2021 |
| Lot 1 Sale Proceeds | $12,000,000 |
| Lot 1 Basis | $500,000 |
| Eligible Gain Already Counted Against the Cap | $0 |
| How You Got the Shares | From the Company |
| The Company Was a C Corporation | Yes |
| You Acquired the Shares at Original Issue | Yes |
| Company Assets Were Within the Limit | Yes |
| The Business Is Not in an Excluded Field | Not Sure |
| How to Figure the Tax | Estimate It From My Income and State |
| Filing Status | Married Filing Jointly |
| Other Income This Year | $300,000 |
| State Where You Live | Texas |
Results
| Result | Estimate |
|---|---|
| Excluded Gain at Your Holding Period | $10,000,000 |
| Rules That Apply | Older Rules |
| Years Held at Sale | 5 |
| Percent of Gain Excluded | 100% |
| Per-Issuer Cap | $10,000,000 |
| Next Higher Exclusion | None |
| Taxable Gain | $1,500,000 |
| Federal Tax | $339,705 |
| State and Local Tax | $0 |
| Federal Tax If the Shares Did Not Qualify | $2,719,705 |
| Federal Tax the Exclusion Removes | $2,380,000 |
The 100% level was reached on March 16, 2026, the day after the fifth anniversary of the acquisition date. The checklist answer “Not Sure” is shown as “Assumed to qualify; confirm.” The calculator summarizes it this way: “Assuming your shares qualify, $10,000,000 of your $11,500,000 gain is excluded from federal tax under the older rules. That removes about $2,380,000 of federal tax.” Results for your own inputs will differ.
Reviewed by Jeff Judge, CFP®, AEP®, ChFC®, CLU®, Managing Partner, Chesapeake Financial Planners. Last updated November 2, 2026. Tax year 2026.
Frequently Asked Questions
What is qualified small business stock?
Stock in a domestic C corporation acquired at original issue (from the company, not another shareholder), from a company whose gross assets were within the limit when the stock was issued and that is not in an excluded field such as health, law, consulting or financial services. How founders qualify for QSBS covers the tests in more detail. Section 1202 lets a holder exclude some or all of the gain on a sale, up to a cap.
How long do I have to hold QSBS?
Stock acquired on or before July 4, 2025 must be held more than five years. Stock acquired after that date can exclude 50% of the gain after three years, 75% after four years, and 100% after five years.
How much gain can be excluded?
Up to the greater of the dollar cap ($10,000,000 under the older rules, $15,000,000 under the newer rules, less gain from the same company already counted) or 10 times the basis of the shares sold. In the worked example, $10,000,000 of an $11,500,000 gain is excluded, and the $1,500,000 above the cap is taxed as long-term capital gain.
Does my state follow the federal exclusion?
Not every state does. The calculator shows a state’s treatment where it is in its verified data; for example, Pennsylvania does not conform and New Jersey conforms. For states marked Unknown, check with a tax professional before relying on the state figure.
Does the calculator confirm that my shares qualify?
No. The calculator assumes your shares qualify and records your checklist answers about the C corporation, original issue, gross assets and excluded fields. Whether they actually qualify is a legal question for the company’s counsel and your own advisers, and it depends on records the calculator cannot see.
Related planning services: Financial Planning for Tech and SaaS Professionals, Sale of Business, Financial Planning for Business Owners.
Related calculators: Business Sale After-Tax Proceeds Calculator, Tender Offer Decision Simulator and ISO/NSO Exercise and AMT Planner.
See all financial planning calculators
Want to talk through your own numbers with an adviser?
Important disclosures
This calculator is for educational purposes only. It provides a simplified, hypothetical estimate under 26 U.S.C. 1202 as amended in 2025, using 2026 federal figures and the information you enter. It assumes your shares qualify; whether they do is a legal question for the company’s counsel and your own advisers. State rules, the alternative minimum tax, a rollover into new qualified stock, and how the cap is shared among lots can change the actual result. It is not tax, legal, investment, or financial planning advice. Tax laws change, and results are not guaranteed.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor. All investing involves risk including loss of principal. No strategy assures success or protects against loss. There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. DiversificationSpreading investments across multiple asset classes, sectors, and geographies so a loss in one area doesn’t devastate your entire portfolio. It’s the financial equivalent of not putting all your eggs in one basket — and it’s one of the few strategies that can reduce risk without necessarily reducing expected returns. does not protect against market risk.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group and Chesapeake Financial Planners are separate entities from LPL Financial.