

How Can I Reduce Taxes When Earning $200K to $500K?
Last reviewed: July 2026
If you earn between $200,000 and $500,000, you can reduce taxes through tax bracket management: timing income, maxing pre-tax retirement contributions, harvesting investment losses, and bunching deductions to land in lower marginal brackets when possible. At this income level your federal marginal rate runs 32% to 35%, so every dollar you shift out of a high-bracket year keeps real money in your pocket. The work happens during the calendar year, not in April.
Key Takeaways
- Earners between $200K and $500K typically face a 32% to 35% federal marginal rate before state taxes and FICA.
- The 2026 401(k) elective deferral limit is $24,500, with larger catch-ups at ages 50 and 60 to 63.
- A family HSA lets you contribute $8,750 in 2026 with triple tax benefits and long-term investment growth.
- Bunching charitable gifts into one year through a donor-advised fund can push you over the standard deduction.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate high-income tax planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same pattern every spring: high earners who think they have no tax levers left actually have five or six they never pulled.
What Is Tax Bracket Management for High Earners?
Tax bracket management is the practice of timing and positioning your income so that fewer dollars get taxed at your highest marginal rate. For someone earning $200K to $500K, it refers to deliberately shifting income, deductions, and gains across tax years to stay out of the most expensive brackets when you can.
You are stuck in what Jeff calls the squeeze zone. You earn too much to qualify for many middle-income tax breaks, but you are not wealthy enough to access the planning structures the ultra-rich use. According to the IRS, the 32% bracket and 35% bracket cover most of this income range for 2026, and that is before you layer on state income tax, FICA, and the 3.8% Net Investment Income Tax on investment income above the threshold.
The point is not to dodge taxes. It is to stop overpaying because no one mapped out the year in advance. High income tax planning rewards the people who plan in June, not the ones who scramble in April.
How Do Retirement Contributions Lower My Tax Bill?
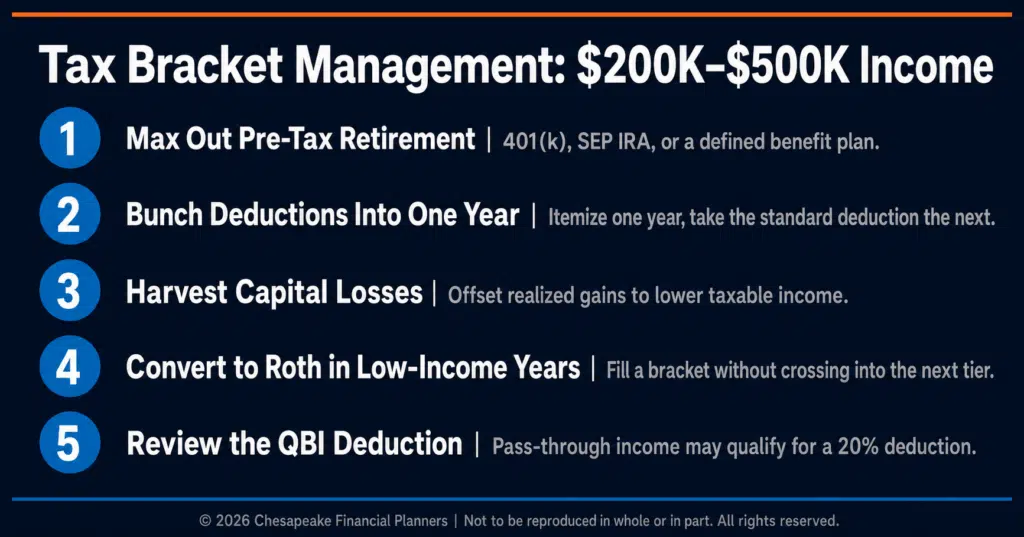
Pre-tax retirement contributions are your first and biggest lever. Every dollar you defer into a traditional 401(k) comes straight off your taxable income, which at a 35% marginal rate means roughly 35 cents of tax savings per dollar.
For 2026, the IRS set the 401(k) elective deferral limit at $24,500, rising to $32,500 if you are 50 or older. Under SECURE 2.0, workers ages 60 to 63 get an enhanced catch-up that lifts the limit to $35,750. If you and a spouse both have workplace plans, that is potentially $49,000 to over $65,000 in deductible contributions in a single year.
Some employers offer after-tax 401(k) contributions paired with in-plan Roth conversions, often called a mega backdoor Roth. That lets you push total contributions toward the $72,000 overall limit and convert the after-tax portion to Roth for tax-free growth. If you have self-employment income, a Solo 401(k) or SEP IRA opens up even higher contribution room based on business profit. These are core tax strategies for high earners that most people leave on the table.
What Tax-Advantaged Accounts Should High Earners Use?
Beyond your 401(k), the Health Savings Account is the most underused tool for high earners. If you have a high-deductible health plan, an HSA gives you a triple tax advantage: deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical costs.
For 2026, you can contribute $4,400 as an individual or $8,750 for a family, plus an extra $1,000 if you are 55 or older. Here is the move most people miss. Do not use the HSA like a checking account. Pay current medical bills out of pocket, invest the HSA for decades, and reimburse yourself tax-free later. Jeff has watched clients turn a few years of HSA contributions into a six-figure, tax-free medical reserve simply by leaving it invested.
This is where a named process helps. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The Uncover step is where these overlooked accounts usually surface.
How Does Tax-Loss Harvesting Reduce Taxes?
Tax-loss harvesting reduces your taxes by selling investments at a loss to offset realized capital gains, and up to $3,000 of ordinary income each year. If you had a strong market year, sold real estate, or received stock compensation, harvested losses can take a real bite out of your taxable income.
The rule you cannot break is the wash-sale rule. The IRS disallows the loss if you buy the same or a substantially identical security within 30 days before or after the sale. You can stay invested by buying a similar but not identical fund, so you keep your market exposure while banking the loss. This is one of the cleaner reduce taxes $300k income moves because it works inside accounts you already hold.
Done consistently across a portfolio, harvested losses also carry forward indefinitely, building a reserve you can deploy against future gains. That matters when you eventually sell concentrated stock or a business.
How Can Bunching Deductions and Roth Conversions Help?
Bunching deductions means concentrating two years of deductible expenses into a single year so you clear the standard deduction, then taking the standard deduction the next year. With the 2026 standard deduction at $32,200 for married couples filing jointly per the IRS, most high earners no longer itemize every year.
A donor-advised fund makes this clean. If you normally give $15,000 a year to charity, contribute $30,000 to a DAF in one year for the full deduction, then grant it out to charities over time. You captured tax deductions high earners often miss without changing how much your favorite causes actually receive.
Roth conversions work the same logic in reverse. In a lower-income year, maybe between jobs, on parental leave, or launching a business, convert traditional IRA dollars to Roth and pay tax at your temporarily lower rate. As Jeff often tells clients, the best conversion year is the one your income forgot to show up for. Tax-free growth and withdrawals follow, which is valuable if you expect higher brackets later.
For a deeper sequencing playbook, see How do you use the years between retirement and RMDs to reduce lifetime taxes? and What is a year-round tax planning calendar for retirees and pre-retirees?.
Frequently Asked Questions
What tax bracket am I in if I make $300,000?
A single filer earning $300,000 in 2026 falls into the 35% federal marginal bracket, while married couples filing jointly at that income typically sit in the 24% to 32% range. Your marginal rate applies only to the top slice of income, not your whole salary, which is why What Is the Difference Between Marginal and Effective Tax Rate? matters so much.
How much can high earners save with 401(k) contributions?
A high earner in the 35% bracket who defers the full 2026 limit of $24,500 saves roughly $8,575 in federal tax in that year alone. Married couples who both max out can shelter $49,000 or more, producing five figures of annual tax savings before any state tax benefit is counted.
Can I do a Roth IRA if I earn over $200,000?
Direct Roth IRA contributions phase out at high incomes, but a backdoor Roth lets high earners contribute indirectly by funding a nondeductible traditional IRA and converting it. The strategy works cleanly only if you have no other pre-tax IRA balances, so coordinate it with any 401(k) rollover plans first.
Does tax-loss harvesting actually help high earners?
Yes, tax-loss harvesting helps high earners by offsetting capital gains dollar for dollar and reducing up to $3,000 of ordinary income annually. Unused losses carry forward indefinitely, building a reserve against future gains from stock compensation, real estate, or a business sale. Just respect the 30-day wash-sale window.
Should I worry about the Net Investment Income Tax?
Yes, if your modified adjusted gross income clears the threshold, the Net Investment Income Tax adds 3.8% on top of your regular rate for interest, dividends, and capital gains. For earners in the $200K to $500K band, this surtax quietly raises the cost of investment income and rewards tax-efficient account placement.
When should I bring in a financial advisor for tax planning?
Bring in an advisor when you have multiple income sources, equity compensation, or a year with unusual events like a bonus, business sale, or job change. Modeling these scenarios before year-end is where planning pays for itself, since most high-income tax moves expire on December 31.
Keeping More of What You Earn
Strategic tax bracket management is the difference between funding a small government program by accident and building wealth on purpose. The strategies that fit you depend on your income mix, your equity compensation, and your timeline, and most of them have a year-end deadline you cannot get back.
If this was useful, our free high-earner tax planning guide walks through these tax strategies for high earners in detail, with a year-end checklist you can act on. Download it at chesapeakefp.com. And if you want a second set of eyes, How can I potentially optimize my taxes as my income grows? is a good next read.
Want to go deeper? Our Tax Moves for High Earners walks through this step by step.
Prefer a different starting point? Our Tax Strategy Readiness Quiz is worth a look.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


