Last reviewed: October 2026
Wealthy retirees rarely win on investment picks. What separates them is a set of habits: they saved on autopilot, converted to Roth in low-income years, kept years of spending in reserve, delayed Social Security, split essential from discretionary spending, managed their tax bracket every year, rebalanced on a schedule, and kept their estate plan current. Most of those habits work at any account balance.
Key Takeaways
- Wealthy retirees treat savings as a fixed bill, often deferring the full 2026 401(k) limit of $24,500 plus catch-up contributions.
- Each year you delay Social Security past full retirement age adds 8% to your benefit, up to age 70.
- The years between retirement and RMDs at age 73 are often the cheapest window for Roth conversions.
- Maryland retirees 65 and older can exclude up to $40,600 of qualifying pension income in 2026, which shapes how withdrawals are sequenced.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement income and tax planning since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The retirees I see with the most confidence aren't the ones with the biggest accounts," Jeff says. "They're the ones who stopped making the same money decisions from scratch every year."
What Do Wealthy Retirees Do Differently Before They Retire?
They treat saving as a bill, not a choice. The wealthy retirees I work with didn't build their accounts by finding a better fund. They built them by deciding, decades earlier, that the retirement contribution came out first and the lifestyle adjusted around it.
That shows up in a few repeatable moves:
- They automate contributions. Money that never hits checking never gets spent.
- They raise the rate with every raise. A 1% or 2% bump at review time barely registers in take-home pay.
- They use catch-up room after 50. In 2026 that's an extra $8,000 in a 401(k), and workers aged 60 to 63 can add $11,250 instead.
- They don't stop during downturns. Pausing contributions in a bad market means buying less when prices are lower.
Compounding does the heavy lifting from there, but only if the money keeps going in. Jeff Judge has watched plenty of high earners out-earn their neighbors and still arrive at 60 with less, simply because their savings rate moved with their mood instead of with a rule.
Is it too late to adopt these habits at 55? No. The catch-up rules exist precisely for late starters, and the ten years before retirement are often the highest-earning years of a career. Starting the automation now still captures a decade of contributions and growth.
Why Do Wealthy Retirees Convert to Roth in Their 60s?
Because the years right after work stops can be the lowest-tax years of the rest of their lives. Paychecks are gone, Social Security may not have started, and required minimum distributions don't begin until age 73. That gap is when converting pre-tax IRA money to a Roth IRA can be done in a lower bracket than the one RMDs and Social Security might push them into later.
The payoff stacks up in three ways. Roth IRAs have no required distributions during the owner's lifetime. Qualified Roth withdrawals don't add to the income Medicare uses for IRMAA surcharges, which start at $109,000 of modified adjusted gross income for a single filer in 2026, per CMS. And Roth assets generally pass to heirs without the income tax bill an inherited traditional IRA carries.
It isn't automatic. A conversion is a tax bill you choose to pay now, so it only makes sense when today's rate is lower than the rate you expect later. Our guide to Roth conversions in the pre-RMD gap years walks through how to size each year's conversion.
How Many Years of Spending Do Wealthy Retirees Keep in Reserve?
Usually two to four years of planned withdrawals, held outside the stock market in vehicles such as high-yield savings, money market funds, short-term CDs, or Treasury bills. The reserve isn't there to earn much. It's there so they never have to sell stocks in a downturn to pay the bills.
That matters because of sequence-of-returns risk: a market drop early in retirement, while withdrawals are underway, can do lasting damage that the same drop ten years later wouldn't. A reserve buys time for markets to recover before stocks have to be sold. Our retirement income drawdown strategy guide shows where a reserve fits in the withdrawal order.
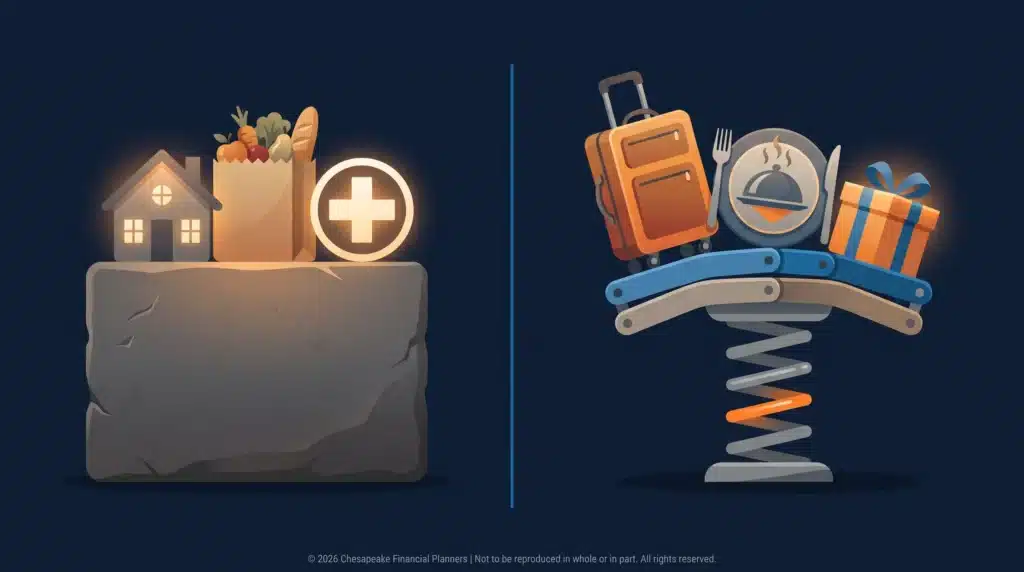
The same group pairs the reserve with a clear split between two kinds of spending:
| Spending type | Examples | Typical funding source | Flexibility in a downturn |
|---|---|---|---|
| Essential | Housing, food, insurance, healthcare | Social Security, pension, bond income | Low |
| Discretionary | Travel, dining, gifts, hobbies | Portfolio withdrawals and reserves | High: can often be trimmed 30% to 50% for a year or two |
When essentials are covered by income that doesn't depend on the market, a bad year means a shorter trip, not a forced sale. That isn't deprivation. It's having options when markets turn.
When Do Wealthy Retirees Claim Social Security?
Many wait until 70. For anyone born in 1960 or later, full retirement age is 67, and every year of delay after that adds 8% to the monthly benefit, for a total of 24% at age 70. The increase is inflation-adjusted and lasts for life, which is hard to match anywhere else.
Delaying only works if something else covers the bridge years. Wealthy retirees typically fund that stretch from taxable accounts, from earmarked reserves, and sometimes from IRA withdrawals that double as low-bracket income. For married couples, a common pattern is for the higher earner to delay to 70 while the other spouse claims earlier, because the larger benefit becomes the survivor benefit when the first spouse dies.
Jeff Judge's view is practical: "Claiming at 70 isn't a rule. It's a bet on longevity, and for a healthy spouse in a married couple it's often the one bet that pays out even after you're gone."
How Do Wealthy Retirees Manage Taxes, Healthcare, and Rebalancing Each Year?
They plan the tax return before the year ends instead of reacting to it in April. In practice that means filling a low bracket with a Roth conversion, harvesting gains at the 0% capital gains rate when income allows, staying under IRMAA thresholds, bunching deductions into alternating years, and, after 70½, giving through qualified charitable distributions of up to $111,000 in 2026. Each move is small. Repeated for 25 years, they add up.
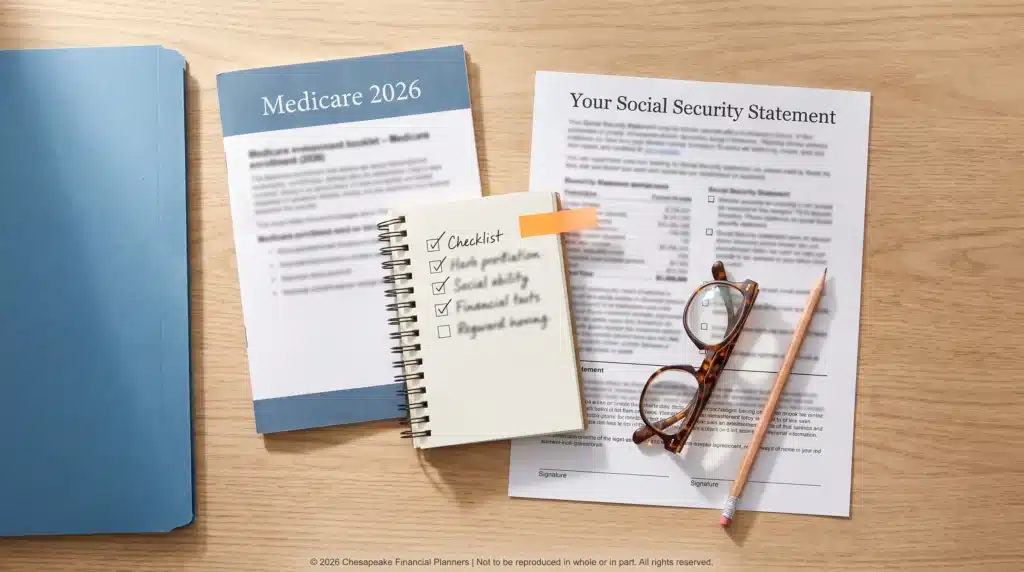
Healthcare gets the same seriousness. Medicare enrollment, the choice between Medigap and Medicare Advantage, and Part D plan selection are planning decisions, not paperwork. Many of the wealthier retirees we see choose Medigap for lower out-of-pocket risk and wider provider access, though the right answer depends on health, budget, and where you live. They also think about long-term care well before 65, when coverage is easier to qualify for.
Rebalancing runs on rules rather than headlines. A common trigger is any asset class drifting five percentage points or more from its target. The rule forces trimming what ran up and adding to what fell, and it keeps panic out of the process.
Do you need an advisor to do all this? Not necessarily, but coordination is the hard part. The wealthier retirees we meet tend to work with a fiduciary advisor whose compensation they understand, and they value the coordination across taxes, Social Security, healthcare, and withdrawals more than investment selection.
Why Do These Habits Matter More for Maryland Retirees?
Maryland adds a state layer that national articles skip. The state taxes traditional IRA and 401(k) withdrawals, while qualifying retirees 65 and older can exclude up to $40,600 of eligible pension income in 2026. That exclusion is reduced by Social Security benefits received, which makes the order of withdrawals a real planning decision. Our breakdown of the Maryland pension exclusion for Harford County retirees shows how it interacts with Social Security.
Estate planning carries a Maryland twist too. The state's $5 million estate tax exemption sits far below the federal $15 million exemption for 2026, so a paid-off home in Bel Air, retirement accounts, and life insurance can approach the state threshold faster than families expect. Wealthy retirees review their estate documents every three to five years and after major life events, and they keep beneficiary designations current, because those designations override what a will says.
For retirees in Forest Hill, Bel Air, Fallston, and across Harford County and northern Baltimore County, we coordinate all of this in one process. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Reassess and Refine is where the annual tax, rebalancing, and estate habits live, so they happen on a calendar instead of when someone remembers.
Frequently Asked Questions
What do wealthy retirees do differently with their money?
Wealthy retirees rely on habits more than investment skill. They automated saving while working, converted to Roth in low-income years, held two to four years of spending in reserve, delayed Social Security, split essential from discretionary spending, managed their tax bracket annually, rebalanced by rule, and kept estate documents current.
How much cash should a retiree keep in reserve?
Many retirees keep two to four years of planned portfolio withdrawals outside the stock market, in high-yield savings, money market funds, short-term CDs, or Treasury bills. The right number depends on how much of your essential spending Social Security and pensions already cover and how much market volatility you can tolerate.
Is it worth delaying Social Security to age 70?
Delaying Social Security to 70 raises the monthly benefit by 8% for each year past full retirement age, or 24% for someone with a full retirement age of 67. It tends to make sense for healthy retirees with other assets to bridge the gap, and for the higher earner in a married couple.
When is the best time to do Roth conversions?
Roth conversions are often most attractive in the years after retirement and before RMDs begin at 73, when taxable income is lower. Converting in those years can mean paying tax at a lower rate than RMDs and Social Security might trigger later, but each year's amount should be sized against brackets and IRMAA thresholds.
Does Maryland tax retirement income?
Maryland taxes traditional IRA and 401(k) withdrawals, but residents 65 and older can exclude up to $40,600 of qualifying pension income in 2026, reduced by Social Security benefits received. Maryland also has a $5 million estate tax exemption, so Harford County retirees should plan state taxes alongside federal ones.
Can these habits work with a smaller nest egg?
Yes. Most of these habits scale to any balance: automating savings, keeping a reserve proportional to your spending, delaying Social Security when health allows, filling low tax brackets, and rebalancing on a schedule. Jeff Judge often notes that retirees with modest accounts gain the most because they have the least room for an expensive mistake.
Ready to Build These Habits Into Your Plan?
Wealthy retirees win on discipline, and those habits are available to you whether your account is large or still growing. Ready to put a plan around yours? Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call.
A version of this article originally appeared in Kiplinger.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
Traditional IRA account owners have considerations to make before performing a Roth IRA conversion. These primarily include income tax consequences on the converted amount in the year of conversion, withdrawal limitations from a Roth IRA, and income limitations for future contributions to a Roth IRA. In addition, if you are required to take a required minimum distribution (RMD) in the year you convert, you must do so before converting to a Roth IRA.
Stock investing includes risks, including fluctuating prices and loss of principal.
CDs are FDIC insured to specific limits and offer a fixed rate of return if held to maturity, whereas investing in securities is subject to market risk including loss of principal.
Government bonds and Treasury bills are guaranteed by the US government as to the timely payment of principal and interest and, if held to maturity, offer a fixed rate of return and fixed principal value.
Rebalancing a portfolio may cause investors to incur tax liabilities and/or transaction costs and does not assure a profit or protect against a loss.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


