
How Do Confident Retirees Spend Without Financial Stress?
Last reviewed: July 2026
Confident retirees spend without financial stress because retirement spending confidence comes from a handful of repeatable habits, not from a bigger balance. The calmest retirees I work with are rarely the wealthiest ones. They are the people who decided, in advance, how much to spend, where the money comes from, and what they will do when markets fall. Make those decisions before emotion shows up, and spending stops feeling like a guess.
Key Takeaways
- Retirement spending confidence is built on planning behaviors, not portfolio size; calm retirees set the rules before markets force a reaction.
- The 4% rule starts you near $40,000 of first-year spending on a $1 million portfolio, then adjusts for inflation each year.
- Fidelity estimates a single 65-year-old needs about $172,500 after tax for retirement health care as of 2026, not counting long-term care.
- Maryland taxes traditional withdrawals but offers a $40,600 pension exclusion for residents 65+, which shapes a Maryland retiree's withdrawal order.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has helped families and business owners across Harford County and the Baltimore metro area build retirement income plans they can actually live on since earning his CFP® certification in 2013, using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The calmest retirees I know are not the ones with the most money," Jeff says. "They are the ones who stopped guessing and put their spending on paper."
What Actually Separates Calm Retirees From Anxious Ones?
The difference is rarely the size of the account. Financial anxiety does not always end at retirement. For a lot of people it gets louder, because the paycheck stops and every withdrawal can feel permanent. What separates calmer retirees from constantly worried ones is how they manage decisions, expectations, and tradeoffs, not how much they saved. Feelings of security track planning behaviors far more closely than they track portfolio size.
A big part of that is refusing to treat an account balance like a scoreboard. When your net worth becomes your report card, a down market feels personal, and personal decisions get emotional. Confident retirees define what "enough" looks like in plain terms: an income plan that funds their life with an acceptable margin of safety. Once that number is clear, the daily market noise carries less weight. The question shifts from "Did we beat the market this quarter?" to "Is our plan still on track to fund the life we want?"
Jeff Judge has noticed the same pattern across hundreds of retirement conversations: the people who focus on income durability, rather than portfolio highs, are the ones who spend freely on the things they value. They also review their plan on a schedule, quarterly or twice a year, instead of watching it daily. Constant monitoring breeds reactivity. The goal is not less awareness, it is less flinching.
How Should You Organize Savings for Retirement Spending Confidence?
Organize the money by when you will spend it, not as one undivided pile. This is the time-bucket idea, and it is the backbone of a calm retirement spending strategy. You split assets into near-, middle-, and long-term buckets so a bad year in stocks does not land on next month's grocery money.
| Time horizon | When you'll spend it | What tends to hold it |
|---|---|---|
| Near term | Years 1 to 3 | Cash alternatives: high-yield savings, money market funds, short-term CDs |
| Middle term | Years 4 to 10 | High-quality short and intermediate bonds, balanced strategies |
| Long term | 10-plus years | Diversified stock exposure for growth |
The practical benefit is obvious: if markets drop, the dollars you need soon are not forced to sell at a loss. The behavioral benefit is bigger. When your next couple of years are already set aside, you are far less tempted to sell long-term investments at the worst possible time. Our bucket strategy for retirement income walks through how to size each layer.
What if the market dropped 20% next year? Ask how much of your next 24 months of spending is already sitting in cash alternatives and short-term holdings. If the honest answer is "most of it," a 20% drop is a headline, not an emergency, because you are not selling stocks to pay for dinner. That single question is the fastest way to test whether your retirement spending confidence rests on structure or on hope.

What Withdrawal Strategy Keeps Spending Steady?
A repeatable withdrawal framework is what keeps spending calm year to year. Stressed retirees withdraw reactively, guessing at a number each time they need cash. Confident ones pick a rule and stick with it. The most common starting point is the safe withdrawal rate known as the 4% rule: take about 4% of the portfolio in year one, then adjust the dollar amount for inflation. On a $1 million portfolio, that is roughly $40,000 in the first year. Each following year you give yourself a raise tied to inflation, such as the 2.8% Social Security cost-of-living adjustment for 2026.
Morningstar's researchers reviewed the math again and still landed near 4% as a reasonable starting point for a 30-year retirement, while stressing that it is a starting point, not a straitjacket.
Does the exact withdrawal method matter? Not nearly as much as having one. A fixed percentage, a guardrails approach that flexes your spending up or down with markets, or a schedule built around required minimum distributions can all work. What calms people is knowing the rule before the market hands them a reason to panic. If you want the mechanics, our guide to the safest way to withdraw from retirement accounts compares the main approaches.
This is where Chesapeake's signature process earns its keep. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A withdrawal rule set inside that process is a decision you make once, calmly, instead of forty separate decisions made under pressure.
Where Should Confident Retirees Spend, and Where Should They Cut?
They spend deliberately on what genuinely improves life and quietly cut what does not. Confident retirees do not slash every expense. They fund travel that keeps them close to people they love, hobbies they actually use, and health and wellness spending that keeps them independent. Then they remove the drift: subscription creep, memberships nobody uses, and a house that got too big to justify. A simple annual "spending values" review does the job. Keep the top three categories that improve your life and challenge one recurring expense that has quietly gone on autopilot.
Flexibility is the other half. Rigid plans break when life changes, so build in room to bend. That can mean keeping the option to earn some income through consulting, part-time, or seasonal work. It can mean separating spending into needs and wants, so discretionary categories can flex in a weak market. And it can mean holding a liquidity backstop, such as an unused home equity line of credit, so you are not forced to sell investments during a decline. Timing counts too: delaying a large discretionary purchase in a down year manages risk without feeling like deprivation.
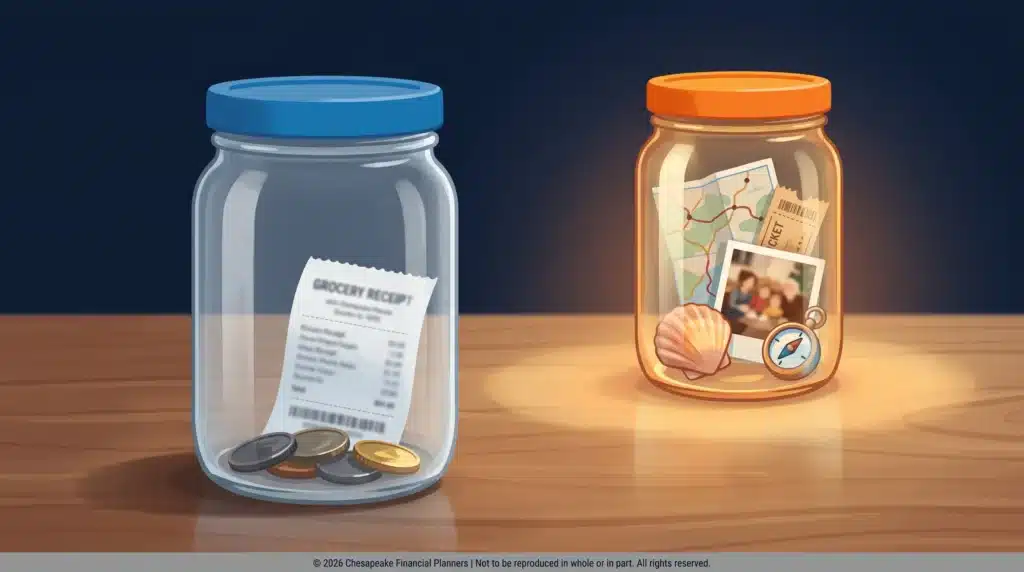
Jeff Judge uses a plain framework with clients here: separate the money that buys your groceries from the money that buys your memories. The grocery money should be boring and close at hand. The memory money can take more risk, because you have the flexibility to spend it later if this year looks rough.
How Do Health Care Costs and Maryland Taxes Fit the Plan?
Health care is the retirement cost most people underestimate, so put a real number on it. Fidelity's annual estimate puts retirement health care for a single 65-year-old at about $172,500 after tax as of 2026, and that figure does not include long-term care. A written estimate plus a funding approach is far calmer than avoiding the topic. Confident retirees learn the basics of Medicare Parts A, B, and D, compare supplemental coverage using our Medigap versus Medicare Advantage breakdown, and budget for premiums and out-of-pocket costs.
| 2026 figure | Amount |
|---|---|
| Fidelity health care estimate, single 65-year-old | about $172,500 after tax |
| Standard Medicare Part B premium, monthly | $202.90 |
| Maryland pension exclusion, age 65+ | up to $40,600 |
For our Harford County clients, state taxes add a layer that shapes the whole withdrawal order. Maryland taxes traditional retirement withdrawals but does not tax qualified Roth distributions, and it offers a pension exclusion of up to $40,600 for residents 65 and older. That exclusion phases down dollar for dollar against Social Security, so the order you pull from accounts genuinely changes your tax bill. Our note on what the $40,600 pension exclusion really means covers the details.
This matters in a specific way around Forest Hill, Bel Air, and the rest of Harford County. Many of our neighbors are federal and military retirees connected to Aberdeen Proving Ground, juggling a FERS pension, the Thrift Savings Plan, and Social Security. Coordinating those three income sources, alongside the Maryland pension exclusion, is exactly the kind of layered decision a Maryland retiree should map out before the first withdrawal, not after.
Frequently Asked Questions
What is retirement spending confidence?
Retirement spending confidence is the calm that comes from knowing your spending rules before markets test them. It is built on planning behaviors, deciding how much to withdraw, where the money comes from, and how you will respond to a downturn, rather than on the raw size of your portfolio. Structure creates the confidence, not the balance.
How much can I safely spend from my portfolio each year?
The 4% rule is the common starting point: withdraw about 4% of your portfolio in year one, then adjust for inflation annually. On $1 million, that is roughly $40,000 the first year. Treat it as a starting estimate, not a fixed law, and revisit the rate yearly as markets and your spending change.
How much should I budget for health care in retirement?
Fidelity estimates a single 65-year-old will need about $172,500 after tax for retirement health care as of 2026, and that number excludes long-term care. Budget for Medicare premiums, the standard Part B premium of $202.90 per month in 2026, out-of-pocket costs, and supplemental coverage. Writing down a real estimate beats hoping the cost stays small.
Does Maryland tax my retirement income?
Maryland taxes traditional retirement withdrawals and Social Security is exempt at the state level, but qualified Roth distributions are not taxed by Maryland. Residents 65 and older can claim a pension exclusion of up to $40,600 in 2026, which phases down against Social Security benefits. This makes your withdrawal order a real planning lever for Harford County retirees.
How often should I review my retirement spending plan?
Review your plan on a set schedule, quarterly or twice a year, and rebalance only when your allocation drifts meaningfully. Update the plan after major life changes such as a health event, a move, or the loss of a spouse. Daily monitoring tends to create anxiety and tempt emotional decisions, so consistency beats constant watching.
Should I keep working part-time in retirement?
Keeping the option to earn some income adds flexibility, which is one of the strongest buffers against retirement spending stress. Consulting, part-time, or seasonal work lets you lean on earnings during a weak market instead of selling investments. Even the ability to work, whether or not you use it, gives your plan room to bend without breaking.
Ready to Spend With Confidence Instead of Guesswork?
Retirement spending confidence is a plan you can point to, not a feeling you hope shows up. If you are weighing how much to spend, where to pull it from, and how to handle health care and Maryland taxes, that is exactly the work we do every week. Jeff Judge and the Chesapeake team serve families, federal retirees, and business owners across Harford County and the Baltimore metro. Schedule a free fit call and put real rules around your retirement income plan.
A version of this article originally appeared in Kiplinger.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Stock investing includes risks, including fluctuating prices and loss of principal.
Bonds are subject to credit, market, and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.
Certificates of Deposit are FDIC insured and offer a fixed rate of return if held to maturity. Brokered CDs sold prior to maturity in the secondary market may result in loss of principal due to fluctuations in the interest rate or lack of liquidity. Brokered CDs are registered with the Depository Trust Corp. (DTC). Brokered CDs with step-down and/or call provisions may be less favorable than traditional CDs without these features.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


