
Published: | Last reviewed:
There is no single best TSP withdrawal strategy, because the right approach depends on your tax situation, income needs, and goals, but the key decisions are how to handle Roth versus traditional balances, which withdrawal method to use, and whether keeping money in the TSP or rolling it elsewhere serves you better. The Thrift Savings Plan offers flexible options: installment payments, partial or full withdrawals, and a life annuity. Understanding how each works, and how your Roth and traditional balances are taxed, lets you build a plan that fits your retirement rather than forcing your retirement to fit a default.
On This Page
- Key Takeaways
- How are Roth TSP and Traditional TSP taxed in retirement?
- What are your TSP withdrawal options?
- Should you keep money in the TSP or roll it over?
- How do you build your TSP withdrawal plan?
- Related Topics Worth Reading
- Frequently Asked Questions
- Making your TSP work for your retirement
- Disclosures
Key Takeaways
- The TSP offers three withdrawal types: installment payments, single (partial or total) withdrawals, and a life annuity.
- Traditional TSP withdrawals are taxed as ordinary income; qualified Roth TSP withdrawals come out tax-free.
- Required minimum distributions from the TSP begin at age 73 under current law.
- Keeping money in the TSP and rolling it to an IRA both have real advantages and trade-offs; the right choice is individual and worth careful, unbiased analysis.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has worked with federal employees and military families across Harford County, near Aberdeen Proving Ground, since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: the TSP is one of the best-built retirement plans in the country, so the withdrawal decision deserves to be made on the facts of your situation, not on a rule of thumb or anyone's sales pitch.
About Jeff Judge, CFP®: meet Jeff and the Chesapeake Financial Planners team.
How are Roth TSP and Traditional TSP taxed in retirement?
Roth TSP and Traditional TSP are taxed very differently in retirement: traditional balances are taxed as ordinary income when withdrawn, while qualified Roth balances come out completely tax-free. Knowing which is which is the foundation of any withdrawal plan, because it determines the tax cost of every dollar you take.
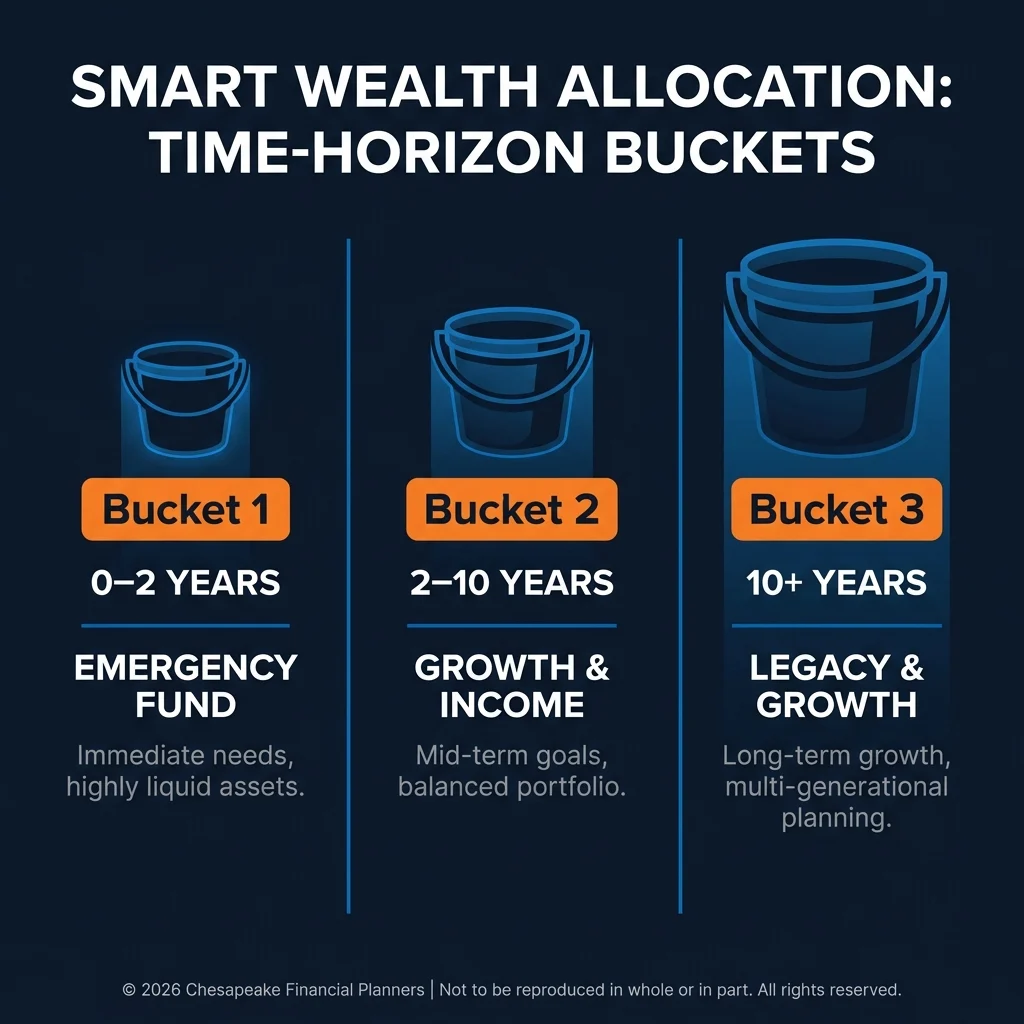
Your Traditional TSP holds pre-tax contributions and their growth, so withdrawals are fully taxable as ordinary income, just like a paycheck. Your Roth TSP holds after-tax contributions, and as long as the withdrawal is qualified, generally meaning you are at least 59½ and the account has been open five years, both your contributions and their earnings come out tax-free. Many federal employees have both types within their TSP, which is actually an advantage: it gives you two tax "buckets" to draw from.
That mix is the heart of smart withdrawal planning in any retirement income plan. In a year when you want to keep taxable income low, perhaps to limit how much of your Social Security is taxed or to stay under the 2026 IRMAA threshold of $109,000 for a single filer or $218,000 for a couple, you can lean on Roth withdrawals. In a lower-income year, drawing from the traditional balance at a low tax rate may make sense. As Jeff Judge puts it, "Federal employees who built a Roth TSP balance gave themselves a valuable lever, and the whole game in retirement is pulling that lever deliberately instead of withdrawing blindly from one bucket."
What are your TSP withdrawal options?
Your TSP withdrawal options fall into three categories that you can combine, and each suits a different need. The TSP allows installment payments, single withdrawals, and a life annuity purchase once you have separated from federal service.
Installment payments send you a set amount on a schedule (monthly, quarterly, or annually), either a fixed dollar amount you choose or an amount based on your life expectancy, and you can change or stop them. Single withdrawals let you take a partial amount when you need it or your entire balance at once, useful for a specific expense or to move funds. A life annuity uses some or all of your balance to buy a guaranteed stream of income for life through the TSP's annuity provider, trading the lump sum for certainty. As the TSP puts it, "You give up your money and control of it in exchange for guaranteed lifetime monthly payments."
These are not mutually exclusive. A common approach is to use installments for steady monthly income while keeping the rest invested, taking occasional partial withdrawals for one-time needs. One important detail: the TSP withdraws proportionally from your Roth and traditional balances unless the rules allow otherwise, so coordinating withdrawals with your tax plan matters. The right combination depends on how much guaranteed income you want, how much flexibility you need, and how you want to manage taxes year to year.
Should you keep money in the TSP or roll it over?
Whether to keep money in the TSP or roll it into an IRA is a genuinely individual decision with real advantages on both sides, and it deserves careful, unbiased analysis rather than a default answer. This is one of the most consequential choices a retiring federal employee makes, so it is worth understanding the trade-offs clearly.
Reasons many federal employees keep money in the TSP include its very low administrative costs, which are among the lowest of any retirement plan and can meaningfully affect long-term returns, its simplicity, the unique G Fund, and strong creditor protections. Reasons some people consider rolling to an IRA include access to a wider range of investment choices, the ability to consolidate multiple accounts in one place, and certain withdrawal or estate-planning flexibilities an IRA can offer. Both lists are legitimate; neither is universally right.
Because a rollover moves money out of a low-cost plan and the decision is hard to reverse, approach it with eyes open. Compare the actual costs, investment options, and features of each side for your specific situation, and be cautious of any recommendation to roll over that does not clearly show why it benefits you. The TSP's own withdrawal resources and a fiduciary who is required to act in your interest can help you weigh it objectively. The goal is a decision based on your facts, not on inertia or on anyone's incentive to move your money.
How do you build your TSP withdrawal plan?
You build your TSP withdrawal plan by clarifying your income needs, coordinating Roth and traditional withdrawals for tax efficiency, choosing your withdrawal methods, and planning around required distributions. It is a sequence of deliberate decisions best made before you start withdrawing.
Work through these steps:
- Project your retirement income needs and identify what the TSP must provide alongside your FERS pension and Social Security.
- Decide how much guaranteed income you want, which informs whether installments, an annuity, or a mix fits best.
- Coordinate Roth and traditional withdrawals year by year to manage your taxable income, Social Security taxation, and Medicare premiums.
- Plan for required minimum distributions, which begin at age 73 and apply to your traditional TSP balance.
- Make the keep-versus-roll decision on the merits for your situation, ideally with a fiduciary's unbiased input.
This methodical approach is exactly what the R.U.D.D.E.R. Method™ is built for. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and a TSP withdrawal plan runs from Design and Develop, where the strategy is built, through Reassess and Refine, where it is adjusted each year as taxes and needs change.
Related Topics Worth Reading
Your TSP is one piece of your federal retirement. These related topics go deeper on the rest.
- The complete guide to federal employee retirement benefits. How do I coordinate my FERS pension, TSP, and Social Security for the best retirement outcome?
- How to coordinate every income source to minimize taxes. How do I coordinate all my retirement income sources to minimize taxes and maximize income?
- The general best order to withdraw across all your accounts. What is the best order to withdraw from my 401k, Roth IRA, and taxable accounts in retirement?
- How your retirement income affects your Medicare premiums. How does my Social Security claiming decision affect my Medicare premiums?
- Federal employees near Aberdeen Proving Ground: local planning considerations. How should Aberdeen Proving Ground federal employees manage their FERS, TSP, and benefits?
This guide is part of our Federal & Military Benefits library.
Related reading in this guide:
Related service: a retirement readiness assessment
Related calculators: FERS Pension and TSP Calculator, Military Retirement and BRS Calculator
Frequently Asked Questions
What are the withdrawal options for the TSP?
The TSP offers three withdrawal options after you separate from federal service: installment payments on a monthly, quarterly, or annual schedule; single withdrawals of part or all of your balance; and a life annuity that provides guaranteed income for life. You can combine them, such as taking steady installments while leaving the rest invested. Withdrawals generally come proportionally from your Roth and traditional balances unless the rules provide otherwise.
Is the Roth TSP or Traditional TSP better for withdrawals?
Neither is universally better; they serve different purposes. Traditional TSP withdrawals are taxed as ordinary income, while qualified Roth TSP withdrawals are tax-free. Having both gives you flexibility to manage your taxable income each year, drawing from Roth in higher-income years to limit Social Security taxation and Medicare surcharges, and from traditional in lower-income years. The best strategy coordinates the two rather than favoring one outright.
Should I roll my TSP into an IRA when I retire?
It depends entirely on your situation, and there are real advantages to both keeping money in the TSP and rolling to an IRA. The TSP offers very low costs, simplicity, the G Fund, and strong creditor protection, while an IRA can offer broader investment choices and consolidation. Because a rollover is hard to reverse and moves money out of a low-cost plan, compare the costs and features carefully for your circumstances, ideally with a fiduciary advisor who must act in your interest.
When do I have to start taking money out of my TSP?
Required minimum distributions from your traditional TSP balance begin at age 73 under current law. You must take your first RMD by April 1 of the year after you turn 73, and subsequent ones by December 31 each year. Roth TSP balances are also subject to plan RMD rules, which is one reason some retirees consider how to position those funds. Planning withdrawals before RMDs begin can help manage your lifetime tax bill.
Can I take money out of my TSP before age 59½?
Yes, but withdrawals before age 59½ may be subject to a 10% early-withdrawal penalty in addition to ordinary income tax, with certain exceptions. One notable exception applies to federal employees who separate from service in or after the year they turn 55 (age 50 for certain public-safety roles), who can take TSP withdrawals without the penalty. The rules are specific, so confirm how they apply to your situation before withdrawing early.
Making your TSP work for your retirement
The best TSP withdrawal strategy is the one built around your actual income needs, tax situation, and goals, drawing on the plan's flexible options and your Roth and traditional balances deliberately. The TSP is an exceptionally well-designed, low-cost plan, which is exactly why the keep-versus-roll decision and your withdrawal mix deserve careful, unbiased thought rather than a default. Jeff Judge and the Chesapeake Financial Planners team help federal employees and military families across Harford County and the Baltimore metro plan their retirement income. Schedule a fit call at chesapeakefp.com.
Sources
- installment payments, single (partial or total) withdrawals, and a life annuity (tsp.gov)
- age 73 (irs.gov)
- 2026 IRMAA threshold of $109,000 for a single filer or $218,000 for a couple (cms.gov)
- 10% early-withdrawal penalty (irs.gov)
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.


