

How does my Social Security claiming decision affect my Medicare premiums?
Last reviewed: July 2026
Your Social Security claiming decision affects your Medicare premiums indirectly but powerfully, because the income you generate while delaying or claiming Social Security can push your modified adjusted gross income over the IRMAA thresholds that raise your Part B and Part D costs. IRMAA, the income-related monthly adjustment amount, is a Medicare surcharge tied to your income from two years earlier. Coordinating when you claim Social Security with the Roth conversions, withdrawals, and other income moves that drive your MAGI is how retirees avoid paying more for Medicare than they need to.
On This Page
- Key Takeaways
- What is IRMAA and how does it work?
- How does Social Security claiming change your IRMAA exposure?
- What are the 2026 IRMAA brackets?
- How can you reduce or appeal IRMAA?
- Related Topics Worth Reading
- Frequently Asked Questions
- Coordinating the decisions that drive your Medicare costs
- Disclosures
Key Takeaways
- IRMAA is a Medicare surcharge added to Part B and Part D premiums once your modified adjusted gross income crosses set thresholds.
- For 2026, IRMAA begins above $109,000 MAGI for single filers and $218,000 for couples, where the standard Part B premium is $202.90.
- Medicare uses a two-year lookback, so your 2026 premiums are based on your 2024 tax return.
- Delaying Social Security, doing Roth conversions, or taking large withdrawals can all spike MAGI and trigger IRMAA, so timing matters.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping Harford County and Baltimore-area retirees coordinate Social Security and Medicare since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: IRMAA is the surcharge almost nobody plans for and almost everybody could reduce, because it is driven by income decisions you actually control in the years before you enroll.
What is IRMAA and how does it work?
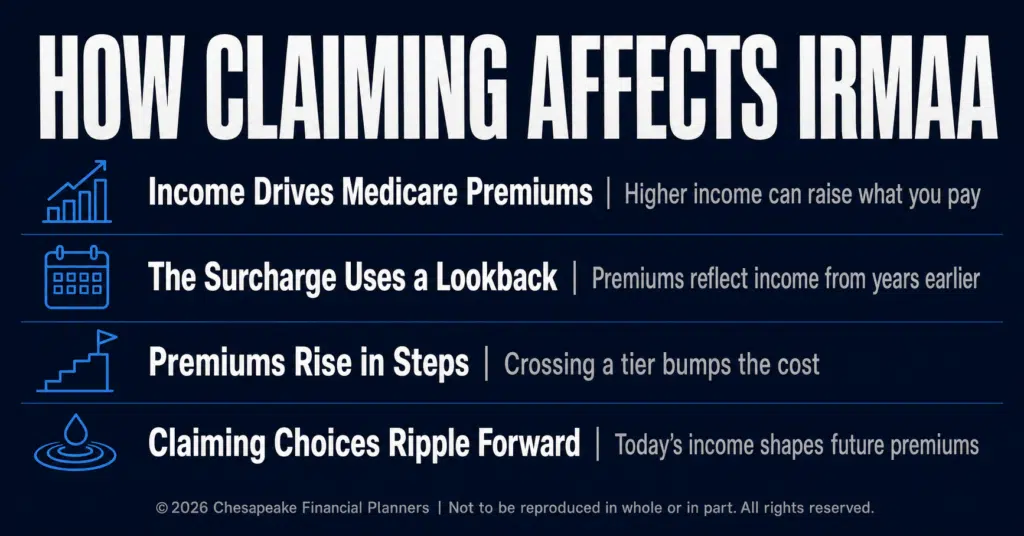
IRMAA is an income-related surcharge added to your Medicare Part B and Part D premiums when your income exceeds certain thresholds, and it can raise your Medicare costs by hundreds of dollars a month. Most beneficiaries pay the standard Part B premium, which CMS set at $202.90 for 2026, but higher earners pay that plus a surcharge across five tiers.
The trigger is your modified adjusted gross income, which is your adjusted gross income plus any tax-exempt interest. As the Social Security Administration puts it, "Your MAGI is your total adjusted gross income and tax-exempt interest income." For 2026, the surcharge starts once MAGI exceeds $109,000 for single filers or $218,000 for a married couple filing jointly. At the first tier, the Part B surcharge adds $81.20 a month on top of the standard premium, and the surcharge climbs at each higher tier up to an additional $487.00 a month at the top.
The detail that catches people off guard is the timing. Medicare uses a two-year lookback, so your 2026 premiums are determined by the tax return you filed for 2024. A one-time income spike two years ago, from a big Roth conversion, a home sale, or a large withdrawal, can raise your Medicare premium today even if your income has since dropped. That lag is exactly why IRMAA has to be planned for in advance.
How does Social Security claiming change your IRMAA exposure?
Your Social Security claiming decision changes your IRMAA exposure by changing the timing and size of the taxable income you report, which is what determines whether you cross an IRMAA threshold. The claiming decision and the IRMAA bill are connected through your MAGI.
Here is the link. When you delay Social Security to grow your benefit, you often fund those gap years by withdrawing from traditional IRAs and 401(k)s, and those withdrawals are taxable income that counts toward MAGI. Done carelessly, the very strategy that boosts your lifetime benefit can also push your MAGI over an IRMAA threshold and raise your Medicare premiums. Conversely, claiming Social Security earlier may keep portfolio withdrawals lower, but a larger share of Social Security itself can become taxable, which also affects MAGI.
The opportunity is in the sequence. Delaying Social Security from full retirement age to 70 raises your monthly benefit to 124% of the full amount, and the low-income gap years before benefits begin are often the best window for Roth conversions, before required minimum distributions and Social Security stack on top of your income. As Jeff Judge puts it, "The years between retiring and turning 73 are the quiet window where most IRMAA and tax savings are won or lost, and a claiming decision made in isolation usually misses them."
What are the 2026 IRMAA brackets?
The 2026 IRMAA brackets set five income tiers that determine your Medicare Part B and Part D surcharges, based on the MAGI from your 2024 tax return. The table below shows the Part B figures for single filers and married couples filing jointly.
| 2026 MAGI (single) | 2026 MAGI (married filing jointly) | Part B premium |
|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 (standard) |
| $109,001 to $137,000 | $218,001 to $274,000 | $202.90 + $81.20 |
| $137,001 to $171,000 | $274,001 to $342,000 | $202.90 + $202.90 |
| $171,001 to $205,000 | $342,001 to $410,000 | $202.90 + $324.60 |
| $205,001 to $499,999 | $410,001 to $749,999 | $202.90 + $446.30 |
| $500,000 or more | $750,000 or more | $202.90 + $487.00 |
The brackets are a cliff, not a ramp. Crossing a threshold by even one dollar moves you into the next tier and applies the full higher surcharge for the year, which is why staying just under a bracket can be worth real money. Part D carries its own parallel surcharges, from $14.50 up to $91.00 a month at the top tier, per the Social Security IRMAA schedule. Both surcharges apply per person, so a married couple who both cross a threshold pay it twice.
How can you reduce or appeal IRMAA?
You can reduce IRMAA by managing the income that drives your MAGI in the years before and during Medicare, and you can appeal it if a life-changing event has lowered your income. Both levers are underused.
On the planning side, the goal is to smooth income so you do not bunch it into a single year that crosses a bracket. Spreading Roth conversions across several lower-income years, using qualified charitable distributions to satisfy required minimum distributions without adding to MAGI, harvesting capital gains deliberately, and timing large withdrawals all help keep MAGI under the next threshold. This is squarely a planning problem. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and IRMAA management lives in Design and Develop, where the claiming, conversion, and withdrawal decisions get sequenced together rather than one at a time.
On the appeal side, IRMAA is not always final. If your income dropped because of a qualifying life-changing event, such as retirement, the death of a spouse, marriage, divorce, or loss of pension income, you can file Form SSA-44 to ask Social Security to use your current, lower income instead of the two-year-old figure. Because the two-year lookback can charge you a surcharge based on income you no longer have, this appeal is one of the most valuable forms a newly retired person can file.
Related Topics Worth Reading
IRMAA sits at the intersection of Social Security, Medicare, and tax planning. These related topics go deeper on each piece.
- The full picture of coordinating Social Security and Medicare in retirement. How do you maximize Social Security and Medicare benefits in retirement?
- How Roth conversions affect your Medicare premiums and lifetime taxes. How do Roth conversions affect IRMAA and Medicare Part B premiums?
- Using the pre-RMD years to cut your lifetime tax bill. How do you use the years between retirement and RMDs to reduce lifetime taxes?
- How qualified charitable distributions keep RMDs out of your MAGI. How Can I Donate From My IRA and Reduce Taxes?
- Building a retirement income plan that manages taxes year by year. What is the best retirement income planning strategy?
Frequently Asked Questions
What income is used to calculate IRMAA?
IRMAA is calculated from your modified adjusted gross income, which is your adjusted gross income plus any tax-exempt interest, such as municipal bond interest. Medicare uses a two-year lookback, so your 2026 IRMAA is based on the MAGI from your 2024 tax return. This includes IRA and 401(k) withdrawals, Roth conversions, capital gains, and the taxable portion of Social Security, all of which you can plan around.
How much can IRMAA add to my Medicare premium in 2026?
In 2026, IRMAA can add between $81.20 and $487.00 per month to your Part B premium, on top of the standard $202.90, depending on your income tier. Part D adds a parallel surcharge of $14.50 to $91.00 a month. The surcharges apply per person, so a married couple who both exceed a threshold each pay the full amount, which can total thousands of dollars a year.
Does delaying Social Security increase my IRMAA?
Delaying Social Security does not directly increase IRMAA, but the way you fund the delay can. Many people who wait to claim withdraw from traditional retirement accounts in the meantime, and those taxable withdrawals raise MAGI, which can push you into a higher IRMAA tier. The fix is to coordinate your claiming decision with your withdrawal and Roth conversion plan, not to make each choice in isolation.
Can I appeal my IRMAA surcharge?
Yes, you can appeal an IRMAA surcharge if a qualifying life-changing event has reduced your income, by filing Form SSA-44 with Social Security. Qualifying events include retirement, marriage, divorce, the death of a spouse, or loss of pension income. Because Medicare bases your premium on income from two years earlier, this appeal lets recently retired people use their current, lower income instead of an outdated higher figure.
What is the IRMAA two-year lookback?
The IRMAA two-year lookback means Medicare sets your premium surcharge using your tax return from two years prior. For 2026 premiums, Social Security uses the MAGI reported on your 2024 return. This lag is why a one-time income event, like a large Roth conversion or a home sale, can raise your Medicare premiums two years later, and why income planning has to look ahead rather than react.
Coordinating the decisions that drive your Medicare costs
The link between Social Security and Medicare is your income, and IRMAA is the surcharge that turns an uncoordinated retirement income plan into a higher Medicare bill. The good news is that the levers, when you claim, when you convert, and when you withdraw, are ones you control, especially in the quiet years before required distributions begin. Jeff Judge and the Chesapeake Financial Planners team help retirees across Harford County and the Baltimore metro sequence these decisions to keep more of their money. Schedule a free fit call at chesapeakefp.com.
Want to go deeper? Our Medicare and Social Security Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


