Last reviewed: October 2026
Financial infidelity breaks a retirement plan by corrupting the numbers it's built on. When one spouse has hidden debt, a private account, or spending the other doesn't see, the household savings rate, net worth, and retirement date in the plan are simply wrong. The fix isn't a budget app. It's one honest conversation where every account goes on a single page, so the plan describes the household you actually have.
Key Takeaways
- Financial infidelity is usually mundane: a separate card, an unmentioned account, or debt carried in from before the marriage.
- A couple each deferring the 2026 401(k) limit of $24,500 can still have a fictional plan if outside money and debt are hidden.
- Privacy means your spouse knows an account exists and roughly what it's for; a secret means they don't.
- Hidden debt often surfaces on a credit report during a mortgage application, so pulling free credit reports together is a practical first step.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement planning and household money decisions since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "A plan built on incomplete information isn't really a plan," Jeff says. "It's a guess with better formatting and a nicer chart."
What Is Financial Infidelity, and Why Does It Break a Good Plan?
Financial infidelity is any money behavior one spouse keeps from the other: hidden debt, a private account, undisclosed spending, or a side venture funded without a real conversation. I sat down with a couple last spring who had done everything right on paper. Two incomes north of $200,000 combined. A 401(k) each, maxed out. A brokerage account with a respectable balance. Then I asked a simple question: "Do you two know what's in each other's individual accounts, down to the dollar?"
Silence. Then a laugh that wasn't really a laugh.
The biggest threat to a household's plan usually isn't the market or the tax code. It's what one spouse doesn't fully know the other is doing with money: a private savings account, a side venture, or $40,000 in student loans from a previous relationship that never got mentioned.
A financial plan is a shared document built from two separate sets of habits, fears, and blind spots. Most couples combined a checking account, split the mortgage, and called it done. The plan looks buttoned-up on a spreadsheet and is quietly inaccurate.
How Does Hidden Money Distort a Retirement Projection?
Every projection starts from a savings rate and a balance sheet. If either is wrong, everything downstream is wrong. One spouse thinks the household saves 20% of income. The other has been redirecting part of a bonus into a separate account for three years because a parent went through an ugly divorce and "you can't be too careful." Neither is lying, exactly. Both are handling risk the way they were taught to: alone.
I watched one couple's projected retirement date move by six years the moment hidden debt came to light. The debt itself wasn't catastrophic. What moved the date was that the whole plan had been built on a savings number that was never true.
"In my experience, the couples whose plans hold up aren't the ones with the most money," Jeff Judge says. "They're the ones where both people could log into every account and see exactly what the other sees."
More income usually makes this worse, not better. RSUs vest on a schedule one spouse tracks and the other barely understands, and a March bonus gets absorbed into "stuff we needed anyway" before the other spouse sees it. Complexity becomes a hiding place: $15,000 spread across four accounts and two employers is easy to lose track of.
What Does Financial Infidelity Look Like in Real Households?
It's rarely scandalous. Most of the time it's ordinary, and it falls into three patterns I see again and again:
- The lifestyle gap only one person sees. One spouse notices the new car and renovated kitchen; the other watches the credit card balance and hopes the bonus covers it. Same account, two stories.
- The "just in case" account. This shows up most with people who watched a parent get wiped out in a divorce. It starts small and stays secret because mentioning it feels like admitting distrust. What it actually does is break every projection built on the household savings number.
- Debt that predates the relationship. Student loans, a tax lien from a business that failed years ago, or a loan from a parent that was never discussed. It sits off to the side until it surfaces on a credit report during a mortgage application, or worse, during a divorce filing with a lawyer in the room instead of an advisor.
There's a quieter version too: hidden advice. One spouse opened a small account years ago with a college friend turned broker and never mentioned it. A decade of separate assumptions later, two people on the same team are running two different games.
Is a separate account always a red flag? No. Plenty of healthy couples keep some individual money, an allowance-style spending account, or a personal card for gifts. The line I use with clients: privacy is when your spouse knows an account exists and roughly what it's for, even without seeing every transaction. A secret is when your spouse doesn't know the account exists, or has been given a balance that isn't accurate. One is a boundary. The other is a blind spot in a plan you're supposedly building together.
None of these are moral failings. Most are coping mechanisms, and they all produce the same result: a plan that looks accurate and is wrong.
Why Is Opting Out of the Money Conversation Not Neutral?
A pattern I see constantly in high-earning, emerging affluent households: one partner handles "the money" because they're better with numbers or more interested, and the other opts out entirely. Opting out isn't neutral. It means one person makes every real decision, and the other agrees to a version of reality they've never checked.
A client told me once, with a straight face, that she didn't want to know the details of the household investment accounts because it stressed her out. Eighteen months later, a business investment her husband made without a real conversation lost most of its value. She had every right to be furious, but she had also handed him full authority the moment she stepped out of the conversation.
Can financial infidelity happen without anyone hiding anything? Yes. Two busy people split money responsibilities early and never revisit the split, and fifteen years later neither has the full picture. It looks identical to financial infidelity, and the fix is the same.
Standard portfolio reviews miss it because they examine only what's visible. That's why I now ask each spouse, separately, at different points in an initial planning conversation, whether there's anything financial the other doesn't fully know about. Not to catch anyone. Because the plan depends on the answer. Our piece on when couples' money biases collide covers the spender-versus-saver side of this.
How Do Maryland Couples Fix Financial Infidelity Before Retirement?
With one uncomfortable conversation, not a new spreadsheet. Every couple I've worked with who fixed this did it by agreeing to full visibility, including the parts that felt embarrassing to say out loud. That conversation is harder than any tax strategy I've recommended, and worth more than most of them. A well-designed Roth conversion schedule doesn't matter if the savings rate it's based on has been fictional for three years.
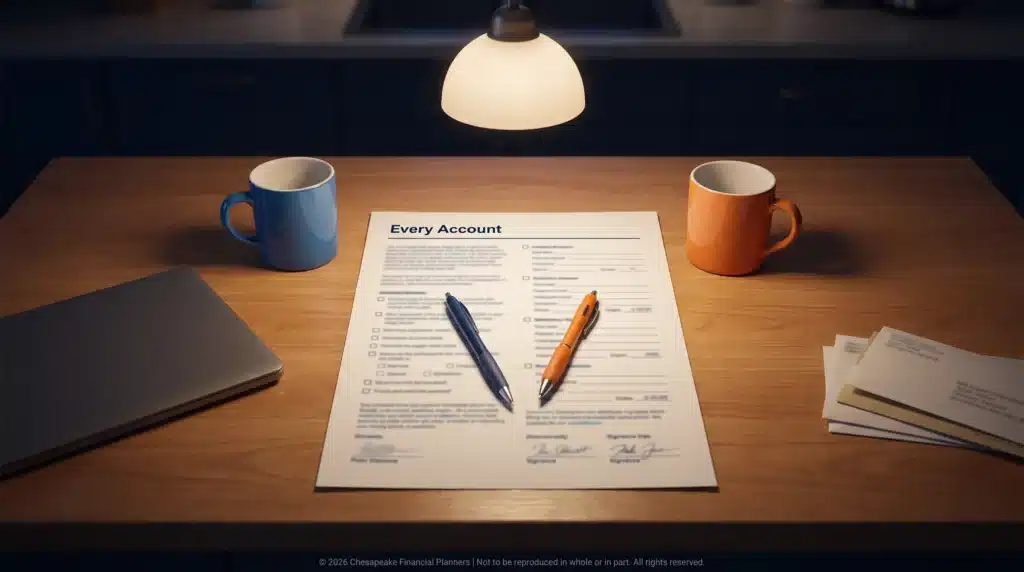
The couples who do it well pick an unglamorous format: one evening, every account listed on a single page, balances and all, no editorializing about how anything got there. For Harford County households, that list often spans more plans than people expect. A spouse at Aberdeen Proving Ground may have a TSP and a FERS pension the other has never logged into, while a Johns Hopkins spouse has a 403(b) and an old 401(k) from a prior job. The TSP, 403(b), and 401(k) each allow up to $24,500 in elective deferrals for 2026, plus an $8,000 catch-up at 50 and older, so two maxed-out spouses can be adding close to $50,000 or more a year in pre-tax savings that belongs on that page.
For couples in Forest Hill, Bel Air, Abingdon, and across the Baltimore metro, we build that one-page view into the first meeting. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Uncover and Understand is where hidden accounts and pre-marriage debt come out, before any projection gets built on them. If you're still deciding how to structure accounts afterward, our guide to joint or separate investment accounts for married couples is a useful next read.
Frequently Asked Questions
What is financial infidelity?
Financial infidelity is when one partner keeps money behavior from the other, such as hidden debt, a secret account, undisclosed spending, or a side investment made without discussion. It's usually mundane rather than scandalous, but it makes a shared financial plan inaccurate because the plan is built on incomplete numbers.
How does financial infidelity affect retirement planning?
Financial infidelity affects retirement planning by distorting the savings rate, debts, and balances a projection depends on. When hidden debt or a private account surfaces, a retirement date can move by years, not because the new information is catastrophic but because the original plan was built on numbers that were never accurate.
Is having a separate bank account financial infidelity?
A separate bank account isn't financial infidelity when your spouse knows it exists and roughly what it's for. Many healthy couples keep some individual money for personal spending or gifts. It becomes financial infidelity when the account is hidden, or when the balance your spouse has been told isn't accurate.
How do you talk to your spouse about hidden debt?
Start with a structured, low-blame format: one evening, every account and debt listed on a single page, balances included, with no editorializing about how anything got there. Pulling both credit reports together helps. Jeff Judge suggests framing it as building an accurate plan, not assigning fault for the gap.
Can a financial advisor help couples with financial infidelity?
A financial advisor can help by asking each spouse directly what accounts, debts, and commitments exist, then building one shared balance sheet and projection from the complete picture. An advisor isn't a therapist, but a structured planning process makes full disclosure feel routine instead of accusatory.
What should Harford County couples list when combining their financial picture?
Harford County couples should list every checking, savings, brokerage, and retirement account, including TSP, FERS, 403(b), and old 401(k) plans from prior jobs, along with all debts, credit cards, and loans from family. Include balances, contribution rates, and who manages each account so the plan reflects the full household.
Could Your Spouse See Every Account Right Now?
Ask yourself the question I asked that couple. If the honest answer makes you flinch, that flinch is the real planning gap, and financial infidelity, even the accidental kind, is easier to fix now than at a mortgage closing or in a divorce filing. Ready to put a plan around yours? Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call
A version of this article was originally published on Jeff Judge's LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
Traditional IRA account owners have considerations to make before performing a Roth IRA conversion. These primarily include income tax consequences on the converted amount in the year of conversion, withdrawal limitations from a Roth IRA, and income limitations for future contributions to a Roth IRA. In addition, if you are required to take a required minimum distribution (RMD) in the year you convert, you must do so before converting to a Roth IRA.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


