
Published: | Last reviewed: November 2026 by Jeff Judge, CFP®
Part of our guide: How Are Financial Advisory Practices Valued for Sale?
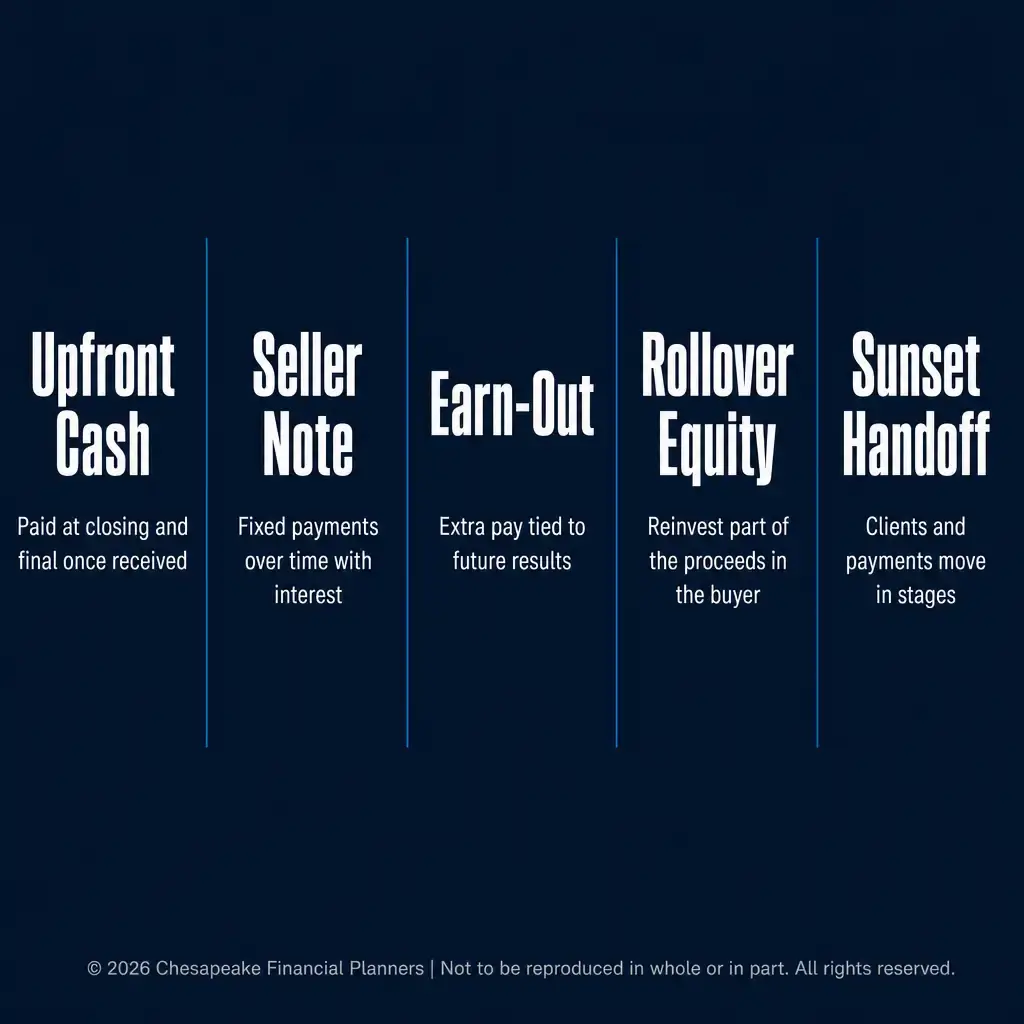
Financial advisory practice sales are usually structured as a blend of cash at closing and payments that arrive later, with the later payments often tied to whether clients stay. The building blocks are upfront cash, a seller note, an earn-out, rollover equity, and a phased or sunset handoff. Each one shifts risk between buyer and seller differently, so the advisory practice sale structure matters as much as the headline price.
Key Takeaways
- Schwab Advisor Services, citing DeVoe & Company, reports more than 300 RIA deals closed in 2025, so these structures are well established.
- Schwab's 2025 RIA Benchmarking Study found 41% of firms pursued inorganic growth, including M&A, in 2024, which means buyers are active.
- A sale can combine cash at closing, a seller note, an earn-out, rollover equity, or a phased handoff, and many deals blend several.
- Capital gains rates of 0%, 15%, or 20% and a possible 3.8% net investment income tax mean deal structure changes what a seller keeps.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate business transitions and exit planning since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "A headline price tells you what a buyer is willing to say; the structure tells you who is carrying the risk."
How Are Financial Advisory Practice Sales Paid For?
Whether you are offering a financial advisor book of business for sale or weighing an RIA acquisition, a buyer rarely pays the whole price in one wire. FP Transitions, which says it has observed thousands of buyers and sellers over two decades, describes the common structure as a cash down payment plus a seller-financed promissory note for the balance. How the price itself is set is covered in How Are Financial Advisory Practices Valued for Sale?
| Structure | How the money arrives | Question for the seller |
|---|---|---|
| Upfront cash | Paid at closing | How much is final and non-refundable? |
| Seller note | Promissory note paid over time with interest | What if clients leave? |
| Earn-out | Extra payments depend on future results | Who controls those results? |
| Rollover equity | Part of the proceeds reinvested in the buyer's equity | Can I sell it later, and at what price? |
| Sunset or phased sale | Clients and payments move in stages | How long must I stay? |
Is a one-payment cash sale common?
No. FP Transitions calls a deal paid entirely in non-refundable cash at closing rare in this space and says such deals usually carry a sizable discount to the purchase price.
How Do Upfront Cash and a Seller Note Work Together?
Upfront cash is what a seller receives at closing. It is the only piece worth face value on day one. A seller note covers part of the balance: the buyer signs a promissory note and pays over several years with interest, which makes it an advisory practice seller note. If you plan to sell a financial advisory practice, the note is where a buyer will ask for assurances. FP Transitions describes performance-based notes with a one-time look-back at the end of the seller's consulting period, so the value can adjust if a meaningful share of client assets does not transfer.
Jeff Judge often points out that a seller note is really a bet on the handoff. Payments feel fair when clients stay comfortable and turn contentious when nobody planned the introductions.
Tax treatment follows structure. Under the IRS installment method, a seller who receives at least one payment after the year of sale may be able to report part of the gain as each payment arrives, while interest counts as ordinary income. Qualifying long-term gain falls under IRS capital gains rates of 0%, 15%, or 20%, and the net investment income tax may apply. Allocating the price among goodwill, consulting, and non-compete agreements can change the result, so a CPA should review it.
How Do Earn-Outs and Rollover Equity Change Who Carries the Risk?
An advisory practice earn-out makes part of the price contingent. The buyer pays extra only if defined results arrive, often client retention or revenue measured after closing. An earn-out also invites disputes, because the buyer often controls the decisions that drive the numbers. Our post on how an earnout clause can cut a business sale price covers those traps.
Advisory practice rollover equity works differently: the seller reinvests part of the proceeds in the equity of the buyer or its platform. FIH's deal-structure guide describes rollover equity as reinvestment rather than deferred payment, illiquid until the acquiring entity itself transacts, where the upside is real and so is the possibility of zero.
Which carries more uncertainty, an earn-out or a seller note?
An earn-out carries more uncertainty about the final amount. A seller note is a fixed promise to pay over time, so the seller's risk is mainly whether the buyer keeps paying. An earn-out depends on future results, so the amount is unknown at closing.
What Is a Sunset Sale, and Do Clients Have to Agree?
A sunset or phased sale keeps the seller in place for a defined period while clients and revenue move to the buyer in stages. Payments often follow the transition, so both sides depend on the handoff.
Clients are part of every structure, because advisory relationships are contracts. The SEC staff explains that Section 205(a)(2) of the Advisers Act "generally makes it unlawful for an SEC-registered adviser to enter into or perform any investment advisory contract unless the contract provides that no assignment of the contract shall be made by the adviser without client consent." A sale therefore needs a client communication plan, not just a signed purchase agreement. Planning for who serves clients in the meantime is covered in What Is a Succession Plan for a Financial Advisor?
How Should You Compare Offers and Plan the Next Step?
Compare offers on certainty, not the headline. Ask:
- What share of the price is paid in non-refundable cash at closing?
- What triggers an adjustment to a note or an earn-out, and who measures it?
- What can the buyer change, such as custodian, fees, or office location, before the measurement period ends?
- How long must I stay, and what are my duties?
- How will the price be allocated for tax purposes, and has my CPA reviewed it?
FP Transitions suggests restricting those buyer changes until the adjustment period ends. Chesapeake Financial Planners acquires advisory practices and applies its planning lens to transitions. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine.
In Jeff's experience, sellers price a practice in their heads as one number, then find that several separate terms decide what they keep. His advice: model each offer with the contingent pieces valued at zero. If the deal still works, the structure is doing its job.
If you are weighing financial advisory practice sales as an exit, start with How Are Financial Advisory Practices Valued for Sale? to understand the price. Then read What Is a Succession Plan for a Financial Advisor? to see how continuity planning fits around a sale.
Frequently Asked Questions
What is the usual way to structure a financial advisory practice sale?
The usual structure pairs cash at closing with a seller-financed promissory note for the balance, according to FP Transitions. Buyers often tie part of the price to client retention. The exact mix depends on the buyer, the financing, and confidence in the transition.
How much of the price does a seller receive at closing?
It depends on the buyer, the financing, and confidence in client retention. Buyers rarely pay entirely in non-refundable cash, and deferred or contingent pieces are common. A specific percentage should come from a written offer and your own advisors, not from a rule of thumb.
Do clients have to approve the sale of an advisory practice?
For SEC-registered advisers, the Advisers Act requires advisory contracts to bar assignment without client consent, so a sale involves notifying clients and obtaining consent as the contract and rules allow. Contract wording and state registration can change the details, so a securities attorney should confirm the process.
What is an earn-out in a practice sale?
An earn-out is a portion of the price paid only if defined results occur after closing, such as client retention or revenue. The seller does not know the final amount at closing. Because the buyer often controls the decisions behind the results, the measurement method deserves careful drafting.
What is rollover equity in a practice sale?
Rollover equity means the seller takes part of the proceeds as an ownership stake in the buyer or its platform instead of cash. It is reinvestment, not deferred payment. The stake is usually illiquid and its value can rise or fall, so the shareholder agreement matters as much as the price.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


