

How Do Maryland's Estate Tax and Inheritance Tax Work Together, and How Do You Plan Around Both?
Last reviewed: July 2026
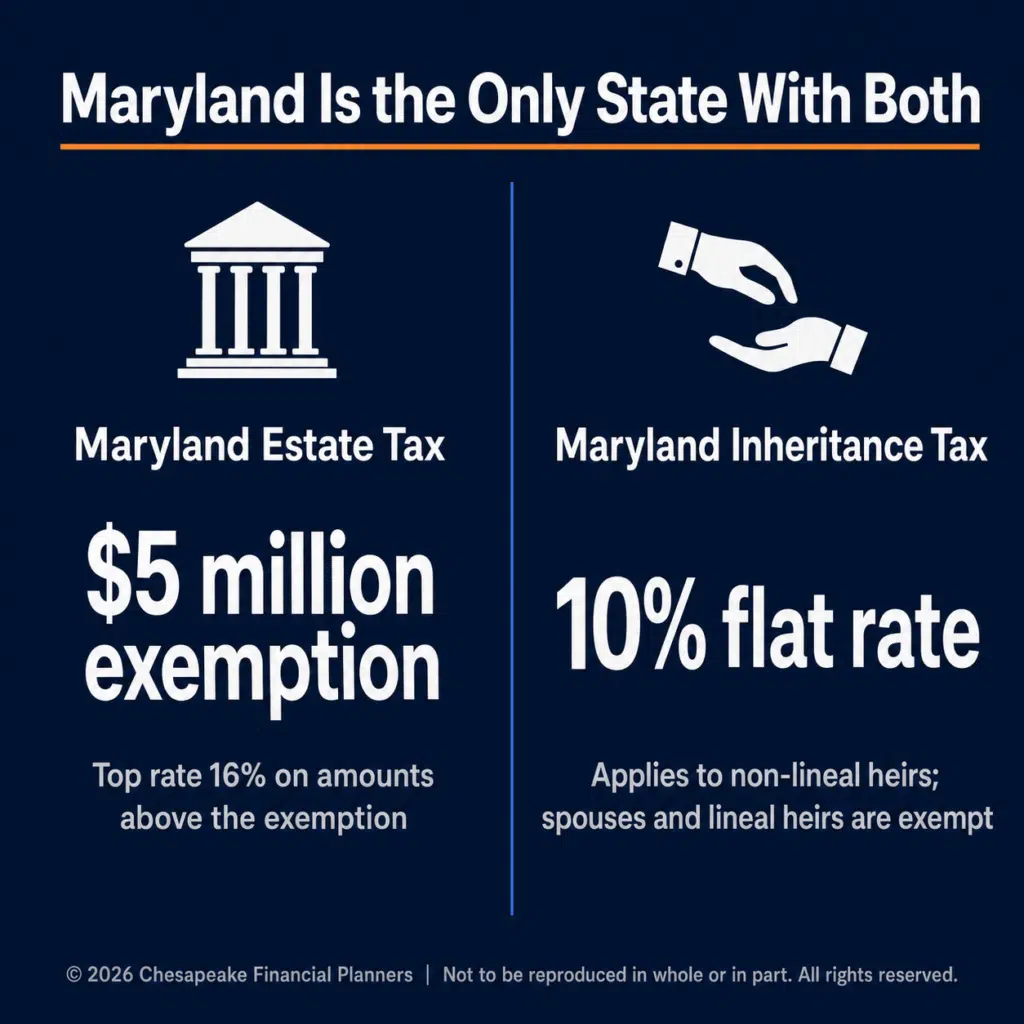
Maryland is the only state in the country that levies both a state estate tax and a separate inheritance tax. The estate tax applies to estates worth more than $5 million and tops out at a 16% rate. The inheritance tax is a flat 10% on assets passing to most non-direct heirs, regardless of estate size. A single estate can owe both, which is why Maryland families need a plan built specifically for these two taxes.
Key Takeaways
- Maryland is the only U.S. state that imposes both an estate tax and an inheritance tax on the same estate.
- The Maryland estate tax exemption is $5 million, well below the 2026 federal exemption of $15 million.
- Maryland's inheritance tax is a flat 10% on assets passing to nieces, nephews, friends, and most non-lineal heirs.
- Spouses, children, parents, grandchildren, and siblings are fully exempt from the Maryland inheritance tax.
- Estate planning around both taxes can save Harford County families tens of thousands of dollars.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate Maryland's complex death tax rules since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched families who assumed they were "safe" under the federal exemption get caught off guard by Maryland's far lower $5 million threshold, and he sees the inheritance tax surprise people more than almost any other rule in the state.
What Is the Difference Between the Maryland Estate Tax and Inheritance Tax?
The Maryland estate tax is paid by the estate before assets are distributed. The inheritance tax is paid based on who receives the assets. These are two separate taxes with two separate triggers, and that distinction trips up a lot of people.
The estate tax looks at the total value of everything the deceased owned. According to the Comptroller of Maryland, if the gross estate exceeds the $5 million exemption, the estate owes a graduated tax that reaches a 16% top rate on the largest estates. This tax is calculated and paid by the estate's representative.
The inheritance tax works differently. It does not care how big the estate is. It cares about the relationship between the deceased and the person inheriting. A flat 10% rate applies to property passing to collateral heirs, which the state defines as anyone outside the direct family line. So a $300,000 bequest to a niece triggers a $30,000 inheritance tax even if the total estate sits well under the estate tax exemption.
Jeff Judge often tells clients in Bel Air that the cruelest version of this is leaving money to a beloved nephew or a longtime friend without planning for it. The gift you intended to be generous shrinks by 10% before it ever reaches them.
Who Pays the Maryland Inheritance Tax in Harford County?
The Maryland inheritance tax applies to most heirs who are not in the direct family line, and the exemptions are based entirely on relationship to the deceased. This is the single most misunderstood rule we explain to families across Harford County.
The following heirs are fully exempt from the Maryland inheritance tax:
- Spouses and surviving spouses
- Children, stepchildren, and their descendants
- Parents and grandparents
- Siblings (brothers and sisters)
- Sons-in-law and daughters-in-law
Everyone else pays the flat 10% rate. That includes nieces, nephews, cousins, aunts, uncles, friends, and unmarried partners. The Register of Wills for Maryland administers and collects this tax through the county where the estate is probated.
This relationship-based structure is why two people who inherit the same dollar amount can owe wildly different taxes. A daughter who inherits $200,000 pays nothing. A niece who inherits the same $200,000 owes $20,000. The asset is identical. The relationship is what changes the bill.
How Does the Maryland Estate Tax Exemption Compare to the Federal Exemption?
The Maryland estate tax exemption is $5 million, while the 2026 federal estate tax exemption is $15 million. That $10 million gap is where most Maryland families get caught, because they plan around the federal number and forget the state has its own, much lower threshold.
Under the One Big Beautiful Bill Act, the federal exemption was set at $15 million per individual starting in 2026 and indexed for inflation going forward. The IRS confirms this is the largest federal exemption in history. Most families hear that number and assume they will never owe estate tax.
Maryland did not follow. The state exemption remains fixed at $5 million and is not indexed to inflation, which means it does not rise each year the way the federal number does. An estate worth $7 million owes zero federal estate tax but is fully exposed to Maryland's tax on the $2 million above the state exemption.
Maryland does allow portability of the estate tax exemption between spouses, similar to the federal rule, but it requires a properly filed Maryland estate tax return to elect it. Skip that filing and the surviving spouse loses the deceased spouse's unused $5 million exemption. We have seen that mistake cost families real money, and it is entirely avoidable with the right paperwork.
How Can Maryland Families Plan Around Both Taxes?
Planning around both Maryland death taxes comes down to structure: who inherits, how assets are titled, and what legal vehicles hold them. There is no single trick, but there are several reliable levers that work together.
For the estate tax, the most common tools are credit shelter trusts (also called bypass trusts) that preserve both spouses' $5 million exemptions, lifetime gifting to move assets out of the taxable estate, and irrevocable life insurance trusts that keep death benefits outside the estate. Charitable giving also reduces the taxable estate dollar for dollar.
For the inheritance tax, the lever is often the structure of the bequest itself. Because the tax is relationship-based, leaving assets to exempt heirs, or restructuring gifts to non-exempt heirs during your lifetime, can sidestep the 10% entirely. Lifetime gifts are not subject to Maryland inheritance tax in most situations.
At Chesapeake Financial Planners, we run this analysis through the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For estate tax work, the Uncover and Understand step is where we map out exactly who inherits and which taxes each bequest triggers before a single document gets drafted.
This is also where coordination matters. We do not draft wills or trusts ourselves. We work alongside your estate attorney, modeling the tax outcomes so the legal documents your attorney prepares actually accomplish what you want. If you do not have an estate attorney, this is the kind of work that calls for one, and we can point you toward experienced Maryland estate counsel.
What do Maryland residents need to know about taxes and benefits before retiring?
How should Aberdeen Proving Ground federal employees manage their FERS, TSP, and benefits?
Frequently Asked Questions
Does Maryland really have both an estate tax and an inheritance tax?
Yes. Maryland is the only state in the country that imposes both a state estate tax and a separate inheritance tax on the same estate. The estate tax applies to estates over $5 million, while the inheritance tax applies a flat 10% to assets passing to most non-direct heirs, regardless of the estate's total size.
What is the Maryland estate tax exemption in 2026?
The Maryland estate tax exemption is $5 million, according to the Comptroller of Maryland. This amount is set by statute and is not indexed for inflation, so it stays fixed each year. Estates valued above $5 million owe a graduated Maryland estate tax that reaches a top rate of 16%.
Who is exempt from the Maryland inheritance tax?
Spouses, children, stepchildren, grandchildren, parents, grandparents, and siblings are fully exempt from the Maryland inheritance tax. Everyone else, including nieces, nephews, cousins, friends, and unmarried partners, pays a flat 10% rate on the value of what they inherit. The exemption depends entirely on the heir's relationship to the deceased.
Can a single Maryland estate owe both taxes at once?
Yes, a single estate can owe both the Maryland estate tax and the inheritance tax. The estate tax is paid by the estate if its value exceeds $5 million, and the inheritance tax is paid separately based on which non-exempt heirs receive assets. A large estate leaving money to nieces or nephews would trigger both.
How is the Maryland inheritance tax different from the federal estate tax?
The federal estate tax only applies to estates over $15 million in 2026 and is paid by the estate. The Maryland inheritance tax applies regardless of estate size and is based on who inherits, taxing non-direct heirs at 10%. Many Harford County families owe Maryland tax even when no federal tax is due.
Do I need an estate attorney for Maryland estate planning?
Yes, planning around Maryland's estate and inheritance taxes typically requires a qualified estate attorney to draft wills, trusts, and related documents. At Chesapeake Financial Planners, we coordinate with your attorney by modeling the tax outcomes first, so the legal documents accomplish your goals and minimize both Maryland death taxes.
Maryland's two-tax structure is one of the few places where good planning produces a clear, measurable savings number, and where doing nothing has an equally clear cost. If you live in Harford County or anywhere in the Baltimore metro and your estate is approaching or above $5 million, or you plan to leave assets to anyone outside your direct family line, the maryland estate tax inheritance tax question is worth running through real numbers. Jeff Judge and the Chesapeake Financial Planners team in Forest Hill model these outcomes alongside your estate attorney. Schedule a call at chesapeakefp.com to see exactly what both taxes would cost your family, and what a plan could save.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


