PSLF and Student Loan Repayment Calculator
When Will You Reach 120 PSLF Payments?
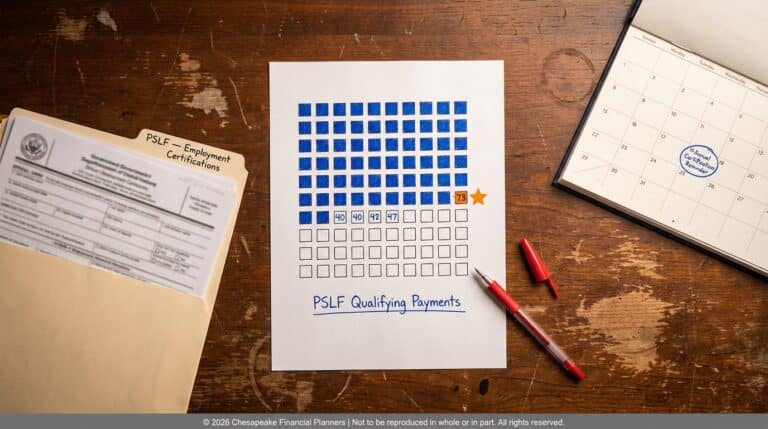
Count forward one month for each full, on-time qualifying payment until you reach 120; the payments need not be consecutive (Federal Student Aid). With 36 payments counted, the 120th falls 84 qualifying payments later. This calculator finds that month, totals what you would pay until then, and estimates what could be left to forgive.
What Does the PSLF Calculator Estimate?
Public Service Loan Forgiveness (PSLF) forgives the rest of your federal Direct Loan balance after 120 qualifying monthly payments made while you work full time for a qualifying government or not-for-profit employer (Federal Student Aid). The payments do not need to be in a row. What counts is who you work for, not your job title, and the repayment plan you are on.
This calculator counts forward from the payments you have made, using the payment path you choose, to find the month of your 120th payment. It tracks interest and the balance year by year, shows what would be left to forgive, and lists which repayment plans are open to you under the 2026 rules, with plan payment estimates at your income. If you choose, it also shows what leaving public service early would cost and compares a pay-off path. StudentAid.gov and your loan servicer decide your actual payments, your qualifying payment count, and any forgiveness. It is not advice.
How Is Your 120th PSLF Payment Date Calculated?
What it estimates: the month of your 120th qualifying payment, the payments counted and left, the earliest month to apply, what you pay until then, the balance that could be forgiven, your next payment, which repayment plans are open to you and whether they count toward PSLF, and, with your optional inputs, what leaving public service early or paying the loans off would mean.
What you enter: Your Loans: Loan Groups to Enter, Federal Loan Balance and Average Interest Rate (for up to four loan groups), Any Loan First Disbursed On or After July 1, 2026?, Do Your Loans Include a Parent PLUS Loan?, and When You First Borrowed. Public Service: Your Employer, Do You Work Full Time There?, Your Repayment Plan, and Qualifying Payments Counted So Far. Your Payments: Your Monthly Payment and How Your Payment Changes (stays the same, changes by a percent each year, steps up in a year you choose, or follows your income year by year). Household and Tax Filing: Marital Status, your adjusted gross income (AGI) and your spouse’s if married, payments if filing separately or jointly, Family Size, Dependents You Claim, and AGI Lowered by Added Pre-Tax Retirement Contributions. Compare Paths (Optional): If I Left Public Service After This Many More Payments, and a pay-off path interest rate, years, and return.
Two modes: Quick estimate mode, the default, asks for Federal Loan Balance, Average Interest Rate, Any Loan First Disbursed On or After July 1, 2026?, Your Employer, Your Repayment Plan, Qualifying Payments Counted So Far, Your Monthly Payment, Marital Status, your AGI, Family Size, and Dependents You Claim, and holds every other field at the calculator’s default; Detailed mode shows every field. Both modes run the same calculation.
1. Are payments counting?
Your employer, full-time work, loan type, and repayment plan decide whether payments count toward PSLF now.
2. The count
From the payments counted so far, each future full, on-time payment adds one, starting next month, until payment 120.
3. What you pay
Your monthly payment along the path you choose, added up until payment 120.
4. The balance
Simple interest on the balance at your rate, with unpaid interest carried rather than added to principal, giving what could be left to forgive.
5. Your plan options
Which 2026 repayment plans are open to you, whether each counts toward PSLF, and its estimated payment at your income.
6. Compare paths (optional)
What you would have paid and still owe if you left public service after a number of payments, and a pay-off path for comparison.
What you see: Month of Your 120th Payment first, then Payments Counted, Payments Left, Earliest Month to Apply, You Pay Until Then, Balance That Could Be Forgiven, Payment Next Month, and, when you enter them, the leave and pay-off comparisons. A year-by-year table shows payments, what is owed, and the count, and a table lists the repayment plans open to you.
What Assumptions and Sources Does It Use?
- Rules as of: October 4, 2026, with the 2026 federal plan formulas and the 2026 HHS poverty guideline.
- PSLF: forgiveness of the remaining Direct Loan balance after 120 qualifying monthly payments, not necessarily in a row, while working full time for a qualifying government or not-for-profit employer. Certify your employment every year and when you change employers (Federal Student Aid).
- Payment timing: the first payment is next month, and every payment is full, on time, and qualifying. The months move with the date you use the calculator.
- Interest: simple interest at your rate; unpaid interest is carried, not added to principal.
- Plan changes in 2026: Tiered Standard Plan payments do not count toward PSLF (91 FR 23840). If any of your loans was first disbursed on or after July 1, 2026 (Federal Student Aid), you lose access to the IBR, ICR, and PAYE plans and the 10-year Standard Plan for all your Direct Loans, and the Repayment Assistance Plan (RAP) is open to eligible loans. Parent PLUS loans have their own rules (34 CFR 685.208; 91 FR 23840).
- Private loans: moving federal loans into a private loan (see refinancing student loans) can give up income-driven repayment and forgiveness, including PSLF.
- Held back until verified: the Income-Contingent Repayment (ICR) payment.
- Not modeled: plan-specific interest relief, capitalization, deferment, forbearance, buyback, and state tax.
Worked Example
The example
This is the calculator’s built-in Detailed example (the “Reset to example” values). Every figure below is the calculator’s own output for these inputs, run with the date fixed at November 2, 2026, so the first future payment is in December 2026. It is hypothetical and uses the rules as of October 4, 2026.
Inputs
| Input | Example value |
|---|---|
| Loan Groups to Enter | One Total |
| Federal Loan Balance | $220,000 |
| Average Interest Rate | 6.8% |
| Any Loan First Disbursed On or After July 1, 2026? | No, All Were Disbursed Earlier |
| Do Your Loans Include a Parent PLUS Loan? | No |
| When You First Borrowed | On or After July 1, 2014 |
| Your Employer | Tax-Exempt 501(c)(3) Not-for-Profit |
| Do You Work Full Time There? | Yes |
| Your Repayment Plan | Income-Driven Plan (RAP, IBR, PAYE or ICR) |
| Qualifying Payments Counted So Far | 36 |
| Your Monthly Payment | $450 |
| How Your Payment Changes | Steps Up in a Year I Choose |
| Year the Payment Changes | 2028 |
| Monthly Payment From Then On | $1,800 |
| Marital Status | Single |
| Your Adjusted Gross Income (AGI) | $90,000 |
| Family Size | 1 |
| Dependents You Claim | 0 |
| Compare Paths | Not entered |
Results
| Result | Estimate |
|---|---|
| Month of Your 120th Payment | November 2033 |
| Payments Counted | 36 of 120 |
| Payments Left | 84 |
| Earliest Month to Apply | November 2033 |
| You Pay Until Then | $133,650 |
| Balance That Could Be Forgiven | $186,437 |
| Payment Next Month | $450 |
The calculator summarizes it this way: “At 36 of 120, your 120th qualifying payment would be in November 2033. On the payments you entered, about $186,437 could be left to forgive after paying about $133,650.” Its plan table shows, at a $90,000 AGI, estimated monthly payments of $600 under the Repayment Assistance Plan (RAP), $551 under Income-Based Repayment (IBR) and Pay As You Earn (PAYE), and $2,532 under the 10-year Standard Plan, all of which count toward PSLF if paid on time and in full. Results for your own inputs will differ.
Reviewed by Jeff Judge, CFP®, AEP®, ChFC®, CLU®, Managing Partner, Chesapeake Financial Planners. Last updated November 2, 2026. Tax year 2026.
Frequently Asked Questions
When will I reach 120 qualifying payments?
Count forward from the payments already counted, one for each full, on-time qualifying payment. In the example above, 36 payments are counted, 84 are left, and with the first future payment in December 2026, the 120th would fall in November 2033, which is also the earliest month to apply.
How much could be forgiven under PSLF?
Whatever is left on your Direct Loans after payment 120. In the example, paying $450 a month until the end of 2027 and $1,800 a month from 2028 would total $133,650, and about $186,437 of the $220,000 balance, with interest at 6.8%, could be left to forgive.
What if I leave public service before 120 payments?
Payments stop counting while you work for an employer that does not qualify, and the balance stays with you. In the example, leaving after 24 more payments, you would have paid $25,650 and still owe $224,270. The calculator shows this when you enter the number of payments.
Does working for a for-profit employer count?
No. Payments made while you work for a for-profit employer, or while self-employed, do not count toward PSLF (Federal Student Aid). In the example, with a for-profit employer, the calculator shows payments as not counting toward the 120. Payments you already made at a qualifying employer still count if you return to public service later.
Which repayment plans count toward PSLF in 2026?
Income-driven plans and the 10-year Standard Plan count when paid on time and in full. Tiered Standard Plan payments do not (91 FR 23840). If any of your loans was first disbursed on or after July 1, 2026, you lose access to IBR, ICR, PAYE, and the 10-year Standard Plan for all your Direct Loans, and the Repayment Assistance Plan (RAP) is open to eligible loans. The calculator lists the plans open to you and their estimated payments.
Is this calculator from the Department of Education?
No. It is not affiliated with, endorsed by, or sponsored by the U.S. Department of Education, Federal Student Aid, or any loan servicer. You can apply for PSLF, change repayment plans, and consolidate federal loans for free at StudentAid.gov or through your loan servicer.
Related planning services: Financial Planning for Emerging Affluent Professionals.
Related calculators: First Job 401(k) Match and Roth Calculator, 403(b) and 457(b) Contribution Calculator and 529 Education Savings Calculator.
See all financial planning calculators
Want to talk through your own numbers with an adviser?
Important disclosures
This calculator is for educational purposes only. It provides a simplified, hypothetical estimate based on the numbers you enter and federal rules as of the date shown. It assumes every future payment is a full, on-time qualifying payment and that your payment follows the path you choose, which real payments may not. StudentAid.gov and your loan servicer decide your actual payments, your qualifying payment count, and any forgiveness. This calculator is not affiliated with, endorsed by, or sponsored by the U.S. Department of Education, Federal Student Aid, or any loan servicer. It is not tax, legal, investment, or financial planning advice. Rules change, and results are not guaranteed.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor. All investing involves risk including loss of principal. No strategy assures success or protects against loss. There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. DiversificationSpreading investments across multiple asset classes, sectors, and geographies so a loss in one area doesn’t devastate your entire portfolio. It’s the financial equivalent of not putting all your eggs in one basket — and it’s one of the few strategies that can reduce risk without necessarily reducing expected returns. does not protect against market risk.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group and Chesapeake Financial Planners are separate entities from LPL Financial.