

How do I find a CFP near Forest Hill, MD?
Last reviewed: July 2026
To find a CFP near Forest Hill, MD, start with the CFP Board's "Find a CFP® Professional" search tool at cfp.net, enter zip code 21050 or "Harford County, MD," and confirm each candidate's fiduciary status, compensation model, and disciplinary history before booking a fit call. The CFP® designation tells you a planner met serious education, exam, and ethics standards, but it does not tell you how they get paid. Verifying that is on you, and it takes about twenty minutes.
Key Takeaways
- Use the CFP Board's free search tool at cfp.net with zip code 21050 to find verified CFP® holders near Forest Hill.
- As of 2025, 104,000+ professionals held the CFP® designation nationwide, a small fraction of those calling themselves advisors.
- Always ask whether a planner is a fiduciary 100% of the time across every service they provide.
- Check FINRA BrokerCheck and the SEC's adviser disclosure site before any first meeting.
- A fit call is a mutual screening conversation, not a sales pitch, and a good local planner welcomes it.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate the search for trustworthy financial advice since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched too many people in this area hire on a referral alone and skip the twenty-minute verification that would have told them everything.
Why the CFP® Designation Matters When You Search in Harford County
The CFP® (Certified Financial Planner) credential is earned, not bought. To hold it, a planner must complete a CFP Board-approved education program, pass a rigorous exam, accumulate at least 6,000 hours of professional financial planning experience (or 4,000 hours in an apprenticeship), and meet ongoing ethics and continuing education requirements set by the CFP Board.
The gap between the credential and the title is wide. As of early 2025, more than 104,000 individuals in the United States held the CFP® designation, out of an estimated population of several hundred thousand people who call themselves "financial advisors." The term "financial advisor" has no federal standard. Anyone can use it. The CFP® mark means something specific was earned and is being maintained.
Jeff Judge, CFP® at Chesapeake Financial Planners in Forest Hill, has held the designation for over a decade. "The CFP® mark tells you that someone went through a serious credentialing process," he says. "It doesn't tell you everything. You still need to understand how they're compensated and whether they act as a fiduciary. But it's the right starting point for any advisor search in Harford County."
That starting point matters here specifically. Harford County has a concentration of business owners, government and military retirees, and dual-income professionals, and each of those situations rewards working with someone who plans for the whole picture rather than selling one product.
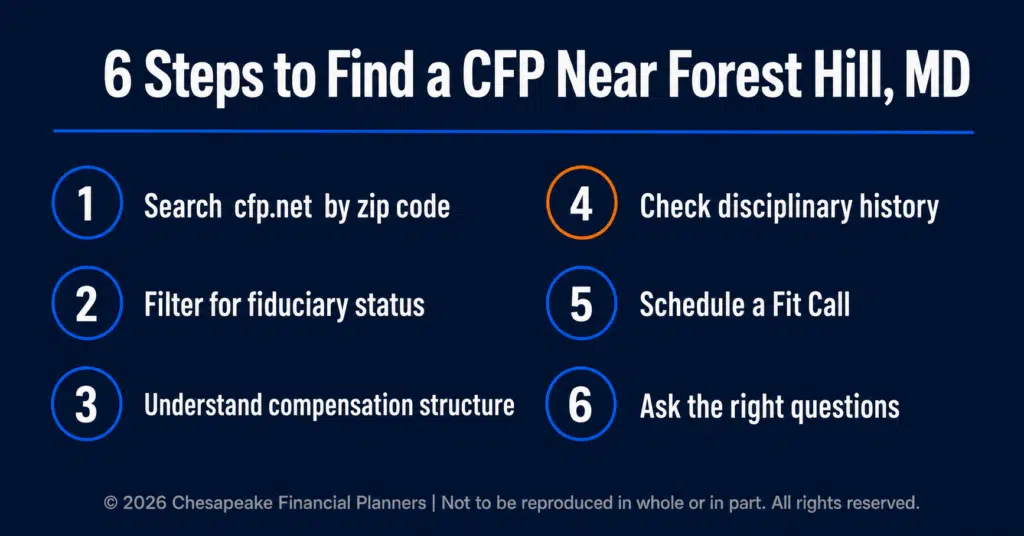
How to Find a CFP Near Forest Hill, MD: A Practical Process
Finding the right planner near Forest Hill is a verification exercise, not a guessing game. Work through these steps in order and you will know more about a candidate before the first meeting than most people learn after the third.
First, use the CFP Board's "Find a CFP® Professional" search at cfp.net. Enter zip code 21050 for Forest Hill or search "Harford County, MD." This database verifies current credential status and surfaces any public disciplinary actions, so it filters your list down to genuine CFP® holders immediately.
Second, filter for fiduciary status. Being a CFP® professional does not automatically mean someone acts as a fiduciary at all times. Some advisors operate under a fiduciary standard for planning advice but a suitability standard when recommending products. A registered investment advisor (RIA) is required by law to act as a fiduciary, and the SEC regulates these firms directly. Ask the plain question: "Are you a fiduciary 100% of the time, for every service you provide?" Anything short of a clear yes is your cue to dig deeper.
Third, understand how they get paid, because compensation shapes advice whether a planner intends it or not.
| Compensation Model | Who Pays the Planner | Main Consideration |
|---|---|---|
| Fee-only | You, directly (retainer, hourly, or % of assets) | No commissions; eliminates the most common conflict of interest |
| Fee-based | You plus commissions on some products | Both streams disclosed; commission incentives still worth understanding |
| Commission-only | Product companies, through sales | No direct fee, but income depends on product placement |
Ask for Form ADV Part 2, which every registered investment advisor must provide. It discloses compensation, conflicts of interest, and services in plain language.
Fourth, check disciplinary history. Use FINRA BrokerCheck for registration history and complaints, and the SEC's Investment Adviser Public Disclosure site for Form ADV and any enforcement actions. A clean record is not a guarantee, but a disclosed action is something you want to understand before moving forward.
Jeff structures every engagement at Chesapeake using the firm's planning method. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. "We don't give advice before we understand the full picture," Jeff says. "That means income, expenses, assets, liabilities, and what you're actually trying to accomplish."
For a deeper look at the questions that separate a good fit from a bad one, see our guide on What should I look for in a financial advisor in Maryland?.
What to Expect From a Local CFP in Forest Hill and Harford County
Forest Hill and the surrounding Harford County area has a mix of practices, from large national firms with local branches to independent firms like Chesapeake Financial Planners that are based in the community and serve clients who live and work nearby. A planner who knows the Harford County landscape brings context a remote advisor often cannot.
In-person planning remains the preference for many clients here, particularly around major transitions: approaching retirement, selling a business, receiving an inheritance, or navigating a divorce. Chesapeake's office sits at 2402 Scotlon Ct in Forest Hill, a short drive from Bel Air, and that proximity matters to families who want to sit across a table when the stakes are high. According to the Bureau of Labor Statistics, there were roughly 321,000 personal financial advisors employed nationally as of 2024, but only a fraction hold the CFP® mark and work locally in a community like this one.
Virtual planning is available too. If your schedule or mobility makes in-person meetings difficult, most local practices offer secure video sessions. If you are weighing the two, our breakdown of What Are the Real Differences Between a Virtual and In-Person Financial Advisor in Maryland? walks through what actually changes and what does not.
A pattern Jeff sees constantly: people in this area hire on a single referral from a neighbor or coworker and never run the verification. The referral might be a great planner. They might also be a commissioned salesperson who happened to be friendly. The twenty minutes it takes to check fiduciary status and compensation is the cheapest insurance you will ever buy. If you want a structured list, our post on What questions should I ask when interviewing a fee-only financial advisor in Maryland? gives you seven questions to bring to that first call. You can also learn what a What does a fiduciary financial advisor in Harford County do that a broker doesn't? actually does day to day.
Frequently Asked Questions
Is there a difference between a financial planner and a financial advisor?
In practice the terms are used interchangeably, but "financial advisor" is not a regulated title while "CFP®" is. When the CFP® credential appears, it signals specific education, examination, experience, and ethics requirements that the broader "advisor" label does not require. Treat the credential as the meaningful distinction.
Do I need a minimum amount of assets to work with a CFP near Forest Hill, MD?
It depends on the firm. Some practices in Harford County set asset minimums, often in the $250,000 to $500,000 range, while others charge flat fees or retainers and work with clients at any asset level. When you book a fit call, ask directly about minimums before the meeting so there are no surprises.
Can a CFP near Forest Hill, MD help with taxes?
A CFP® professional can help with tax-aware planning, such as Roth conversion timing, capital gains strategy, and withdrawal sequencing in retirement. They generally do not file your return unless they also hold a CPA or EA credential. Many local planners coordinate directly with your tax preparer so the strategy and the filing stay aligned.
How much does a CFP cost in Forest Hill and Harford County?
Costs vary by model: fee-only planners may charge an hourly rate, a flat annual retainer, or roughly 0.5% to 1.5% of assets managed, while fee-based planners may combine fees with product commissions. Ask for the total annual cost in dollars, not just a percentage, and request Form ADV Part 2 for full disclosure. See our How much does a CFP cost in Maryland? guide for detail.
How do I verify a CFP's credentials are current?
Use the CFP Board's free verification tool at cfp.net to confirm active status and check for public discipline. Then cross-reference FINRA BrokerCheck and the SEC's adviser disclosure database. This three-step check takes about twenty minutes and tells you whether the credential is genuine and the record is clean before you ever meet.
If you are searching for a CFP near Forest Hill, MD and want a straightforward conversation about your situation, Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County and the Baltimore metro. We work through this exact decision with clients every week, and a fit call costs you nothing. Visit chesapeakefp.com to schedule one.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


