
What is an ILIT, and how does it keep life insurance out of my estate?
Last reviewed: July 2026
An irrevocable life insurance trust (ILIT) is a separate legal entity you create to own your life insurance policy so the death benefit passes to your heirs without being counted in your taxable estate. When the policy is properly owned by the ILIT and the rules are followed, the proceeds go to your beneficiaries free of federal estate tax and, in states with their own estate tax, often free of state estate tax too. For families closing in on the federal exemption or Maryland's $5 million state threshold, that single decision can shift hundreds of thousands of dollars from the government back to the next generation.
On This Page
- Key Takeaways
- What Is an Irrevocable Life Insurance Trust (ILIT)?
- How Does an ILIT Keep Life Insurance Out of Your Estate?
- How Do You Fund an ILIT and What Is a Crummey Letter?
- When Does an ILIT Make Sense, and What Are the Tradeoffs?
- Related Topics Worth Reading
- Frequently Asked Questions
- Disclosures
Key Takeaways
- An ILIT owns your life insurance policy so the death benefit is excluded from your taxable estate under IRC §2042.
- Maryland's $5 million state estate tax exemption is far below the federal $15 million OBBBA exemption, so ILITs are useful for many Maryland families.
- Transferring an existing policy to an ILIT triggers a three-year lookback under IRC §2035 before the policy is fully out of your estate.
- Funding the ILIT to pay premiums usually uses annual exclusion gifts of $19,000 per beneficiary in 2026, backed by Crummey notice letters.
- An ILIT is irrevocable, so the structure is hard to undo; that is the main tradeoff to weigh before signing.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate planning and life insurance strategy since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the most expensive mistake he sees in estate plans is not the tax rate; it is the policy that was supposed to be outside the estate but wasn't, because the lookback period ran out a year short.
What Is an Irrevocable Life Insurance Trust (ILIT)?
An irrevocable life insurance trust (ILIT) is a trust that owns one or more life insurance policies on your life, with named beneficiaries who receive the death benefit through the trust rather than directly. The word "irrevocable" is doing real work. Once you sign the trust agreement and either transfer an existing policy or fund the trust with cash to buy a new one, you give up the right to change the terms, swap beneficiaries, or pull the policy back into your own name.
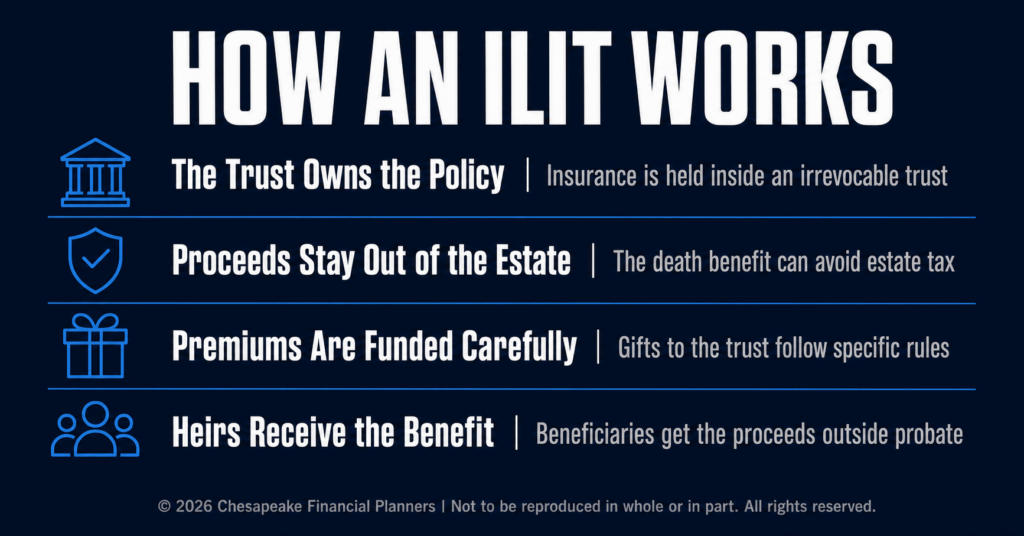
That permanence is the whole point. Because you no longer own the policy and have no "incidents of ownership" over it, IRC §2042 keeps the proceeds out of your gross estate at death. The trustee, not you, owns the policy, pays the premiums from trust assets, and distributes the death benefit per the terms you wrote into the trust.
A few features are common across well-drafted ILITs. You name an independent trustee, often a family member who is not the insured, a professional fiduciary, or a trust company. The trust holds the policy and any cash you contribute each year to pay premiums. Beneficiaries are usually a spouse, children, or grandchildren, and the trust can pay them outright or hold the money for asset protection.
What an ILIT is not: it's not a way to control the policy after the fact, and it's not a magic loophole. It is a specific structural choice, governed by a specific section of the Internal Revenue Code, that you make on purpose, in advance, with clear eyes about what you are giving up.
How Does an ILIT Keep Life Insurance Out of Your Estate?
The life insurance estate tax problem is simple: under IRC §2042, the death benefit of any policy in which the decedent held "incidents of ownership" at death is included in the gross estate. That phrase covers the right to change beneficiaries, take loans, surrender, assign, or borrow against the policy. If you own it outright, the IRS counts the death benefit in your estate.
An ILIT cuts this chain. The trustee owns the policy, holds the incidents of ownership, and makes the policy decisions during your lifetime. You are the insured, not the owner. When you die, the policy pays out to the trust, and because you held no incidents of ownership at death, §2042 does not pull the proceeds into your estate.
For families near the federal estate tax exemption of $15 million per person under OBBBA, the savings can run into seven figures at the 40% top federal estate tax rate. For Maryland residents, the math is more aggressive. The state's estate tax kicks in at $5 million per person, with a top state rate of 16%. A $2 million policy on a Maryland resident with an otherwise $4 million estate can swing the result from no Maryland tax to a meaningful bill. For married couples near or above the federal exemption, a common ILIT structure pairs the trust with a second-to-die survivorship policy that pays only at the second death, when the estate tax bill actually lands.
The three-year lookback if you transfer an existing policy
Here is the catch that trips up half the families coming to us for an estate plan refresh: if you already own a policy and transfer it into a new ILIT, IRC §2035 pulls the death benefit back into your estate if you die within three years of the transfer. The clock starts on the transfer date, not the trust signing date.
There are two clean ways around this. The first is to buy a new policy through the ILIT from day one, so the trust is the original applicant, owner, and beneficiary; nothing has to "transfer" because you never owned it. The second is to transfer an existing policy and live three years past the transfer date, which most healthy clients will. The risk lives with older or already-sick clients, where the three-year rule can swallow the entire planning move.
How Do You Fund an ILIT and What Is a Crummey Letter?
Premiums on an ILIT-owned policy have to come from somewhere, and you can't write a check directly to the insurance company without compromising the structure. The trustee pays premiums from trust assets, and those assets almost always come from gifts you make to the ILIT each year.
Gifts to a trust are usually treated as gifts of a future interest, which do not qualify for the annual gift tax exclusion of $19,000 per recipient in 2026. Future-interest gifts come off your $15 million lifetime estate and gift tax exemption, which most families want to preserve.
The Crummey letter solves this. Named after the 1968 case Crummey v. Commissioner, a Crummey provision in the trust gives each beneficiary a short-term right, usually 30 days, to withdraw their share of any new contribution. The trustee sends written notice each time you contribute, explains the withdrawal right, and lets the window run. Beneficiaries don't exercise the right; they let it lapse, and the trustee uses the money to pay that year's premium. Because the withdrawal right existed, the contribution qualifies as a present-interest gift and fits inside your annual exclusion.
This is exactly where most do-it-yourself ILITs fall apart. Skipping the Crummey notice letters, or sending them after the trustee has already paid the premium, is the single most common ILIT mistake we see. The IRS has built case law around this paper trail, and the trail has to be real and contemporaneous, not reconstructed at audit. Jeff often tells clients: "The Crummey letter that nobody opens is the one doing the heavy lifting. It's the proof you have when an examiner asks why a $19,000 gift to a trust shouldn't chew into your lifetime exemption."
There is one subtle wrinkle: well-drafted ILITs cap each beneficiary's withdrawal right at the "5 and 5" limit, the greater of $5,000 or 5% of trust assets, to avoid an unused lapse being treated as a gift back from the beneficiary to the trust.
A couple gifting to an ILIT with three adult-child beneficiaries can move up to $38,000 per beneficiary, or $114,000 per year, into the trust under the 2026 annual exclusion, which covers most family-level term or permanent insurance premiums. Excess premiums count against the lifetime exemption and require a Form 709 gift tax return.
When Does an ILIT Make Sense, and What Are the Tradeoffs?
The decision to set up an ILIT comes down to whether the estate tax savings justify the loss of control. For high-net-worth families with significant life insurance, the math is usually clear. For families well below all applicable exemptions, it usually is not.
A useful screen: an ILIT makes sense when the projected estate, including the life insurance death benefit, exceeds either the federal estate tax exemption or a state estate tax threshold where you live, and the family wants the death benefit to go to heirs intact, often to cover the estate tax bill on illiquid assets like a closely held business or appreciated real estate.
Maryland deserves a separate look. Because the Maryland estate tax exemption sits at $5 million, a family in Forest Hill or anywhere else in the state can be well below the federal threshold and still face state estate tax on a death benefit that pushed them past $5 million.
The tradeoffs are real. Once the trust is signed and funded, you can't pull the policy back, change beneficiaries directly, or use the cash value for your own needs. The trustee, not you, controls the policy. Most ILITs are drafted as grantor trusts for income tax purposes, so any investment income is taxed at the grantor's individual rate rather than compressed trust rates. There is upfront legal cost, usually a few thousand dollars to draft, plus ongoing administrative effort to keep Crummey letters and trust accounting clean each year.
Jeff has watched clients sign trust documents in a Tuesday afternoon meeting and regret the irrevocability eighteen months later, after a family change made the original beneficiary structure feel wrong. The right time to sign an ILIT is when the analysis is settled and the family is aligned, not when an estate planning attorney has a slot open next week.
Personally-owned policy vs. ILIT-owned policy
| Dimension | Personally Owned | ILIT-Owned |
|---|---|---|
| Death benefit included in your estate? | Yes (under IRC §2042) | No, if structured correctly and three-year rule cleared |
| Right to change beneficiaries | You | Trustee per trust terms |
| Access to cash value during life | Yes | No |
| Federal estate tax exposure on proceeds | Up to 40% if over the exemption | None on properly structured trust |
| Maryland estate tax exposure on proceeds | Up to 16% if state estate exceeds $5M | None on properly structured trust |
| Administrative effort | Minimal | Annual Crummey letters, trust accounting |
| Reversible? | Fully (you control it) | No (irrevocable by definition) |
The decision is not whether to "do an ILIT." It is whether the life insurance death benefit is large enough, the estate is close enough to a federal or state tax threshold, and the family is committed enough to the structure to justify giving up control. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The ILIT analysis lives inside the Design and Develop step, where the tax savings model collides with the personal cost of giving up the policy for good.
Related Topics Worth Reading
If an ILIT is one piece of an estate plan, several other pieces almost always come up in the same conversation.
What is estate tax portability, and how do I claim my spouse's unused exemption? covers the rule that lets a surviving spouse use any unused federal exemption from the deceased spouse, but only if a timely Form 706 is filed.
What is a SLAT, and how does spousal gifting work? looks at the spousal lifetime access trust, often evaluated alongside an ILIT for high-net-worth couples.
What is step-up in basis, and how are inherited assets taxed? explains the income tax basis story for the rest of the estate, which ILIT planning does not change.
How Does the Annual Gift Tax Exclusion Work? covers the broader menu of uses for the annual exclusion, including Crummey gifting, 529 contributions, and direct gifts.
Who should I name as my trustee? walks through how to evaluate a family member, professional fiduciary, or corporate trustee.
Maryland estate tax planning for residents focuses on how the $5 million state exemption drives the planning agenda for Maryland families.
Term, whole, or universal life insurance: what is the difference? covers the underlying policy choice. ILITs work with either, but the policy type changes the funding pattern and cost.
Frequently Asked Questions
Who needs an ILIT?
Families whose total estate, including the life insurance death benefit, exceeds either the $15 million federal estate tax exemption per person or a state estate tax exemption are the most obvious candidates. Maryland residents, with a $5 million state exemption, often qualify well below the federal threshold. Single people with sizable insurance and no spouse to use portability often benefit too.
Can I be the trustee of my own ILIT?
No, generally not. If the grantor is also the trustee, the IRS treats the grantor as holding incidents of ownership over the policy, which pulls the death benefit back into the estate under IRC §2042. Families typically name an adult child who is not a primary beneficiary, a trusted friend, or a professional fiduciary as trustee instead.
What is a Crummey letter?
A Crummey letter is a written notice the ILIT trustee sends each beneficiary every time you contribute money to the trust, telling them they have a short window, usually 30 days, to withdraw their share. The letter establishes the present-interest nature of the gift so it qualifies for the $19,000 annual gift tax exclusion in 2026.
What happens if I die within three years of transferring a policy to an ILIT?
Under IRC §2035, the death benefit of any policy you transferred into an ILIT within three years of your death is included back in your taxable estate as if you still owned it. The clock runs from the actual transfer date, not the trust signing date. This is why advisors often recommend buying a new policy directly through the ILIT instead of transferring an existing one, especially for clients over 65 or in poor health.
How much does an ILIT cost to set up?
Drafting an ILIT typically runs $2,000 to $5,000 in attorney fees, depending on complexity. Ongoing costs include annual Crummey letter administration, trust tax filings, and a corporate trustee fee if you use one. For families with significant insurance and federal or state estate tax exposure, the total cost is usually a small fraction of the projected tax savings the structure delivers.
Can I cancel or change an ILIT once it is set up?
The trust is irrevocable by definition, so you cannot unilaterally cancel it or amend its terms. Some flexibility can be built in upfront through trust protector provisions, decanting in states that permit it, or beneficiary agreement, but these options depend heavily on state law. The decision to fund the trust needs to be settled before signing, not after.
Does an ILIT make sense if my estate is under the federal exemption?
For Maryland residents, often yes. The state's $5 million estate tax exemption sits well below the federal $15 million threshold, so an ILIT can prevent Maryland estate tax even when no federal tax would apply. For residents of states with no state estate tax, the case is weaker but creditor protection and beneficiary control may still justify it.
Estate planning around life insurance is one of those decisions where the structure you choose today permanently shapes what your family receives later, for better or worse. An irrevocable life insurance trust is not the right answer for every family, but for the families who need it, the cost of getting it wrong is much higher than the cost of getting it right. Our estate planning fundamentals guide covers the broader picture, including portability, basis rules, and how life insurance fits into a full plan. Download it at chesapeakefp.com. Jeff Judge notes: "For Maryland residents especially, an ILIT is worth a serious look even when no federal estate tax applies, because a $5 million state exemption at a 16% top rate can create a real tax bill for families who never imagined they had an estate tax problem."
Want to go deeper? Our Busy Professional's Guide to Making Financial Progress walks through this step by step.
This material is for educational purposes only and should not be considered tax or legal advice. Please consult with your tax advisor or attorney regarding your specific situation.
The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
All investing involves risk including loss of principal. No strategy assures success or protects against loss.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
The ChFC® is the property of The American College of Financial Services, which reserves sole rights to its use, and is used by permission.
The CLU® is the property of The American College of Financial Services, which reserves sole rights to its use, and is used by permission.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


