
How Can I Donate From My IRA Tax-Free?
Last reviewed: July 2026
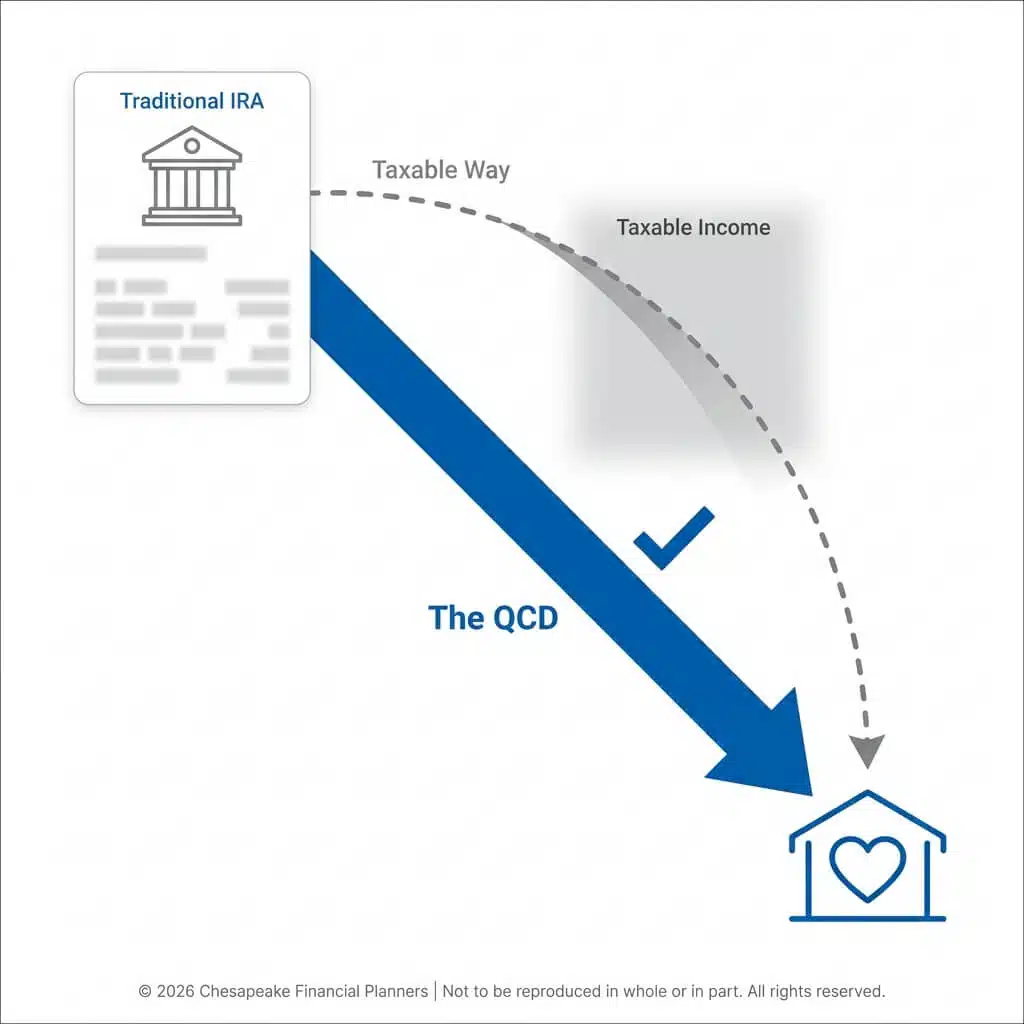
You can donate directly from your IRA to charity, satisfy your required minimum distribution, and pay zero income tax on the transfer. This move is called a qualified charitable distribution, or QCD. The money goes straight from your IRA custodian to a qualified charity, never touches your tax return as income, and counts toward your RMD for the year. For retirees who give and don't itemize, it is usually the single most tax-efficient way to support a cause they care about.
Key Takeaways
- A qualified charitable distribution lets IRA owners age 70½ or older send money straight to charity with no income tax owed.
- For 2026, the IRS caps QCDs at $111,000 per person per year, indexed annually for inflation.
- A QCD counts toward your RMD and is excluded from income, which can lower Medicare premiums and Social Security taxation.
- The check must go directly to the charity; if it is made out to you first, it stops being a QCD.
- Donor-advised funds and private foundations do not qualify as QCD recipients.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement income and charitable giving decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the biggest QCD mistake isn't the strategy itself, it's people who already mailed the charity a personal check and only later learn they gave up the tax break.
What Is a Qualified Charitable Distribution?
A qualified charitable distribution is a direct transfer of funds from your IRA custodian to a qualified charity that is excluded from your taxable income. For 2026, you can give up to $111,000 per person per year through QCDs, a figure the IRS now indexes for inflation each year. A married couple with separate IRAs can each give up to that amount.
Here is why it beats a normal donation for most retirees. When you take an ordinary distribution from a traditional IRA, that money is added to your taxable income, and you owe income tax on it. With a QCD, the money skips your tax return entirely. You don't claim a charitable deduction, but you also never report the income in the first place. For people who take the standard deduction rather than itemizing, that is almost always the better outcome.
The strategy fits the way our firm thinks about retirement income. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. QCDs usually surface during the Design and Develop stage, when we map out where each dollar of retirement income comes from and what it costs in tax.
Who Qualifies to Make a QCD?
You must be at least 70½ years old on the day the distribution is made. That age has not moved, even though the RMD age has. People born between 1951 and 1959 hit RMD age at 73, and those born in 1960 or later wait until 75. So there is a window where you can do QCDs at 70½ but aren't yet required to take RMDs, which is a smart way to start shrinking a large IRA early.
The account also matters. QCDs can come from traditional IRAs and inherited IRAs. SEP and SIMPLE IRAs only qualify if they are inactive, meaning you are no longer receiving employer contributions. Roth IRAs technically qualify, but since Roth withdrawals are already tax-free, there is no reason to use one for a QCD.
The recipient has to be a public 501(c)(3) charity eligible to receive tax-deductible gifts. This trips people up: donor-advised funds, private foundations, and supporting organizations do not qualify. If giving to a fund is part of your plan, How does a donor-advised fund work and who should consider using one? is a separate strategy worth understanding alongside QCDs.
How Do QCDs Lower Your Taxes?
A QCD does two things at once. It satisfies your RMD and it keeps that money out of your adjusted gross income. Because QCDs are excluded from income rather than deducted, they lower your AGI, and a lower AGI ripples through your whole tax picture.
| Tax exposure | How a QCD helps |
|---|---|
| Medicare IRMAA surcharges | Lower AGI can keep you under the income brackets that trigger higher Part B and Part D premiums. |
| Social Security taxation | Up to 85% of benefits can be taxed based on income; a lower AGI can shrink that taxable share. |
| Net Investment Income Tax | The 3.8% NIIT applies above modified AGI of $200,000 single or $250,000 married filing jointly; QCDs help keep you under. |
| State income tax | In states with an income tax, a lower AGI lowers state liability too. |
Compare this to the alternative. If you take the RMD as income and then write the charity a check, you report the full distribution as taxable income and can only claim a deduction if you itemize. For 2026, you would have to clear a standard deduction of $16,100 for single filers or $32,200 for married couples filing jointly before itemizing buys you anything. Most retirees don't get there, which is exactly why the QCD wins. With a QCD you get the tax benefit whether you itemize or not.
A quick example. Say your RMD is $15,000 and you direct a $10,000 QCD to your church. The $10,000 never hits your income, and you still take the remaining $5,000 as a taxable RMD. At a 22% bracket, that QCD just saved you roughly $2,200 versus taking the full RMD and donating after tax with no itemized benefit.
How Do You Actually Execute a QCD?
Start by calling your IRA custodian, whether that is Fidelity, Vanguard, or Schwab. Some have a dedicated QCD form; others process it as a standard distribution with the check made payable to the charity. Either way, the instruction has to be clear that the check goes to the charity, not to you.
You'll need the charity's legal name and mailing address, plus your own donor information so the organization knows who the gift is from. Then keep your paper trail: a confirmation from your custodian showing the distribution and a written acknowledgment from the charity. Report the QCD correctly on your tax return so it shows as a nontaxable distribution, because the 1099-R from your custodian will not separate it out for you.
The one rule that ruins QCDs: the check cannot be made out to you. Jeff has watched clients receive the distribution check in their own name, forward it to the charity untouched, and still lose the tax break entirely. The custodian has to pay the charity directly. Get that part right and the rest is straightforward. For broader tax planning around giving, How Can Bunching Charitable Deductions Save Me on Taxes? and How can I potentially optimize my taxes as my income grows? pair well with a QCD strategy.
Frequently Asked Questions
What is the maximum QCD allowed in 2026?
The maximum qualified charitable distribution for 2026 is $111,000 per person, according to the IRS, and the figure is indexed for inflation each year. A married couple who each own an IRA can each give up to that amount, for a combined ceiling above $222,000 in a single year if both have the assets and the charitable intent.
Can a QCD satisfy my required minimum distribution?
Yes, a qualified charitable distribution counts toward your required minimum distribution for the year. If your RMD is $20,000 and you make a $12,000 QCD, you have satisfied $12,000 of the requirement and only owe tax on the remaining $8,000 you take as a normal distribution. The QCD portion is excluded from income.
Do I get a charitable deduction for a QCD?
No, you do not claim a separate charitable deduction for a QCD, and that is the point. Instead of deducting the gift, the distribution is simply excluded from your taxable income. This is better than a deduction for most retirees, because you get the tax benefit even if you take the standard deduction rather than itemizing.
Can I make a QCD to a donor-advised fund?
No, donor-advised funds do not qualify to receive QCDs, and neither do private foundations or supporting organizations. The recipient must be a public 501(c)(3) charity eligible for tax-deductible contributions. If you want to fund a donor-advised fund, you do that with other assets, while reserving QCDs for direct gifts to operating charities.
At what age can I start making QCDs?
You can make a qualified charitable distribution starting at age 70½, the day you reach that age, not the year. This is earlier than the RMD start age of 73 or 75, depending on your birth year. That gap creates a planning window to shrink a large traditional IRA through tax-free giving before required distributions ever begin.
Does a QCD lower my Medicare premiums?
A QCD can help lower or avoid Medicare IRMAA surcharges because it keeps that distribution out of your adjusted gross income. Medicare Part B and Part D premiums climb at higher income brackets, so excluding a five-figure distribution from AGI may keep you below a surcharge threshold and save thousands in premiums.
Ready to Put a Plan Around Your Charitable Giving?
A qualified charitable distribution is simple in concept and easy to fumble in execution, and the cost of a single mistake is your entire tax benefit. If you want to see how QCDs fit alongside your RMDs, your Medicare premiums, and the rest of your retirement income, our team can help you map it out. Visit chesapeakefp.com to download our retirement income planning guide and learn how tax-free giving could lower your bill this year.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


