
How Can High Net Worth Individuals Reduce Estate Taxes?
Last reviewed: July 2026
High net worth individuals reduce estate taxes through estate tax planning that moves appreciating assets out of the taxable estate during life. The core tools are lifetime gifting, irrevocable trusts, valuation discounts, and charitable structures. Even with a historically high federal exemption, the 40% top rate and low state thresholds make this work matter. Estate tax planning is the process of structuring how wealth transfers at death so heirs keep more and the government takes less.
Key Takeaways
- The federal estate tax exemption is permanently set at $15 million per individual ($30 million per couple) for 2026, indexed for inflation starting 2027.
- Estates above the exemption face a 40% federal tax rate, so moving appreciating assets out early protects future growth.
- Some states tax estates as low as $1 million, meaning federally exempt estates can still owe state tax.
- Irrevocable trusts, lifetime gifting, and valuation discounts remain the workhorses of high net worth estate planning.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate tax planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often reminds clients that the biggest estate tax mistake is waiting until the exemption is about to change to act, because the best assets to move are the ones that haven't appreciated yet.
What Is the Current Estate Tax Exemption for 2026?
The 2026 federal estate tax exemption is $15 million per individual, or $30 million for a married couple with proper planning. This amount was made permanent by the One Big Beautiful Bill Act signed in 2025, ending years of uncertainty about whether the exemption would be cut roughly in half. Beginning in 2027, the figure is indexed annually for inflation.
Estates above the exemption pay a 40% federal tax on the excess. On a $30 million estate held by an individual with no planning, the taxable amount above $15 million is $15 million, which produces a $6 million federal bill. That number alone explains why high net worth families plan ahead.
The federal exemption is high right now, but that does not mean planning is finished. Tax law changes with each administration, many estates already exceed even the new threshold once business interests and real estate are counted, and state taxes apply at far lower levels. Some states impose estate or inheritance taxes starting around $1 million. The IRS maintains the federal rules, but state exposure has to be measured separately.
How Does Lifetime Gifting Reduce Estate Taxes?
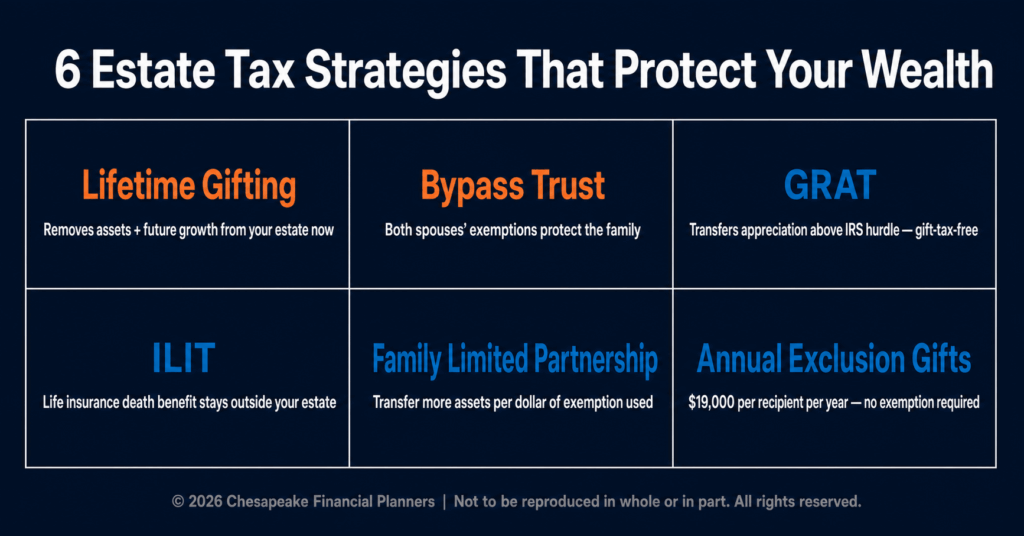
Lifetime gifting reduces estate taxes by removing assets, and all of their future appreciation, from your taxable estate before you die. Every dollar you gift using your exemption is a dollar that escapes the 40% rate, along with whatever that dollar grows into. This is the single most direct lever in estate tax planning.
The power comes from timing. Gift $5 million of stock that doubles over a decade and you have removed $10 million from your estate while using only $5 million of exemption. The appreciation lands in your heirs' hands, not in the taxable column. The IRS has confirmed that gifts made under earlier higher exemptions will not be clawed back, which gives families confidence to act.
Each spouse holds a separate exemption, so a couple can move up to $30 million in 2026. There is also an annual gift exclusion of $19,000 per recipient for 2026, which lets you transfer wealth every year without touching your lifetime exemption at all. Used consistently across children and grandchildren, that adds up fast. For high earners exploring complementary tax moves, see How can I potentially optimize my taxes as my income grows?.
Jeff Judge has watched clients hesitate on lifetime gifting because they fear losing control or access to the money. His framework is simple: gift the assets you are confident you will never need, prioritize the ones most likely to grow, and keep enough liquid wealth that the gift never becomes a regret.
What Trusts Help Reduce Estate Taxes?
Several irrevocable trusts move appreciating assets out of your estate while letting you keep some benefit during life. The right one depends on the asset, your time horizon, and how much control you want to retain. Below are the structures high net worth families use most.
| Trust Type | Best For | Core Benefit |
|---|---|---|
| Grantor retained annuity trust (GRAT) | High-growth stock or business interests | Transfers appreciation above the IRS hurdle rate gift-tax-free |
| Irrevocable life insurance trust (ILIT) | Large life insurance policies | Keeps death benefit out of the taxable estate |
| Qualified personal residence trust (QPRT) | Valuable primary or vacation homes | Transfers the home at a reduced gift value |
| Charitable lead trust | Families with philanthropic goals | Cuts gift or estate tax on transfers to heirs |
A grantor retained annuity trust lets you transfer assets while retaining fixed annuity payments for a set term. If the assets grow faster than the IRS-assumed return, the excess passes to your beneficiaries gift-tax-free. Many families run serial GRATs, several shorter-term trusts in sequence, to limit the risk that they die during a single long term and pull assets back into the estate.
An irrevocable life insurance trust owns your life insurance so the death benefit is not counted in your estate. A $10 million policy owned personally adds $10 million to your taxable estate; owned by an ILIT, it stays out, protecting roughly $4 million in tax. ILITs require disciplined administration, including the withdrawal notices beneficiaries must receive when you fund premiums.
A qualified personal residence trust moves a home to heirs at a discounted gift value because you retain the right to live there for a term. After the term ends, the home and all its appreciation belong to your beneficiaries, and you can keep living there by paying fair market rent. For families also weighing the foundational documents, review What is a will and do I need one for my estate? and What Is a Financial Power of Attorney and Why Do I Need One?.
How Do Valuation Discounts Work for Estate Planning?
Valuation discounts let you transfer more wealth per dollar of exemption by gifting interests in an entity rather than the underlying assets directly. A family limited partnership or LLC holds the assets, and you gift limited interests that carry no control and cannot be easily sold. Those limitations lower the appraised value.
Discounts commonly run 20% to 40% depending on the structure and the asset. A 30% discount means $1.4 million of assets can be transferred while using only roughly $1 million of exemption. Family limited partnerships work well for real estate, closely held businesses, and marketable securities, and they centralize management across generations.
These structures draw heavy IRS scrutiny. They need a genuine business purpose beyond tax savings, proper legal formalities, and real economic substance. Poorly run partnerships invite challenges that strip the discounts entirely. For business owners thinking about long-term family structure, see How do you create a family wealth governance structure for long-term success?.
How Does Charitable Giving Reduce Estate Taxes?
Charitable giving reduces estate taxes dollar-for-dollar because amounts left to qualified charities are deducted from the taxable estate. For families already facing a 40% rate, blending charitable gifts with transfers to heirs is often more efficient than leaving everything to children. A charitable lead trust pays income to charity for a term and passes the remainder to family, cutting the gift or estate tax on that transfer.
Charitable remainder trusts flip the order, paying income to you or your family first with the remainder going to charity, and they generate a current deduction for the charitable portion. Private foundations and donor-advised funds keep the family engaged in giving across generations. To compare giving vehicles, see How do donor-advised funds work for charitable giving and taxes? and How Can I Donate From My IRA Tax-Free?.
This is where the R.U.D.D.E.R. Method™ earns its place. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Charitable and estate strategies that look good on paper often need the Reassess and Refine step as tax law and family circumstances shift.
Frequently Asked Questions
What is the estate tax exemption for 2026?
The 2026 federal estate tax exemption is $15 million per individual and $30 million per married couple, made permanent by the One Big Beautiful Bill Act. Estates above that amount pay a 40% federal tax on the excess. Starting in 2027, the exemption is indexed annually for inflation.
Do I still need estate planning if my estate is under the federal exemption?
Yes, because state estate and inheritance taxes often apply at much lower thresholds than the federal exemption. Some states tax estates starting around $1 million, so a family that owes nothing federally can still face a meaningful state bill. Estate planning also handles non-tax goals like control and asset protection.
What is the most powerful estate tax reduction strategy?
Lifetime gifting of appreciating assets is usually the most powerful single strategy. Removing an asset before it grows pulls both the asset and all its future appreciation out of your taxable estate. Gifting $5 million of stock that later doubles removes $10 million while using only $5 million of exemption.
How does an irrevocable life insurance trust save estate taxes?
An irrevocable life insurance trust owns your policy so the death benefit is excluded from your taxable estate. Owned personally, a $10 million policy adds $10 million to your estate; owned by the trust, it stays out, protecting roughly $4 million in tax. The trust requires careful funding and beneficiary withdrawal notices.
Are valuation discounts on family limited partnerships still allowed?
Yes, valuation discounts of 20% to 40% on family limited partnership interests remain available, but the IRS scrutinizes these structures closely. They require a genuine business purpose, proper legal formalities, and real economic substance. Partnerships created solely to discount gifts and lacking substance can have their discounts disallowed on audit.
Will gifts made under the higher exemption be clawed back later?
No, the IRS has confirmed that gifts made under higher exemption amounts will not be clawed back if the exemption later falls. This anti-clawback rule lets families use the current high exemption with confidence. It is one reason advisors encourage moving wealth while the exemption stands at its permanent $15 million level.
If you found this helpful, our estate planning guide for high net worth families covers gifting, trusts, and charitable structures in depth. Download it at chesapeakefp.com to see how these strategies fit together for your situation.
Want to go deeper? Our Busy Professional's Guide to Making Financial Progress walks through this step by step.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


