

What Is a Financial Power of Attorney and Why Do I Need One?
Last reviewed: July 2026
A financial power of attorney is a legal document that lets you name someone to make money decisions on your behalf if you cannot make them yourself. That person, called your agent or attorney-in-fact, can pay your bills, manage your accounts, and handle financial matters when illness or injury takes you out of the driver's seat. Without one, your family may have to ask a court for control, and a judge decides who gets it. Setting up a financial power of attorney is one of the cheapest, fastest ways to protect yourself and the people you love.
Key Takeaways
- A financial power of attorney names an agent to manage your money if you become incapacitated.
- A durable power of attorney stays valid through incapacity; a standard one does not.
- Without this document, your family may face a court guardianship process that can take months.
- Roughly two-thirds of U.S. adults have no estate planning documents at all, according to Caring.com.
- Choosing the right agent matters more than the legal form itself.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate incapacity planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched families spend thousands on guardianship petitions that a single signed document would have prevented entirely.
What Is a Financial Power of Attorney?
A financial power of attorney is a legal document that authorizes a person you choose to make financial decisions and take actions on your behalf. The person you name is called your agent or attorney-in-fact. You stay in control of your own finances for as long as you are able. Your agent steps in only when you cannot act for yourself.
Your agent's authority can be broad or narrow, depending on what you put in the document. According to the Consumer Financial Protection Bureau, an agent under a financial power of attorney has a legal duty to act in your best interest and keep your money separate from their own.
Common powers people grant include:
- Managing bank and investment accounts
- Paying bills and handling everyday expenses
- Filing tax returns
- Buying, selling, or managing real estate
- Operating a business
- Accessing a safe deposit box
- Managing insurance policies and retirement accounts
You decide how much authority to hand over. A financial power of attorney is a core piece of the estate planning documents every adult should have, alongside a will and a health care directive.
What Are the Types of Financial Power of Attorney?
Not every financial power of attorney works the same way. The type you choose determines when your agent can act and whether the document survives your incapacity. Picking the wrong type is one of the most common and costly mistakes in incapacity planning.
| Type | When it takes effect | Survives incapacity? | Best use |
|---|---|---|---|
| Standard (non-durable) | When signed | No | Temporary, specific tasks |
| Durable | When signed | Yes | Long-term planning for most people |
| Springing | On a triggering event | Yes | Those who delay agent authority |
| Immediate | When signed | Depends on language | Maximum flexibility with high trust |
A standard, or non-durable, power of attorney ends the moment you become incapacitated. That is exactly when most people assume it would help, which makes it the wrong tool for incapacity planning. Standard versions work for short, specific jobs, like letting someone close on a house while you travel.
A durable power of attorney stays valid even after you lose capacity. As legal publisher Nolo explains, the word durable means the document endures through your incapacity. This is the version most families actually need.
A springing power of attorney only activates after a triggering event, usually a doctor certifying that you cannot manage your affairs. It sounds safe, but banks often demand heavy medical proof before they honor it, which creates delays right when speed matters. Jeff Judge often steers clients away from springing documents for this reason. He has seen agents stuck for weeks waiting on a hospital to release paperwork while bills piled up.
How Do I Choose the Right Agent?
Choosing your agent is the single most important decision in a financial power of attorney, and it carries more weight than the form itself. This person will hold legal authority over your accounts, so trustworthiness and judgment outrank financial expertise every time.
Look for these qualities in an agent:
- Trustworthiness. Your agent can move money, sell assets, and make binding decisions. Pick someone with unquestionable integrity.
- Financial competence. They do not need to be an expert, but they should handle their own money responsibly and stay organized.
- Availability. Someone who travels constantly or lives far away may struggle to act quickly.
- Good judgment. Choose a person who stays calm under pressure and honors your wishes even when they disagree.
- No conflicts of interest. Be careful naming an agent who personally benefits from the decisions they would make for you.
Spouses, adult children, siblings, and trusted friends are the usual choices. You can also hire a professional fiduciary, such as a trust company, for a fee. Naming co-agents who act jointly can reduce family conflict but may slow decisions, since both must agree. Always name a successor agent in case your first choice cannot serve.
This decision sits at the heart of any solid incapacity planning conversation. Reviewing your agent choice is also part of the Reassess and Refine step of the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Jeff Judge notes: "We revisit agent designations regularly with clients because the person who was the obvious choice ten years ago may no longer be the right fit given changes in health, geography, or family dynamics."
When Do I Need a Financial Power of Attorney?
You need a financial power of attorney now, not later, because incapacity rarely announces itself in advance. A power of attorney must be signed while you have full mental capacity, so waiting until a crisis hits often means waiting too long. Certain life events make the need urgent.
A serious health diagnosis is a clear signal to act while you are still clearly capable. Major financial decision making moments also matter, such as buying a business, handling an inheritance, or starting retirement. Divorce is one of the most overlooked triggers. If your former spouse is still named as your agent, they may retain control over your money long after the marriage ends. Updating beneficiary designations and your power of attorney should happen together during any separation.
The National Institute on Aging notes that advance planning documents work best when completed before a health emergency, not during one. Jeff Judge tells clients that the cheapest version of this document is the one you sign while you are healthy. The most expensive version is the court process you trigger by not having it.
What Happens If I Don't Have a Financial Power of Attorney?
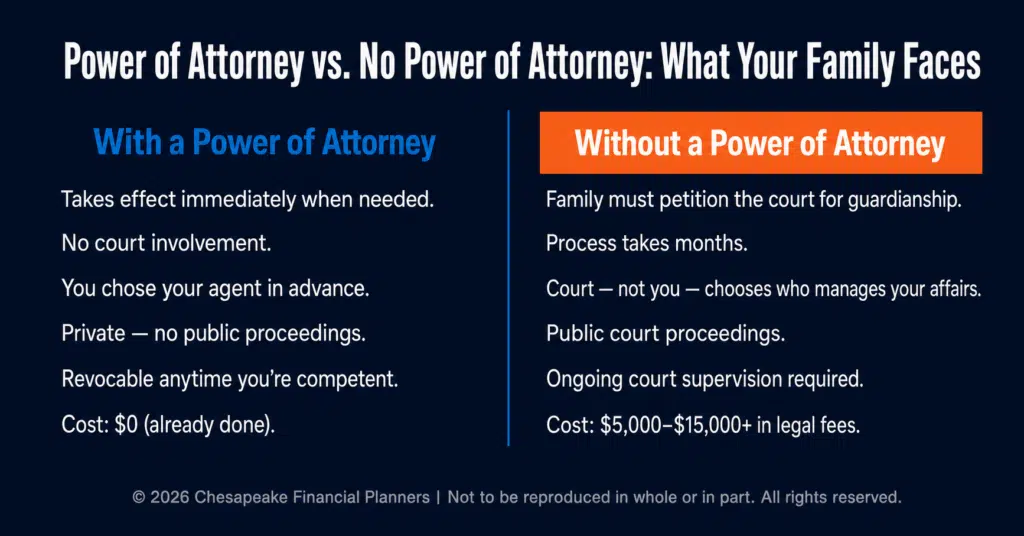
Without a financial power of attorney, your family may have to petition a court for guardianship or conservatorship if you become incapacitated. That process is public, expensive, and slow. A judge, not you, decides who controls your money. According to the American Bar Association, guardianship proceedings can stretch on for months and involve ongoing court supervision.
During that limbo, bills can go unpaid, accounts can freeze, and investment decisions stall. Your family absorbs added stress and legal fees at the worst possible time. A signed power of attorney prevents all of it by establishing clear authority before any crisis arrives. For most people, it is the cheapest insurance policy in their entire estate plan.
Frequently Asked Questions
What is the difference between a durable and non-durable power of attorney?
A durable power of attorney stays valid even after you become incapacitated, while a non-durable one ends the moment you lose capacity. Most people need a durable version because the whole point of incapacity planning is to cover the period when you cannot act for yourself.
Can a financial power of attorney be revoked?
Yes, you can revoke a financial power of attorney at any time as long as you remain mentally competent. You revoke it in writing, notify your agent, and inform any banks or institutions that relied on it. Many people update their document after a divorce, a move, or a change in their chosen agent.
Does a financial power of attorney cover medical decisions?
No, a financial power of attorney covers only money and property matters, not health care choices. For medical decisions you need a separate document, often called a health care power of attorney or advance directive. Most complete estate plans include both so every type of decision is covered.
When does a financial power of attorney take effect?
It depends on the type you choose. An immediate or durable power of attorney can take effect as soon as you sign it. A springing power of attorney activates only after a triggering event, usually a doctor certifying you can no longer manage your own affairs, which can cause delays at financial institutions.
Do I need a lawyer to create a financial power of attorney?
You are not legally required to use a lawyer, but professional guidance helps you avoid costly mistakes in agent selection and document language. Banks sometimes reject poorly drafted forms, so working with an estate planning attorney and your financial advisor improves the odds the document actually works when needed.
If you want to keep your estate planning documents organized and current, our free estate planning checklist walks you through every document your family should have in place, including powers of attorney. Download it at chesapeakefp.com and take the first step toward protecting the people who depend on you.
What is a will and do I need one for my estate?
Do I need to update my beneficiary designations after a divorce or major life change?
How Do I Protect My Children's Inheritance in a Blended Family?
Want to go deeper? Our Estate Document Locator walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


