
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Part of our guide: Donor-advised fund, private foundation, or QCD: which giving strategy fits me?
A donor advised fundA charitable giving account where you make a tax-deductible contribution, invest the assets for potential tax-free growth, and distribute grants to charities over time on your own schedule. It's one of the most flexible and tax-efficient ways to structure charitable giving, especially in high-income years. is a charitable giving account at a sponsoring 501(c)(3) public charity that lets you take the full tax deduction the year you contribute, then recommend grants to qualified charities on your own timeline. The cash, stock, or other assets you put in are irrevocably committed to charity, the assets can grow tax-free inside the account, and you decide later which charities receive the money. For households that give regularly, especially in a high-income year or with concentrated appreciated stock, a donor advised fund is one of the cleanest tools the tax code offers.
Key Takeaways
- A donor advised fund lets you claim the charitable deduction the year you contribute, then grant the money to charities over any timeframe you choose.
- Cash gifts to a DAF are deductible up to 60% of AGI; appreciated long-term securities up to 30%. Unused amounts carry forward five years.
- Starting in 2026, itemized charitable deductions face a new 0.5% AGI floor, and top-bracket donors are capped at a 35% benefit rate.
- Charitable bunching through a DAF is the cleanest way to clear the $32,200 MFJ standard deduction in 2026.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate charitable giving and tax-efficient wealth transfer since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched donor advised funds go from a niche tool used by foundation-sized donors to a default recommendation for any household that gives more than a few thousand dollars a year.
What is a donor advised fund and how does it actually work?
A donor advised fund is a charitable account, not a separate legal entity. You open it at a sponsoring organization like Fidelity Charitable, Schwab Charitable, Vanguard Charitable, or a community foundation. The sponsor is the 501(c)(3) of record, which is why your contribution is deductible the moment it lands in the account.
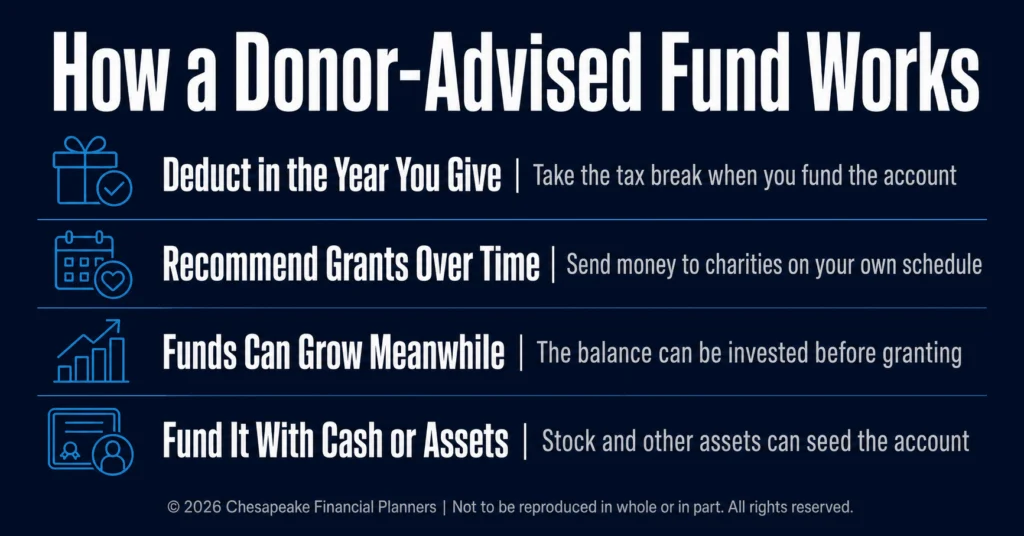
Here's the flow most clients use. You make an irrevocable contribution of cash, publicly traded stock, mutual funds, or sometimes real estate or private business interests. You claim the deduction for that tax year. The assets sit inside the DAF, invested in one of the sponsor's portfolios, and any growth happens tax-free because the account belongs to a public charity. When you want to give, you log in and recommend a grant to a qualified 501(c)(3). The sponsor reviews the recommendation and issues the check.
Two design points matter most. First, your contribution is irrevocable. Once the money is in, you cannot pull it back out for personal use. Second, your grant recommendations are non-binding from a legal standpoint. The sponsoring charity has final authority over distributions, although in practice they approve virtually every grant to a qualifying public charity.
The combination is what makes DAFs flexible. You separate the timing of the deduction from the timing of the gifts. Take the deduction in a high-income year. Spread the grants over a decade if you want.
Donor-advised funds held about $328 billion in charitable assets in fiscal year 2024, according to the Donor Advised Fund Research Collaborative, which shows how mainstream the tool has become.
How does a donor advised fund save you on taxes?
A donor advised fund saves you taxes in three distinct ways. Each one matters independently, and most donors stack at least two.
The income tax deduction is the first. Cash contributions to a DAF are deductible up to 60% of your adjusted gross income in the year you contribute, per the rules made permanent under the One Big Beautiful Bill Act. Long-term appreciated securities are deductible up to 30% of AGI based on fair market value. Excess contributions carry forward for five years. For a household with $400,000 of AGI, the cash deduction ceiling is $240,000 and the appreciated stock ceiling is $120,000. Most clients never test those limits with normal annual giving, but a one-year DAF lump-sum contribution often does.
Capital gainsThe profit you make when you sell an asset for more than you paid for it. Short-term gains (assets held less than a year) are taxed at your ordinary income rate; long-term gains (held more than a year) qualify for preferential rates of 0%, 15%, or 20% — a meaningful difference that shapes many investment decisions. avoidance on appreciated stock is the lever clients underuse most. When you donate long-term appreciated stock directly to a DAF, you deduct the full fair market value and avoid the capital gains tax you would have paid by selling first and donating cash. Concentrated positions, RSURestricted Stock Unit — a grant of company shares that vest on a set schedule, at which point their full market value is taxed as ordinary income. Since you often can't control the timing of vesting, planning around RSU events in advance is an important part of managing taxes at a public company. vesting events, and company stock from a sale are the natural candidates. A $50,000 position with a $10,000 cost basis donated through a DAF skips roughly $9,520 of long-term federal capital gains tax (20% top rate plus the 3.8% net investment income tax, depending on income).
Tax-free growth inside the account is the third. Once contributed, the assets grow free of capital gains and dividendA cash payment distributed to shareholders from a portion of a company's earnings, typically paid quarterly. Dividends provide income without requiring you to sell shares, making them particularly appealing for retirees and income-focused investors. tax. A $100,000 DAF contribution at 7% growth becomes roughly $140,000 over five years of granting, with all of it going to charity instead of to the IRS on the way through.
Two compliance details to keep clean. Contributions of $250 or more require a contemporaneous written acknowledgment from the sponsor under IRC §170(f)(8). DAF sponsors handle this automatically. And starting in 2026, the new 0.5% AGI charitable floor means itemizers do not deduct the first slice of their charitable giving. If your AGI is $300,000, the first $1,500 of charitable deductions are lost. Disallowed amounts under the floor do not carry forward.
Why are donor-advised funds useful in an income-spike year?
A DAF separates the tax deduction from the act of giving, which solves a timing problem that retirement income and windfalls create. A bonus year, a business sale, a Roth conversionMoving money from a traditional pre-tax IRA to a Roth IRA, paying income taxes now in exchange for tax-free growth and withdrawals in the future. Conversions make the most sense when your current tax rate is lower than what you expect in the future — making the years between retirement and RMD age a prime window for strategic action., or a large IRA distribution can spike your income and your tax bill. Funding a DAF that year captures the deduction when it helps most.
Required minimum distributions generally begin at age 73 (75 for those born in 1960 or later), according to the IRS. A qualified charitable distribution must go straight to a charity and cannot fund a DAF, but the two strategies can sit side by side in one plan: a DAF for appreciated stock and a qualified charitable distribution from an IRA for the RMD itself.
Two more common uses are year-end planning and legacy planning. If you face a higher-than-expected tax bill in December, a contribution before year-end lowers that year's taxable income. You can also name the DAF as a beneficiary of an IRA or other retirement account. Because charities pay no income tax, this routes pre-tax retirement dollars to charity without the income tax that would hit non-charitable heirs, a point worth coordinating with your estate planning and beneficiary designations.
What does donating appreciated stock look like in numbers?
Consider a position you bought for $50,000 that is now worth $150,000. If you sell it, you owe federal long-term capital gains tax (15% or 20% depending on income, plus the 3.8% net investment income tax for higher earners) on the $100,000 gain. If you donate the shares to the DAF instead, you skip that bill and deduct $150,000, subject to the income-based limits on charitable deductions. Growth then compounds inside the fund with no tax on the gain: if you contribute $100,000 and it were to grow to $150,000 over several years, the full $150,000 would be available for grants.
Hypothetical example for illustration only. It assumes the shares were held more than one year, ignores state tax, and assumes investment growth that is not guaranteed.
DAF or private foundation: which one fits your situation?
For households planning to give six or seven figures over the next decade, the question of donor advised fund versus private foundation comes up early. Both are charitable vehicles. Both involve giving up control of the assets. The mechanics are different enough that the answer is almost always one or the other, not both.
| Feature | Donor-Advised Fund | Private Foundation |
|---|---|---|
| Setup cost | Free or minimal | $5,000 to $25,000+ in legal fees |
| Minimum to open | Often $0 to $25,000 | Typically $1M+ to justify costs |
| Annual administrative cost | Sponsor fee, usually 0.6% to 0.85% of assets | 1% to 2.5% all-in (excise tax, legal, accounting) |
| Cash deduction limit | 60% of AGI | 30% of AGI |
| Appreciated stock deduction | Full fair market value, up to 30% of AGI | Often limited to basis for non-publicly-traded stock; 20% of AGI |
| Annual distribution requirement | None imposed by the IRS on individual donors | 5% of net asset value required annually |
| Public reporting | Anonymous; donor identity confidential | Form 990-PF public; donations and grants disclosed |
| Hiring family members | Not permitted | Permitted with reasonable compensation |
| Investment control | Limited to sponsor's portfolio options | Donor controls investments directly |
In practice, donor advised funds win on cost, deduction limits, anonymity, and administrative simplicity. Private foundations win when the family wants direct investment control, plans to employ family members, wants the public profile that comes with a named foundation, or expects the assets to span generations of granular family governance. For the typical Chesapeake client giving $50,000 to $500,000 a year, a DAF does what a foundation would do at a fraction of the cost. Our How Does a Charitable Remainder Trust Work for High Net Worth Individuals? explainer covers another vehicle worth comparing against if income for the donor or a beneficiary is also part of the picture.
A subtle point on appreciated assets. If you hold non-publicly-traded stock, private business interests, or restricted shares, foundations almost always cap your deduction at cost basis. A DAF that accepts complex assets, and several large sponsors do, lets you deduct fair market value. That gap alone can swing the decision in favor of a DAF for founders, executives with restricted stock, and business owners planning a sale.
How does a DAF compare with giving directly to charity?
The DAF vs direct giving question comes down to timing, asset type, and how much you give. Direct giving is simpler for small, regular cash gifts. A DAF fits better when you want to separate the deduction from the grant, donate appreciated assets, or bunch several years of giving into one.
| Factor | Donor-advised fund | Direct giving |
|---|---|---|
| Deduction timing | Year you contribute, grant later | Year you give to the charity |
| Appreciated stock | Avoids capital gains, deducts full value | Avoids gains only if the charity accepts stock |
| Bunching deductions | Built for it | Not practical across years |
| Tax-free growth | Yes | No |
| Administrative work | Sponsor handles records | You track each gift |
| Anonymity option | Yes | Limited |
Direct giving makes sense when you write a $200 check to a local cause every year. A DAF makes sense when you have a $250,000 income spike, a concentrated stock position, or a desire to involve your children in family giving over time. These amounts are illustrations, not data.
How does charitable bunching work with a donor advised fund?
Charitable bunching is the deliberate strategy of bundling two, three, or four years of normal charitable giving into a single tax year so you can itemize that year and take the standard deduction in the off-years. The math depends on three numbers: the 2026 standard deduction of $32,200 for married filing jointly, your other itemizable deductions (state and local taxes capped at $40,000 under OBBBA, mortgage interest, and so on), and your normal annual charitable giving.
Here's the mechanism. A married couple gives $15,000 a year to their church and a handful of nonprofits. Their other itemizable deductions add up to $25,000 a year. Each year, their total itemized deductions are $40,000, which beats the standard deduction by $7,800. They get a real deduction benefit on only that incremental amount.
If that same couple opens a DAF and contributes $45,000 in 2026, then $0 in 2027 and 2028, the math changes. In 2026, itemized deductions are $70,000, which is $37,800 above the standard deduction. In 2027 and 2028, they take the $32,200 standard deduction. Over three years, the bunched approach delivers roughly $30,000 more in deductions than the year-by-year approach. Their actual giving did not change. They still grant $15,000 from the DAF each year to the same charities.
The new OBBBA rules make bunching more important, not less. The 0.5% AGI floor and the 35% benefit cap for top-bracket itemizers both reward concentrating deductions in fewer years. A donor in the 37% bracket who gives $20,000 a year in 2026 and 2027 takes less benefit than a donor who bunches $40,000 into 2026 and clears the floor once instead of twice.
This is the kind of decision that maps cleanly onto our planning framework. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Charitable bunching lives in the Design and Develop step, after we have reviewed the household's tax picture and uncovered the giving pattern they already have. Jeff Judge often tells clients that bunching is the rare strategy where doing nothing different in the eyes of the charity produces a meaningfully different tax outcome.
Related topics worth reading
DAFs are one piece of a larger charitable giving toolkit. The strategies below are the ones we most often pair with them.
Should I donate appreciated stock instead of cash? covers the standalone case for using long-term appreciated securities as the funding source for any charitable gift, with or without a DAF. The deduction math and the capital gains avoidance scale the same way.
How can a qualified charitable distribution lower my RMD and taxes? is the right read for anyone age 70½ or older. QCDs cannot go to a DAF, but they can replace DAF granting for clients with large IRAs and required minimum distributions.
How does bunching charitable donations help me clear the standard deduction? is the standalone walk-through of bunching math, with worked examples across income levels.
What is step-up in basis, and how are inherited assets taxed? is worth reading in tandem with this post if you are weighing whether to give appreciated stock now or hold it for an heir to inherit at stepped-up basis.
What is a SLAT, and how does spousal gifting work? is the right read for families using their lifetime gift tax exemption and wondering how charitable giving fits alongside large family gifts.
Frequently Asked Questions
What is the difference between a donor advised fund and a private foundation?
A donor advised fund is a charitable account at a sponsoring 501(c)(3), with no setup cost, no annual distribution requirement, and a 60% AGI cash deduction limit. A private foundation is a separate legal entity that costs $5,000 or more to establish, requires 5% annual distributions, files a public Form 990-PF, and limits the cash deduction to 30% of AGI. For most family giving programs under $1 million in assets, a DAF does what a foundation would do at a fraction of the cost.
Can I take a tax deduction for the year I open a donor advised fund?
Yes. Your contribution to a donor advised fund is fully deductible in the tax year it is received by the sponsoring charity, even if no grants are made to operating charities that year. Cash is deductible up to 60% of AGI; long-term appreciated securities up to 30% of AGI at fair market value. Excess contributions carry forward for five years. The deduction does not depend on when the DAF eventually grants the money out to operating charities.
Can I contribute appreciated stock to a donor advised fund?
Yes, and this is where DAFs deliver some of their largest tax savings. When you contribute long-term appreciated publicly traded stock to a DAF, you deduct the full fair market value up to 30% of AGI and avoid the capital gains tax you would have paid by selling. The DAF sponsor sells the stock inside the account with no capital gains tax owed by either party. Many sponsors also accept complex assets like restricted stock, private business interests, and real estate.
What is charitable bunching and why does it work with a DAF?
Charitable bunching means combining several years of planned giving into a single tax year so you exceed the standard deduction and itemize that year, then take the standard deduction in the off-years. A DAF is the cleanest vehicle for bunching because you get the full deduction the year you fund the account, while still granting to charities over multiple years. The 2026 OBBBA changes, including the 0.5% AGI floor for itemizers, make bunching more valuable for households with steady annual giving below the standard deduction.
Can I make a QCD from my IRA to a donor advised fund?
No. The IRS specifically excludes donor advised funds, private foundations, and supporting organizations as eligible recipients of qualified charitable distributions from an IRA, per IRS Publication 590-B. QCDs must go directly from an IRA custodian to a qualifying public operating charity. If you are 70½ or older with a large IRA, the right structure is often a QCD for some of your annual giving and a DAF for the rest, funded with after-tax dollars or appreciated stock.
How long can the money stay in a donor advised fund before being granted?
The IRS does not impose a minimum payout requirement on individual donor advised funds. Some sponsors set their own inactivity policies, often requiring at least one grant every few years, but assets can otherwise stay invested indefinitely. Jeff Judge generally recommends granting at a sustainable pace that matches your charitable intent, not warehousing assets for decades. The National Philanthropic Trust reports DAFs distribute over 20% of assets per year on average, well above the 5% required of private foundations.
Who should consider using a donor-advised fund?
A donor-advised fund makes the most sense for high earners with variable income, anyone facing a liquidity event like a business sale or large bonus, and people holding appreciated stock they would otherwise sell. It also fits families who want to teach the next generation about giving while controlling the timing of grants over many years.
If you are planning your charitable giving for 2026 and want to see how a donor advised fund fits with the new OBBBA rules, our 2026 Charitable Giving Planning Guide walks through the bunching math, deduction limits, and account comparison side by side. Download it at chesapeakefp.com.
Want to go deeper? Our Tax-Smart Charitable Giving Playbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


