

How Do Business Owners Save for Retirement Without a 401(k)?
Last reviewed: July 2026
Business owners without a 401(k) save for retirement using a SEP IRA, a Solo 401(k), or a defined benefit plan such as a cash balance plan. These accounts carry contribution limits three to five times higher than a corporate 401(k), and a strong business owner retirement plan often combines tax-deductible saving with the eventual sale of the company. You build wealth outside the business while the business grows inside it.
Key Takeaways
- A Solo 401(k) and SEP IRA both allow up to $72,000 in total 2026 contributions, far above a corporate 401(k).
- Cash balance plans can let high earners in their 50s deduct well over $150,000 a year.
- Roughly one-third of small business owners have no retirement plan of their own, relying solely on a future sale.
- The right plan depends on your age, income, and whether you have employees.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate self-employed retirement since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same pattern constantly: owners who pour every dollar back into the business and treat "I'll sell it someday" as a retirement plan, when the tax code already offers them better tools than their employees get.
Why "Selling the Business" Isn't a Retirement Plan
Many owners treat the company itself as their nest egg. That plan has one fatal flaw: it depends on a single illiquid asset selling at the right price, at the right time, to the right buyer. According to SCORE, about one-third of small business owners have no separate retirement savings at all.
Ask the hard questions. What if the business sells for less than you hoped? What if your industry shifts and buyers disappear? What if a health event forces you out before the company is ready? Betting your entire future on one asset is the opposite of diversification, the exact principle you'd insist on for any other investment.
Jeff Judge often tells clients that the goal isn't to stop reinvesting in the business. It's to make sure that if the sale never happens the way you pictured, you still retire comfortably. A funded retirement account does that. A hopeful exit doesn't.
SEP IRA: The Simplest Self-Employed Retirement Plan
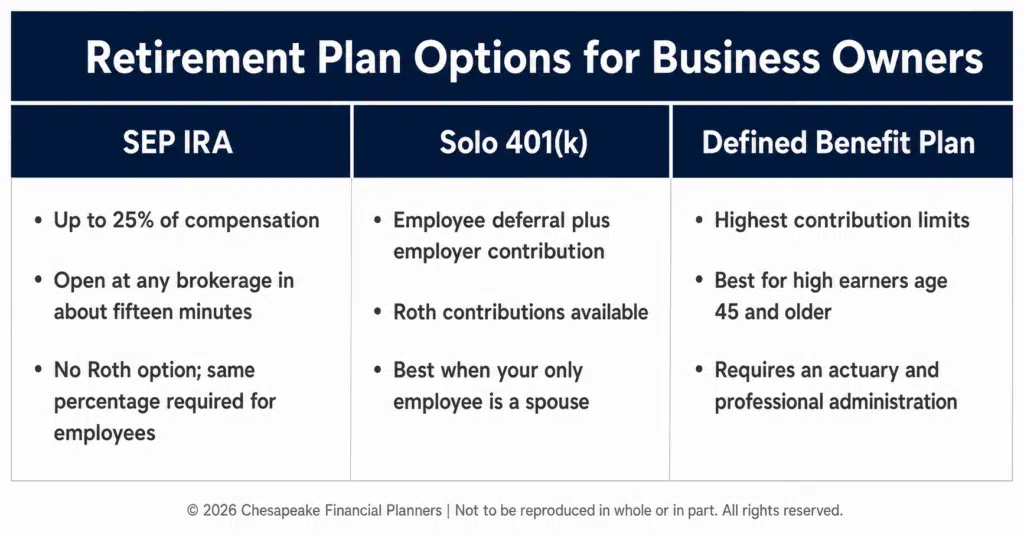
A SEP IRA (Simplified Employee Pension) lets you make tax-deductible contributions of up to 25% of compensation, with a 2026 maximum of $72,000. You can open one at almost any brokerage in about fifteen minutes, and there are no annual filing requirements until balances grow large.
The math is direct. An owner in the 35% federal bracket who contributes $60,000 saves roughly $21,000 in federal tax that year. That is real money working for you instead of going to the IRS.
The catch is employees. If you have staff who worked three of the last five years and earned at least the IRS compensation threshold, you must contribute the same percentage of pay for them as you do for yourself. With several employees, a generous contribution rate gets expensive fast. SEP IRAs work best for solo owners or those with very few employees who want maximum simplicity.
Solo 401(k): Maximum Contributions for the Self-Employed
A Solo 401(k) is the workhorse for self-employed people and owners whose only "employee" is a spouse. You contribute in two roles. As the employee, you can defer up to $24,500 in 2026. As the employer, you can add up to 25% of compensation on top. The combined cap reaches $72,000 in 2026, with higher ceilings once catch-up contributions apply.
Owners 50 and older can add an $8,000 catch-up contribution. Under SECURE 2.0, those aged 60 to 63 get an even larger "super catch-up," letting them set aside meaningfully more in those final working years. Because of the dual employee-plus-employer structure, a Solo 401(k) usually lets you contribute more than a SEP IRA at the same income level. It also supports Roth contributions for tax-free growth.
You can vary contributions year to year based on cash flow, which matters when income swings. The main administrative note: once plan assets cross $250,000, you must file an annual Form 5500. And if you hire non-spouse employees, the plan rules change.
Cash Balance and Defined Benefit Plans: The High Earner's Tool
A cash balance plan is a type of defined benefit pension that allows very large tax-deductible contributions, often $100,000 to $300,000 or more per year depending on age and income. It works best for owners 45 and older earning $250,000 or more with consistent income who want both significant tax deductions and accelerated retirement saving.
Picture a 55-year-old owner earning $400,000 who wants to catch up. A cash balance plan might permit a $200,000 contribution. In the 37% bracket, that is roughly $74,000 in federal tax savings every year. The trade-offs: contributions are largely mandatory based on actuarial calculations, you generally maintain the plan for at least three years, and you need professional administration that runs a few thousand dollars annually. For the right owner, the tax savings dwarf the fees. A cash balance plan can also be paired with a 401(k) for even larger combined contributions. Jeff Judge notes: "For an owner in the 37% bracket with consistent earnings, a cash balance plan can generate more in annual federal tax savings than most people contribute to retirement accounts in total, but it only makes sense if the cash flow is steady enough to meet the mandatory contribution schedule."
This is where a structured planning process matters. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For a high earner weighing a cash balance plan against a Solo 401(k), that framework keeps the decision tied to cash flow, age, and tax bracket rather than a sales pitch.
For a deeper comparison of the two most common starting points, see Should I Choose a Solo 401(k) or SEP IRA for My Business?. Owners thinking about how saving fits alongside an eventual sale should also read How do business owners plan for retirement differently?.
Quick Comparison of Business Owner Retirement Plans
| Plan | 2026 Max Contribution | Best For | Admin Burden |
|---|---|---|---|
| SEP IRA | Up to $72,000 | Solo owners, few employees | Very low |
| Solo 401(k) | Up to $72,000 (more with catch-up) | Self-employed, spouse-only | Low to moderate |
| Cash Balance Plan | $150,000-$300,000+ | High earners 45+ | High (actuary required) |
How you fund retirement also connects to how you pay yourself. Owners structuring contributions should review How Should Business Owners Pay Themselves Salary vs Distributions? before locking in a plan.
Frequently Asked Questions
What is the best retirement plan for a self-employed business owner?
The best plan depends on your situation. Solo owners with no employees usually choose a Solo 401(k) because its dual employee-and-employer contributions allow the largest savings at most income levels. Owners wanting simplicity often pick a SEP IRA, while high earners over 45 frequently add a cash balance plan for six-figure deductions.
How much can a business owner contribute to retirement in 2026?
A business owner can contribute up to $72,000 in 2026 through a SEP IRA or Solo 401(k), based on IRS limits. Owners 50 and older can add catch-up contributions, and those using a cash balance plan can often deduct $150,000 or more per year depending on age, income, and actuarial calculations.
Can I have a retirement plan if my business has employees?
Yes, but the plan choice changes. A SEP IRA requires you to contribute the same percentage of pay for eligible employees as you do for yourself, which raises costs. A 401(k) or profit-sharing plan can be structured to manage employee costs while still rewarding owners, so the decision depends on your headcount and budget.
Is a SEP IRA or Solo 401(k) better for one-person businesses?
A Solo 401(k) is usually better for one-person businesses because it allows both employee deferrals and employer contributions, often producing higher total savings than a SEP IRA at the same income. The Solo 401(k) also permits built-in Roth contributions, while a SEP IRA wins on pure simplicity with no annual filing until balances grow large.
Do I still need a retirement account if I plan to sell my business?
Yes. Selling your business is one illiquid asset that may not sell at the price or timing you expect. A separate retirement account diversifies your future, provides tax-deductible savings now, and protects you if the sale is delayed, falls through, or nets less than planned. Most advisors treat the sale as a bonus, not the plan.
Stop Relying on the Sale Alone
You sacrificed corporate benefits to build something of your own, and the tax code rewards that with retirement tools your employees never get. The right business owner retirement plan turns those tools into real security outside the company. If this was useful, our guide on retirement and exit planning for owners covers the next steps in depth. Download it at chesapeakefp.com.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


