
How Do Business Owners Plan for Retirement Differently?
Last reviewed: July 2026
Business owner retirement planning means building income and financial independence when your biggest asset isn't a savings account, it's the company you built. Unlike employees who lean on a company 401(k), automatic payroll deductions, and an employer match, business owners carry the full weight of retirement preparation themselves. No HR department enrolls you in anything. What you get instead is flexibility most employees never see: control over which accounts to fund, how much to contribute, when to take income, and whether a future business sale becomes the foundation of your retirement.
Key Takeaways
- Business owners fund their own retirement and must coordinate tax and retirement strategy as one decision, not two.
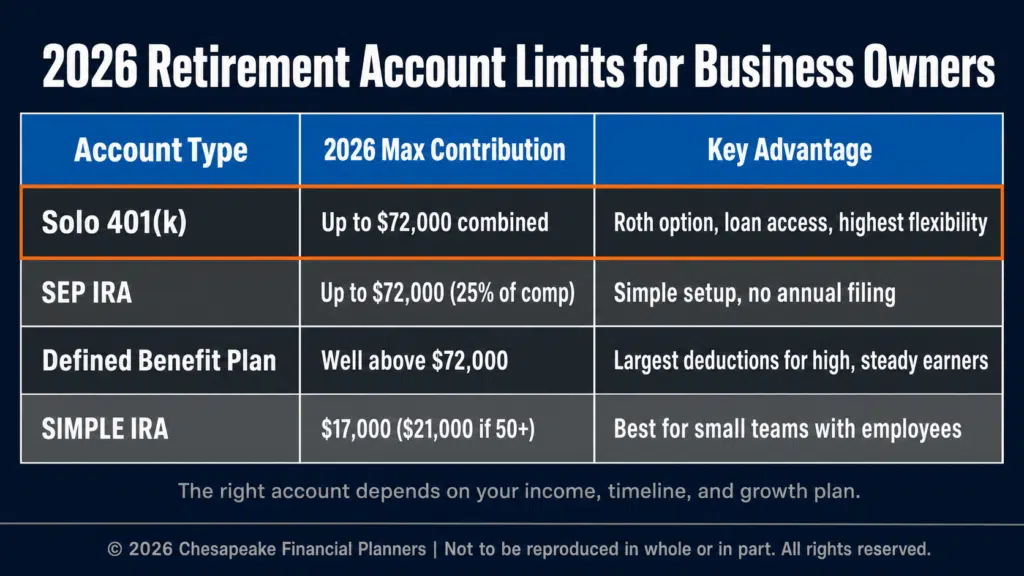
- In 2026, a Solo 401(k) allows a combined contribution of up to $72,000, far above a standard employee limit.
- For many owners the business itself is the retirement plan, which makes it powerful but dangerously illiquid and concentrated.
- Exit planning typically should begin five to seven years before a target sale date.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement and exit planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: the owners who struggle most aren't the ones who saved too little, they're the ones who never separated the value of their company from their personal retirement income plan.
The same instincts that make owners successful, reinvesting in the company, staying lean, chasing growth, can leave retirement savings critically underfunded until there's almost no runway left to catch up. That's the core tension, and it's why the standard advice doesn't fit.
Why the Employee Retirement Playbook Doesn't Work for Owners
Most retirement advice is written for employees. Contribute to your 401(k) up to the match, max your Roth IRA, then add more to the 401(k). Clean, linear, automatic.
Owners don't operate in a linear system. Income fluctuates year to year. Your tax situation shifts with revenue, expenses, and how you structure your own compensation. Applying generic rules without adapting them can mean overpaying in taxes, undercontributing to retirement accounts, or both at once.
Jeff Judge puts it plainly: "When you own the business, retirement planning and tax planning are the same conversation. You can't separate them. Owners who treat them as two different problems usually make weak decisions on both."
That integration, tax and retirement strategy working as one, is where self-employed retirement planning starts to look genuinely different from anything in the standard playbook. It's also why a good What questions should I ask before hiring a financial advisor? conversation should cover both at once.
The Retirement Account Options Business Owners Actually Have
The IRS offers several account structures built specifically for self-employed people and business owners. Choosing among them depends on your income, your employee count, and how aggressively you want to save. According to the IRS, several of these plans let owners contribute far more than a typical W-2 employee can.
Solo 401(k)
Available to owners with no full-time employees other than a spouse. In 2026, you can defer up to $24,500 as the employee, plus an additional $8,000 catch-up if you're 50 or older (and a larger catch-up of $11,250 if you're ages 60 to 63), then add an employer contribution of up to 25% of compensation. The combined maximum reaches $72,000, per IRS guidance. That ceiling sits well above anything a standard W-2 employee can access in a single year. If you want a side-by-side comparison, see Should I Choose a Solo 401(k) or SEP IRA for My Business?.
SEP IRA
Simpler to set up and run, but less flexible. Contributions are limited to 25% of net self-employment income, capped at $72,000 in 2026. If you have employees, you must contribute the same percentage to their accounts as you do to your own, which is one reason a Solo 401(k) often makes more sense for true solo operators.
Defined Benefit Plan
For higher earners who want to shelter amounts well above $72,000, a defined benefit plan allows contributions based on actuarial math and a target retirement income. These plans demand more administration and consistent annual funding, but they're among the most powerful tax-reduction tools available to self-employed people with high, steady income.
SIMPLE IRA
A lower-contribution option suited to businesses with up to 100 employees. The 2026 employee limit is $17,000, with a $21,000 limit for those 50 and older. Less common among high earners chasing maximum deferral, but worth understanding as your structure evolves.
The right choice isn't universal. It depends on income consistency, payroll obligations, and how you've built the business.
The Business Itself Is Part of the Retirement Plan
Here's what separates business owner retirement planning from everything else: for many owners, the business is the retirement plan. The value built over 20 or 30 years, through a potential sale, succession to a family member or key employee, or an ESOP, can represent more wealth than everything in traditional retirement accounts combined.
That's both a strength and a real vulnerability.
The strength: a successful exit can fund decades of income in a single transaction. The vulnerability: that wealth is illiquid, concentrated in one asset, and dependent on factors only partly in your control, including market timing, buyer availability, and whether the company can run without you at the center.
Jeff has watched this play out many times. "I've sat with owners in their late 50s who have a multimillion-dollar business and almost nothing in retirement accounts. They reinvested everything for years. That's not automatically wrong, but it means the exit becomes the retirement strategy, and we have to plan for it with the same rigor we'd apply to any portfolio."
Working through Chesapeake Financial Planners' R.U.D.D.E.R. Method™, this usually surfaces in the Review and Recognize phase, where the business is catalogued alongside personal assets and the gap between current trajectory and real income needs becomes visible for the first time. For owners who haven't mapped this yet, What Do Business Owners Most Often Forget to Plan Before Exiting? is a useful next read.
Tax Strategy Is Where Owners Win or Fall Behind
The right retirement account paired with the right business entity can meaningfully change your long-term tax picture. S-Corps, LLCs, and sole proprietors each interact differently with contribution limits, deduction timing, and self-employment tax. Getting this wrong is expensive.
A few high-leverage moves worth understanding:
- Contribution timing. Maximize deductions in high-income years by timing plan contributions strategically.
- Roth conversions. Convert traditional balances to Roth during lower-income years, such as the gap after you stop drawing full salary but before Social Security and RMDs create taxable income.
- Qualified Business Income deduction. Under Section 199A, many owners can deduct up to 20% of qualified business income, subject to income thresholds and business-type rules.
- Business-funded benefits. Health insurance premiums, HSA contributions, and plan administrative costs may be deductible as business expenses.
None of these levers exist for W-2 employees. Coordinated across your CPA and financial planner, they create real advantages, but only when the business, tax, and retirement conversations happen together. How you pay yourself feeds directly into this, which is why How Should Business Owners Pay Themselves Salary vs Distributions? is worth reviewing alongside your plan.
Frequently Asked Questions
Can I contribute to both a Solo 401(k) and a SEP IRA in the same year?
Generally not for the same business, because a Solo 401(k) effectively replaces the SEP IRA when you operate a single entity. You can hold both only if they relate to genuinely separate business activities, and the rules get complicated fast. A CPA or planner who works with self-employed retirement accounts can confirm what your specific structure allows before you fund either one.
What happens to my retirement accounts if I sell the business?
Your existing retirement accounts stay with you, because they belong to you personally and are not attached to the business entity. The sale proceeds are separate and need their own tax and investment plan. That distinction matters before any purchase agreement is signed, since proceeds and account balances are taxed and managed under entirely different rules.
How much should a business owner hold in retirement accounts outside the business?
A commonly cited guideline is keeping no more than 50% to 60% of total net worth concentrated in the business, though the right number varies with your age, income consistency, business type, and exit timeline. The less liquid your company, the more important outside savings become, because they give you income that doesn't depend on finding a buyer.
At what point should exit planning begin?
Most advisors recommend starting five to seven years before your target exit date, not because you're ready to leave, but because building a business that can actually sell on your timeline often requires structural changes that take years to implement. Waiting until you feel emotionally ready to exit frequently narrows your options and lowers your final sale value.
Is the sale of a business taxed like retirement income?
Proceeds from a business sale are typically taxed as capital gains rather than ordinary income, which is generally more favorable. The actual treatment depends on how the sale is structured, whether it's an asset sale or stock sale, how proceeds are allocated across goodwill and equipment, and whether installment payments are involved. Discuss this with your CPA and planner well before negotiations begin.
Building retirement around a business takes a different blueprint than the standard advice assumes. If this was helpful, our guide on planning an exit on your own timeline goes deeper into the structural moves that protect your sale value. Download it at chesapeakefp.com.
Want to go deeper? Our Tax Strategy Readiness Quiz walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


