
How Do I Protect My Children's Inheritance in a Blended Family?
Last reviewed: July 2026
To protect your children's inheritance in a blended family, you combine three tools: an updated will, a trust (often a QTIP trust) that separates income from principal, and beneficiary designations that match your actual wishes. Beneficiary designations override your will, so the single most common mistake in blended family financial planning is leaving an ex-spouse or the wrong person on a retirement account or life insurance policy. Done right, you can provide for your current spouse and still guarantee your kids receive what you intended.
Key Takeaways
- Beneficiary designations on retirement accounts and life insurance override your will, so review them first.
- A QTIP trust provides income to your surviving spouse while preserving the principal for your children.
- Roughly 40% of new marriages in the U.S. involve at least one previously married spouse.
- A prenuptial agreement is a clarity tool in blended families, not a sign of distrust between spouses.
- Without an updated plan, state intestacy law, not your wishes, decides who inherits.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate blended family financial planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often points out that the most painful inheritance disputes he sees aren't caused by bad intentions; they're caused by a beneficiary form nobody updated after a remarriage.
What Makes Blended Family Financial Planning Different?
Blended family financial planning carries complications that first-marriage households rarely face. You may be paying child support, meeting alimony obligations, or funding college for kids from a prior marriage. Your spouse may carry similar commitments. You both arrive with retirement accounts, property, and promises already made.
Here's the part that surprises people. The default legal structure almost never matches what you actually want. If you die without an updated estate plan, state intestacy law steps in, and in most states a surviving spouse receives a large share of the estate before your children see a dime. That can unintentionally disinherit kids you meant to protect.
Remarriage is common. According to Pew Research Center, about four in ten new marriages include at least one spouse who has been married before. Yet conventional planning advice still assumes a single set of heirs. That gap is where families get hurt.
Jeff Judge has watched this play out more than once: an adult child expecting to inherit a parent's IRA, only to learn the account passed entirely to a stepparent because the beneficiary form was never changed. The will said one thing. The form said another. The form won.
Should You Have a Prenuptial Agreement Before Remarrying?
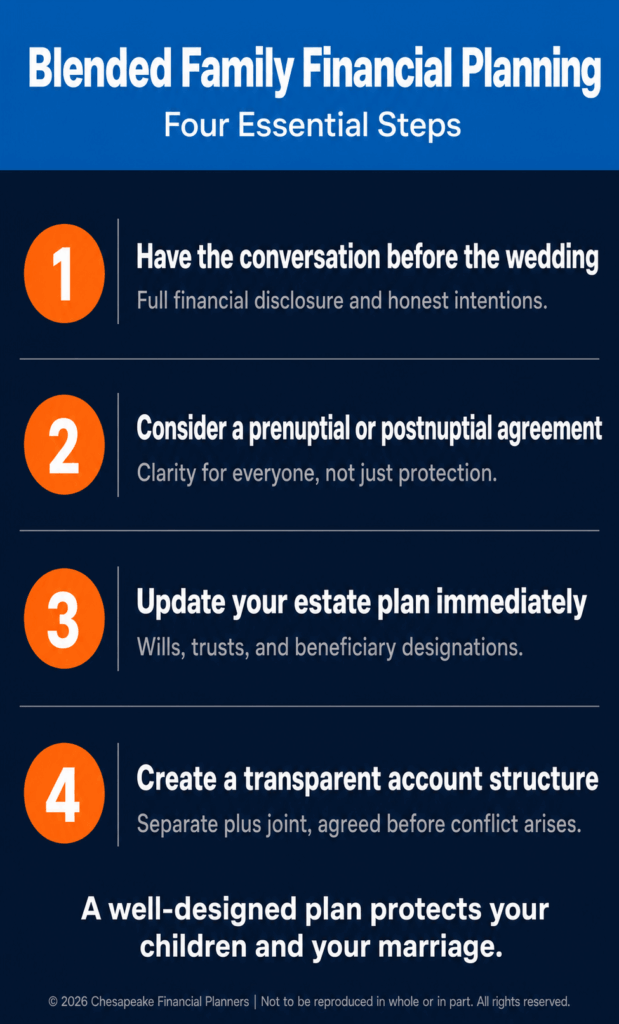
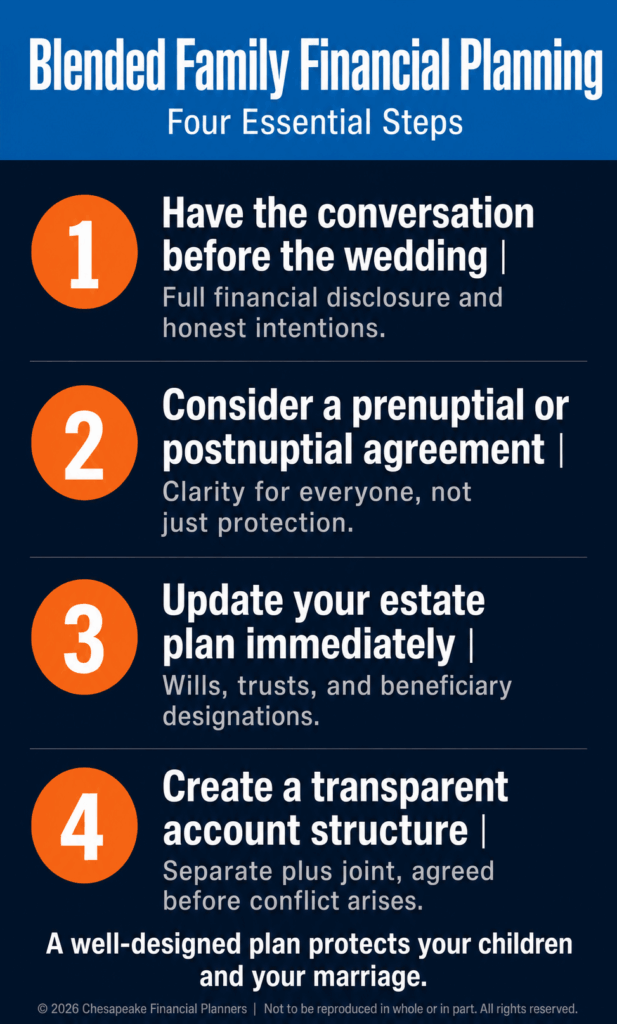
Yes, in most blended family situations a prenuptial or postnuptial agreement is worth serious consideration, because it protects assets you've earmarked for your children while setting clear expectations with your new spouse. Many people see a prenup as unromantic or a sign of distrust. In a second marriage with children, it functions as the opposite: a written agreement that removes ambiguity and prevents conflict later.
A well-drafted agreement can:
- Protect assets you intend to pass to your children
- Clarify how property acquired during the marriage will be treated
- Define financial support expectations during the marriage
- Give both spouses and all children peace of mind about where things stand
Both partners need independent legal counsel for the agreement to hold up. An agreement one spouse never had a chance to review with their own attorney is the kind of agreement that gets challenged in court.
This is also where a postnuptial agreement comes in. If you're already remarried and skipped this step, it isn't too late. A postnup accomplishes much of the same clarity after the wedding.
How Do Trusts Protect Children's Inheritance?
A trust protects children's inheritance by separating who gets the income from who gets the principal, which lets you provide for a surviving spouse without giving them control over the ultimate destination of your assets. For blended families, the workhorse tool is the QTIP trust.
A QTIP trust (Qualified Terminable Interest Property trust) pays income to your surviving spouse for life, then passes the remaining principal to your children when your spouse dies. Your spouse is taken care of. Your kids are guaranteed the principal. Neither outcome depends on goodwill between people who may not be close.
The IRS treats QTIP property as qualifying for the marital deduction when the proper election is made, which has meaningful estate tax implications worth reviewing with an advisor and an attorney. For 2026, the federal estate tax exemption sits at $15 million per individual, so most families won't owe federal estate tax, but the inheritance-protection function of the trust matters regardless of whether tax is owed.
Beyond the QTIP, a revocable living trust can hold assets, name your children as remainder beneficiaries, and avoid probate. The right structure depends on your assets, your state, and the relationships involved. There's no single template that fits every blended family.
Who owes Maryland's 10% inheritance tax and what planning options protect non-lineal heirs?
Why Beneficiary Designations Matter More Than Your Will
Beneficiary designations on retirement accounts, life insurance, and annuities pass directly to the named person and override whatever your will says. This is the single most overlooked detail in blended family financial planning, and it causes the most damage.
Picture this. Your will leaves everything to your three children. But your 401(k), worth more than your house, still lists your former spouse as beneficiary from fifteen years ago. When you die, that account goes to your ex. Your will never touches it. Your children have no legal claim.
After any remarriage, review and update:
- 401(k), IRA, and other retirement account beneficiaries
- Life insurance policy beneficiaries
- Annuity beneficiaries
- Transfer-on-death and payable-on-death account designations
Jeff uses a simple framework with clients here, drawn from the firm's planning process. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The Review and Recognize step exists precisely to catch stale beneficiary forms before they become a crisis.
Do I need to update my beneficiary designations after a divorce or major life change?
What is a will and do I need one for my estate?
Frequently Asked Questions
Does my will control who inherits my retirement accounts?
No, your will does not control retirement accounts or life insurance. These assets pass directly to whoever is named on the beneficiary designation form, which legally overrides your will. If your ex-spouse is still listed as beneficiary, they will inherit that account even if your will leaves everything to your children.
What is a QTIP trust and who should use one?
A QTIP trust provides lifetime income to a surviving spouse while guaranteeing the remaining principal passes to your chosen heirs, usually your children. Blended families use it most often, because it lets you support your current spouse without giving them the power to redirect assets away from your kids after you die.
Is a prenuptial agreement necessary for a second marriage?
A prenuptial agreement is not legally required, but for second marriages with children it is one of the strongest tools for protecting inheritance and preventing conflict. It documents which assets stay separate, how marital property is handled, and what each spouse can expect, with both parties using independent legal counsel.
What happens if I die without updating my estate plan after remarrying?
If you die without an updated estate plan, state intestacy law decides who inherits, and in most states your surviving spouse receives a large share before your children. This can unintentionally disinherit kids from a prior marriage. Updating your will, trusts, and beneficiary forms after remarrying prevents that outcome entirely.
How should blended families handle joint and separate accounts?
There is no single correct structure, but most blended families keep pre-existing assets and obligations in separate accounts while funding a joint account for shared household expenses. Some couples contribute to the joint account proportionally based on income. The right approach is whatever both spouses agree to and can sustain over time.
Can a postnuptial agreement help if we are already married?
Yes, a postnuptial agreement accomplishes much of what a prenup does, just after the wedding. It can clarify which assets remain separate for your children, define how marital property is treated, and set expectations for financial support. Both spouses should use independent attorneys for it to hold up legally.
If you found this helpful, our estate planning guide for blended families walks through the documents, conversations, and trust structures covered here in greater depth. Download it at chesapeakefp.com to start protecting your children's inheritance while building a healthy financial future with your spouse.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


