

Do I need to update my beneficiary designations after a divorce or major life change?
Last reviewed: July 2026
Yes, you must actively update your beneficiary designations after a divorce or any major life change, because these designations override your will and, in most states, a divorce does not automatically remove an ex-spouse. Your beneficiary forms quietly control who receives your retirement accounts and life insurance when you die, regardless of what your will says. Outdated designations are one of the most common and most painful estate planning mistakes, and they fall especially hard on women, who more often outlive a spouse and manage these decisions alone in later years.
Key Takeaways
- Beneficiary designations override your will, so an outdated form can send assets to the wrong person no matter what your will states.
- In most states a divorce does not automatically remove an ex-spouse; you must change the designation yourself.
- Naming a minor child directly, skipping a contingent beneficiary, or naming your estate are common, costly errors.
- Review beneficiaries after every major life event and at least once a year as part of a financial review.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. As an Accredited Estate Planner®, he has helped Harford County and Baltimore-area families, including many women navigating divorce and widowhood, keep their estate plans intact since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: the single most preventable estate disaster I see is a years-old beneficiary form that quietly overrules everything in the will, and it takes ten minutes to fix once you know to look.
Why do beneficiary designations override your will?
Beneficiary designations override your will because the assets they govern pass directly to the named person by contract, outside the probate process your will controls. This is the single most important and most misunderstood fact in estate planning.
Certain assets, retirement accounts like 401(k)s and IRAs, life insurance, annuities, and payable-on-death or transfer-on-death bank and brokerage accounts, transfer straight to whoever is named on the form, bypassing your will entirely. As the IRS explains, "A beneficiary is generally any person or entity the account owner chooses to receive the benefits of a retirement account or an IRA after they die," which is exactly why an outdated form after a divorce is so dangerous. So if your will leaves everything to your current spouse but your ex-spouse is still named on your 401(k), your ex-spouse receives it. If you intended to divide assets equally among your children but only one is named on a life insurance policy, only that child collects. Courts consistently uphold the beneficiary designation over the will, even when the form clearly no longer reflects your wishes.
This is exactly why updating designations after a divorce is urgent rather than optional. In most states, a divorce decree does not by itself strip an ex-spouse from your beneficiary forms; the change only happens when you make it. The painful reality, which Jeff Judge has seen firsthand, is divorced parents who die with an ex-spouse still named on the life insurance meant for their children, after which the ex receives the proceeds and the children receive nothing.
What are the most common beneficiary mistakes?
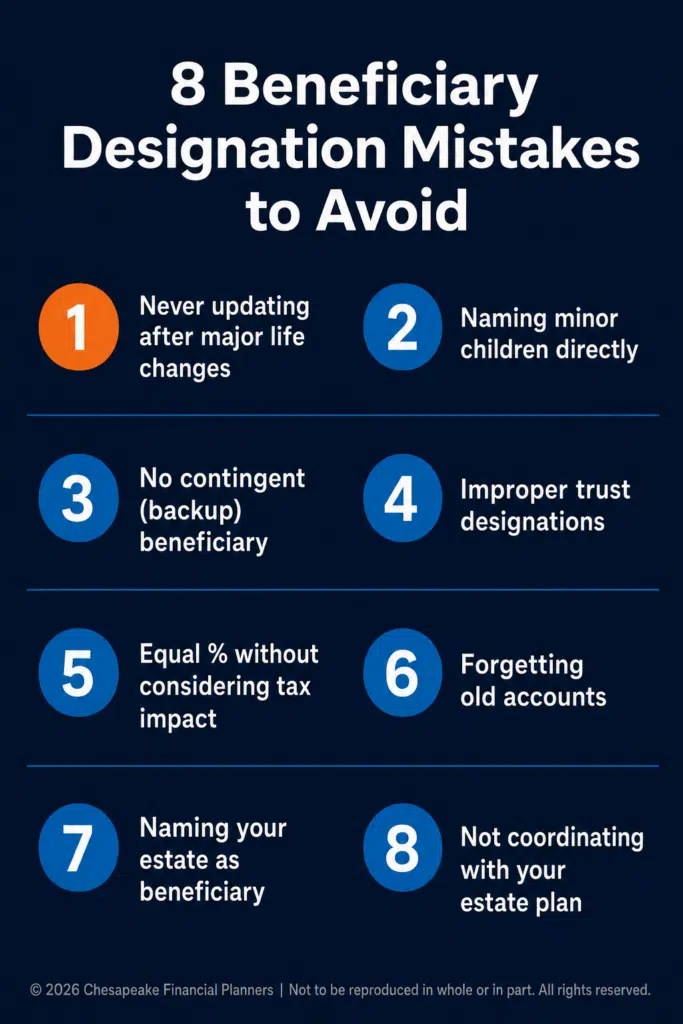
The most common beneficiary mistakes are failing to update after life changes, naming minors directly, skipping contingent beneficiaries, and naming your estate, each of which can derail an otherwise sound plan. Knowing them is the first step to avoiding them.
The recurring errors are:
- Never updating after a major life change. Marriage, divorce, a birth or adoption, a beneficiary's death, or remarriage all should trigger an update; skipping it sends assets to outdated recipients.
- Naming minor children directly. You cannot leave substantial assets directly to a minor, so a court appoints a guardian to manage the money until the child reaches adulthood, who then receives the full amount outright. Naming a properly drafted trust instead lets you control how and when funds are used.
- Skipping contingent beneficiaries. If your primary beneficiary dies before you and there is no backup, the asset usually flows to your estate and through probate. Always name at least one contingent beneficiary.
- Improper trust designations. If you name a trust, use its exact legal name and date and make sure it is set up to hold retirement accounts properly, since vague or unfunded trust designations cause tax and distribution problems.
- Ignoring tax differences. Leaving each child an equal percentage can be unequal after tax if one inherits a taxable traditional IRA and another a tax-free Roth or life insurance.
- Forgetting old accounts. Former-employer 401(k)s, small old IRAs, work life insurance, and old annuities all carry their own designations that people forget to review.
- Naming your estate. Retirement accounts and life insurance should almost never name your estate, which triggers probate, exposes assets to creditors, and can worsen the tax treatment of retirement accounts under the IRS inherited-account distribution rules.
- Not coordinating with your estate plan. A designation that contradicts your will or trust can cause real harm, such as naming a disabled child directly and disqualifying them from needs-based benefits like Supplemental Security Income that a special needs trust was meant to preserve.
This kind of coordination across every account and document is precisely what the R.U.D.D.E.R. Method™ is built to ensure. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and beneficiary review runs through Review and Recognize and Reassess and Refine, where designations are checked against your current life and the rest of your plan.
Why is this especially important for women?
Beneficiary planning is especially important for women because they more often outlive their spouses, navigate divorce and widowhood, and end up managing these decisions alone later in life. The stakes and the responsibility both tend to land disproportionately on women.
After a divorce, the rule bears repeating: in most states divorce does not automatically remove an ex-spouse from your forms, so you must change the designation yourself, and you should do it immediately after the divorce is final rather than letting it slip. Employer plans add a wrinkle, because under federal law your current spouse is the default beneficiary of a 401(k), and the Department of Labor notes that naming someone else requires a notarized spousal waiver, a detail that matters during and after a divorce. After widowhood, a surviving spouse often needs to update both the accounts inherited from a late spouse and her own accounts, perhaps naming adult children or a trust in place of the deceased spouse. Women who stepped away from paid work for caregiving may have old retirement accounts from former employers sitting with stale beneficiaries that deserve tracking down and verifying.
Because women typically live longer, they are also more likely to be the last decision-maker, the one whose designations ultimately direct where the family's assets go. That makes a regular review habit especially valuable. Reviewing beneficiaries each year, and after every major life event, keeps a plan aligned with reality across the decades when it matters most.
How do you review and update your beneficiaries?
You review and update your beneficiaries by inventorying every account, checking each designation against your current wishes, making the changes formally, and documenting the result. A simple, repeatable process closes the gaps that cause problems.
Work through these steps:
- Create a complete inventory of every account with a beneficiary, current and former employer retirement plans, all IRAs, life insurance (personal and through work), annuities, and any payable-on-death or transfer-on-death accounts, noting the current primary and contingent beneficiaries on each.
- Review each for accuracy, asking whether the named people reflect your current wishes, whether any minors are named directly, whether contingent beneficiaries exist, and whether the designations coordinate with your will and trust.
- Make the updates formally with each institution, online or by paper form, and never rely on a verbal promise; complete the official process and keep written confirmation.
- Document your decisions in a master list, account, institution, primary and contingent beneficiaries, and the date last updated, stored with your estate planning documents.
- Review regularly, at least annually and after any marriage, divorce, birth, death, job change, or update to your will.
For more complex situations, blended families, special needs dependents, larger estates, or significant retirement accounts, an estate planning attorney and financial advisor can make sure your designations coordinate with the whole plan and minimize taxes. The goal is simple: make sure these forms say exactly what you intend, because they carry more legal weight than almost any other financial document you hold.
Related Topics Worth Reading
Beneficiary planning connects to divorce, estate, and trust decisions. These related topics go deeper.
- The canonical guide to the costliest beneficiary errors. What Are the Most Common Beneficiary Designation Mistakes?
- Rebuilding your financial life and documents after a divorce. How do I rebuild my finances and establish financial independence after a divorce?
- How a QDRO divides retirement accounts in a divorce. How does a QDRO work and what do I need to know to protect my retirement savings in a divorce?
- Why a special needs trust must be the beneficiary, not the child. Special Needs Trusts: Protecting a Dependent's Future
- Keeping assets out of probate entirely. How Can I Avoid Probate When Planning My Estate?
Frequently Asked Questions
Does divorce automatically remove my ex-spouse as beneficiary?
No, in most states divorce does not automatically remove your ex-spouse from your beneficiary designations. You must actively change the designation yourself with each institution. Many people assume the divorce decree handles it, and as a result ex-spouses end up receiving retirement accounts and life insurance that were meant for children or a new spouse. Update every beneficiary form immediately after a divorce is finalized rather than waiting.
Do beneficiary designations override a will?
Yes, beneficiary designations override your will for the assets they govern, including retirement accounts, life insurance, annuities, and payable-on-death or transfer-on-death accounts. These assets pass directly to the named beneficiary outside of probate, so even if your will says otherwise, the person on the form receives the asset. Courts consistently uphold the designation over the will, which is why keeping forms current is essential.
Should I name my minor child as a beneficiary?
Generally no; naming a minor child directly as a beneficiary creates problems, because a court must appoint a guardian to manage the money until the child reaches adulthood, after which they receive the full amount with no restrictions. A better approach is to name a properly drafted trust as beneficiary, with instructions for how and when funds are distributed, which protects the money and lets it be used for the child's needs along the way.
How often should I update my beneficiary designations?
You should review your beneficiary designations at least once a year as part of a financial review, and immediately after any major life event, including marriage, divorce, the birth or adoption of a child, the death of a beneficiary, a job change, or an update to your will or trust. Regular review is especially important for anyone likely to be the last decision-maker for the family's assets, since outdated forms can quietly undo years of planning.
Why shouldn't I name my estate as the beneficiary?
You should almost never name your estate as the beneficiary of retirement accounts or life insurance, because doing so forces the assets through probate, exposes them to creditors, and can create unfavorable tax treatment for retirement accounts. If you want assets distributed according to your will's terms, name a properly structured trust as the beneficiary instead, which preserves control while avoiding the drawbacks of routing everything through your estate.
Make your designations say what you mean
Your beneficiary designations may be the most powerful financial documents you own, because they override your will and direct your largest accounts directly to the people named on them. After a divorce, a remarriage, a birth, or a death, those forms need your attention promptly, since the law usually will not update them for you, and the cost of an oversight falls hardest on the families left behind. Pull your statements this week and check who is listed. If you would like a second set of eyes, Jeff Judge and the Chesapeake Financial Planners team help families across Harford County and the Baltimore metro keep their designations aligned with their wishes, alongside their estate attorneys. Schedule a free fit call at chesapeakefp.com.
Want to go deeper? Our 10 Signs You're Ready for a Certified Financial Planner walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


