

Did the OBBBA Actually Eliminate Social Security Taxes?
Last reviewed: July 2026
No, the One Big Beautiful Bill Act did not eliminate Social Security taxes. That answer is direct and it needs to be said plainly, because the news coverage created a widespread impression that it did. What the OBBBA actually created is a new $6,000 above-the-line deduction for taxpayers age 65 and older, available through 2028, that phases out above $75,000 for single filers and $150,000 for married couples filing jointly. The deduction is real and useful for qualifying retirees. It is not the same as exempting Social Security income from taxation, and for many retirees — including those with joint income above $150,000 — it changes nothing at all about how their Social Security benefits are taxed.
Key Takeaways
- The Social Security taxation rules established in 1983 and 1993 were not changed by the OBBBA.
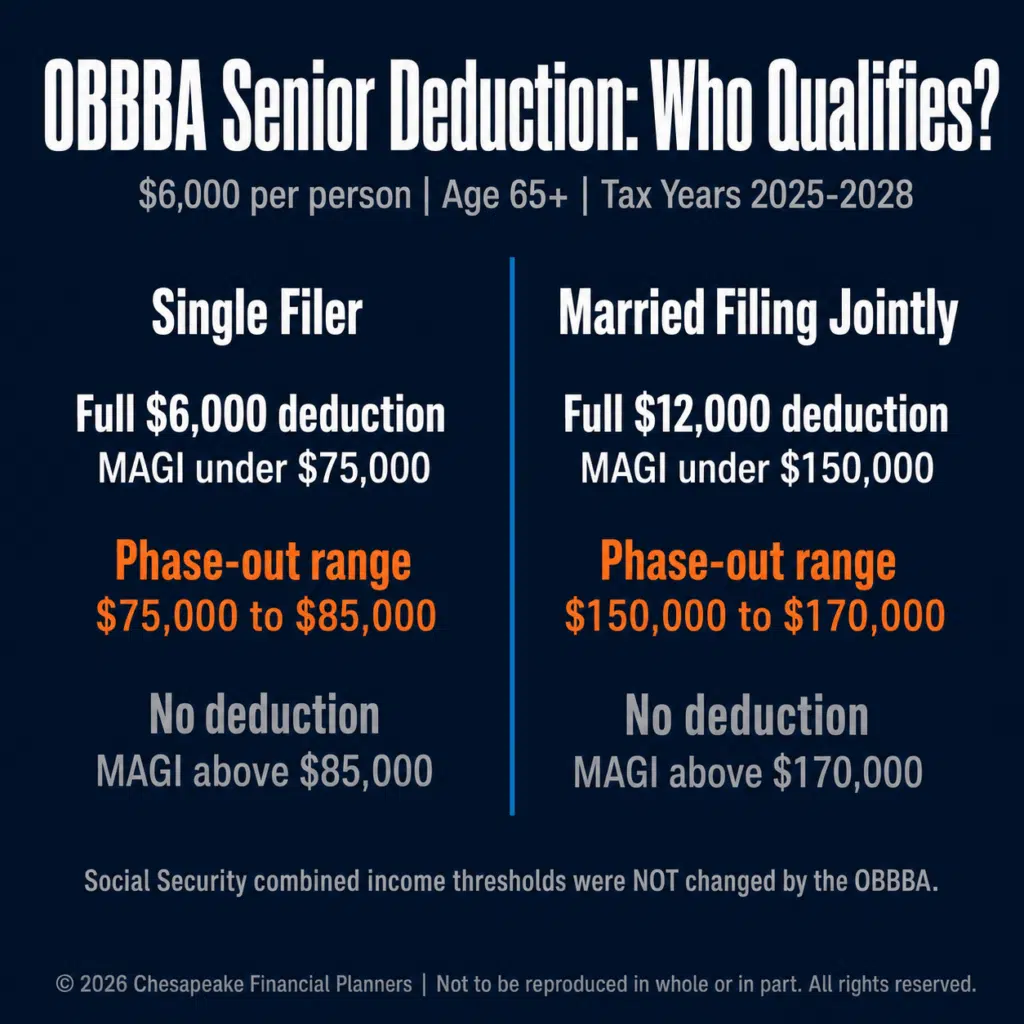
- The OBBBA created a new $6,000 above-the-line deduction per qualifying taxpayer age 65 or older, effective for tax years 2025 through 2028.
- The deduction phases out beginning at $75,000 MAGI for single filers and $150,000 for married filing jointly — couples above those thresholds receive no benefit.
- Combined income thresholds for Social Security taxation ($32,000 and $44,000 for joint filers) remain unchanged and have never been indexed for inflation.
- Long-term planning around Social Security taxation still centers on provisional income management, Roth conversions, and What Is Tax-Efficient Fund Placement for Retirement Accounts?.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has worked with retirees and pre-retirees across Harford County and the Baltimore metro area on Social Security strategy, provisional income planning, and retirement income distribution since earning his CFP® in 2013. Jeff speaks directly with clients when legislative changes generate confusion, including the significant misinformation that circulated after the OBBBA passed, by using Chesapeake Financial Planners' signature process, the R.U.D.D.E.R. method™.
What the viral claim actually says (and why it spread)
The White House promoted the One Big Beautiful Bill using explicit "no tax on Social Security" language. That message spread efficiently through financial media, social channels, and word of mouth all through the summer and fall. Retirees called their advisors. Adult children called their parents' advisors. The claim had enough authority behind it that people treated it as settled law.
The Social Security section of the original legislative proposal would have excluded benefits from income tax entirely. That provision did not survive the legislative process. What passed was a bill with dozens of provisions, one of which created a new deduction — not an exemption — for older taxpayers.
The distinction matters enormously in practice. An exemption would remove Social Security income from the tax base entirely. A deduction reduces adjusted gross income (AGI), which can in turn reduce how much of your Social Security falls into the taxable portion of the combined income calculation. These are related but not equivalent outcomes, and the deduction is significantly more limited in scope.
What the OBBBA actually created: the $6,000 senior deduction
Here is what the OBBBA provision actually created: a new above-the-line deduction of $6,000 per qualifying individual, available to taxpayers who are age 65 or older on December 31 of the tax year. A married couple where both spouses are 65 or older can claim $12,000 in total. The deduction is above-the-line, meaning it reduces AGI before you reach itemized deductions or the standard deduction calculation.
The deduction phases out based on modified adjusted gross income (MAGI). For single filers, the phase-out begins at $75,000. For married filing jointly, it begins at $150,000. Above those thresholds, the deduction reduces and eventually disappears entirely.
The deduction sunsets on December 31, 2028. That is not speculation about possible future expiration — it is what the law says. Four tax years: 2025, 2026, 2027, and 2028.
The deduction reduces AGI. A lower AGI can in turn reduce the portion of Social Security included in taxable income, because the combined income calculation the IRS uses to determine Social Security taxability starts with AGI. So there is an indirect benefit. But the Social Security taxation rules themselves — the thresholds, the percentages — were not touched.
Who actually qualifies (the income phase-out math)
The deduction is most meaningful for retirees with moderate incomes who qualify fully or partially for the benefit.
Consider a couple, both age 68, with $30,000 in Social Security benefits, $40,000 in IRA distributions, and $20,000 in investment income. Their MAGI is approximately $90,000. Both are under the $150,000 joint threshold. The $12,000 combined deduction reduces their AGI by $12,000. That lower AGI feeds into the Is Social Security Taxable? 2026 Tax Rules Explained that determines Social Security taxability, potentially moving some portion of benefits from the 85% taxable tier toward the 50% tier. At a 22% marginal federal rate, $12,000 in reduced AGI translates to roughly $2,640 in federal tax savings. Real money. Not nothing.
Now consider a couple with $80,000 in Social Security benefits, $150,000 in IRA distributions, and $40,000 in investment income. Their MAGI exceeds $150,000. The deduction phases out entirely. Their Social Security taxation picture in 2026 is identical to what it was in 2024. The OBBBA did nothing for them.
The population that benefits falls between those two examples: retirees with MAGI below the phase-out threshold, who are 65 or older, and whose tax situation would be meaningfully changed by a $6,000 to $12,000 reduction in AGI. That is a real population. It is not everyone.
What this means for Social Security taxation going forward
The underlying rules governing Social Security taxation are unchanged. The Social Security Administration's explanation of how benefits are taxed remains accurate law.
The IRS uses a figure called combined income: adjusted gross income plus nontaxable interest plus half of your Social Security benefits. If that combined income exceeds certain thresholds, a portion of benefits becomes taxable. For single filers, up to 50% of benefits can be taxable between $25,000 and $34,000, and up to 85% above $34,000. For married filing jointly, the 50% threshold starts at $32,000 and the 85% threshold begins at $44,000.
Those thresholds were set in 1983 and 1993. They have never been indexed for inflation. In 1993 dollars, $44,000 in combined income described a relatively affluent household. If the $44,000 threshold had kept pace with inflation, it would sit around $90,000 in today's terms. Because it was not adjusted, a retiree couple with $50,000 in combined income faces the same taxation structure that Congress originally designed for much higher earners. The OBBBA did not address this structural problem.
For planning purposes through 2028, if you are 65 or older and your MAGI falls below the phase-out threshold, capture the deduction. Make sure your tax preparer accounts for it correctly — it does not file itself. And plan around the sunset: the deduction expires after 2028 unless Congress extends it. Build income projections around the rules as they stand now.
Maryland angle: what Maryland actually does with Social Security income
Maryland's treatment of Social Security income is worth knowing clearly, because it is genuinely favorable and frequently misunderstood.
Maryland does not tax Social Security benefits for most residents. The state follows federal rules on Social Security inclusion, but then subtracts the taxable Social Security amount from Maryland taxable income for residents whose federal AGI is below $100,000 (single) or $150,000 (joint). Above those thresholds, Maryland taxes a portion of Social Security based on the same federal combined income calculation, but lower-income retirees are largely exempt at the state level.
This matters for How Can Maryland Retirees Reduce Their State Tax Burden? planning. A Harford County retiree with modest income who gets hit at the federal level by the Social Security taxation rules may face little or no Maryland tax on the same benefits. The OBBBA senior deduction, by reducing federal AGI, could also affect whether a retiree crosses Maryland's income threshold — which is an additional indirect benefit for some Maryland taxpayers worth reviewing with a tax professional.
The broader planning strategy for Maryland retirees around Social Security taxation works through the same levers as the federal strategy: managing the composition of income, using Roth assets that produce qualified distributions not counted in combined income, and timing When does a Roth conversion make financial sense and how do you execute it? strategically in the years before Social Security begins and before required minimum distributions force larger taxable distributions.
This type of income composition planning belongs inside the R.U.D.D.E.R. Method™ — Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Social Security taxation sits at the intersection of asset location, withdrawal sequencing, and tax bracket management: all Design and Develop questions that need to be revisited as income levels shift.
"I've had more than a few conversations this year where clients came in certain that their Social Security benefits would no longer be taxed. The news cycle created that impression. The actual law created something more specific and more limited."
As I, Jeff Judge, CFP®, explain to clients navigating the OBBBA's senior deduction: the provision is real and worth capturing, but it is not a substitute for the provisional income management and Roth conversion planning that determines how much of your Social Security is taxable in the first place.
Frequently Asked Questions
Did the OBBBA eliminate Social Security taxes?
No. The Social Security taxation rules established in 1983 and 1993 were not changed by the OBBBA. What the bill created is a new $6,000 above-the-line deduction for taxpayers age 65 or older, available through 2028, that phases out above $75,000 single and $150,000 joint. Social Security benefits remain taxable under the same combined income framework that has applied since 1993.
Who qualifies for the new $6,000 OBBBA senior deduction?
Taxpayers who are age 65 or older on December 31 of the tax year and whose MAGI falls below the phase-out threshold — $75,000 for single filers and $150,000 for married filing jointly. A qualifying couple can claim $12,000 combined. The deduction phases out above those thresholds and disappears entirely for higher-income retirees. It is available for tax years 2025 through 2028 only.
How does the OBBBA deduction affect Social Security taxation indirectly?
The deduction reduces AGI. A lower AGI lowers your combined income figure, which is what the IRS uses to determine how much of your Social Security is taxable. If the reduction is large enough to move your combined income from the 85% taxability tier toward the 50% tier, a portion of your Social Security benefits that would have been taxable may no longer be. The actual benefit depends on your income level, filing status, and marginal tax bracket.
Does Maryland tax Social Security income?
For most Maryland residents, no. Maryland excludes Social Security income from state taxable income for residents with federal AGI below $100,000 (single) or $150,000 (joint). Above those thresholds, Maryland's treatment is more nuanced and mirrors the federal combined income approach. This means many Harford County and Baltimore-area retirees with moderate incomes avoid Maryland Social Security tax entirely, making federal-level planning around combined income even more impactful.
When does the OBBBA senior deduction expire?
The deduction sunsets on December 31, 2028. That's four tax years: 2025, 2026, 2027, and 2028. Unless Congress acts to extend it, retirees who benefit from this deduction in 2026 should not assume it will still exist when planning for 2029 and beyond. Build income projections around the rules as they currently stand.
How do I capture the OBBBA deduction on my tax return?
The deduction is an above-the-line deduction, meaning it reduces AGI on your federal return before you reach the standard deduction or itemized deduction calculation. It should appear on your Form 1040. Make sure your tax preparer is aware of the provision and is applying it correctly — it is not automatic and does not file itself. If you prepare your own return, verify your software is updated to reflect 2025+ law changes.
Schedule a Social Security income review
If you came into 2026 thinking your Social Security would no longer be taxed, you are not alone — and your plan may need adjustment based on what the law actually says. If you benefit from the OBBBA deduction through 2028, that is four years of real tax savings worth capturing correctly. If your income is above the phase-out threshold, the conversation shifts entirely to provisional income management, Roth conversion timing, and What Is Medicare IRMAA and Why Does It Hit High Earners Two Years Late? planning.
At Chesapeake Financial Planners, I work with pre-retirees and retirees across Harford County, Bel Air, Forest Hill, and the Baltimore metro area on exactly this kind of income planning. Schedule a complimentary consultation at chesapeakefp.com to walk through your Social Security strategy and how the OBBBA affects your specific situation.
This post is adapted from 'The New Tax Law Did Not Eliminate Social Security' originally published on Jeff Judge's LinkedIn.
Want to go deeper? Our Medicare and Social Security Guide walks through this step by step.
Prefer a different starting point? Our Tax Strategy Readiness Quiz is worth a look.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


