

What Is Medicare IRMAA and Why Does It Hit High Earners Two Years Late?
Last reviewed: July 2026
The IRMAA Medicare surcharge is an income-based penalty added to your Part B and Part D premiums when your Modified Adjusted Gross Income crosses defined thresholds. What makes it a consistent planning problem for affluent pre-retirees is the two-year lookback: your 2026 Medicare premiums are set by what you earned in 2024, not what you earn today. By the time most people see the bill, the income decision that caused it is two years in the past and completely out of reach.
Key Takeaways
- IRMAA stands for Income-Related Monthly Adjustment Amount and is assessed by the Social Security Administration based on your MAGI from two years prior.
- In 2026, the standard Part B premium is $202.90 per month. IRMAA can push that to $689.90 per person per month at the highest bracket.
- A married couple in the fourth IRMAA bracket pays over $10,700 more per year in Part B premiums alone compared to the standard rate.
- The most common triggers are Roth conversions, business sales, and large capital gains events — often sound financial decisions made without a Medicare premium projection attached.
- Form SSA-44 allows you to appeal IRMAA when a qualifying life-changing event has permanently reduced your income.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. Jeff has spent over a decade helping families in Harford County, Baltimore, and the surrounding region navigate the intersection of retirement income planning and Medicare costs, by using Chesapeake Financial Planners' signature process, the R.U.D.D.E.R. method™. He holds designations in estate planning (AEP®), insurance (CLU®), and financial planning (ChFC®, CFP®) that are directly applicable to pre-retirement income coordination. Jeff chairs the local FPA chapter and contributes to Kiplinger on tax-efficient retirement topics.
What IRMAA Is and How the Two-Year Lookback Works
IRMAA is not determined by your current income. It is determined by the most recent tax return on file with the IRS when the Social Security Administration sets premiums each fall. For 2026 premiums, that means your 2024 tax return.
The lag exists because the IRS does not certify current-year income data in time for fall premium calculations. The SSA reaches back two years to get a finalized number. The result is that a high-income year you had two years ago shows up in this year's Medicare bill, with no way to undo it after the fact.
Your MAGI for IRMAA purposes is your Adjusted Gross Income plus tax-exempt interest. It includes taxable Social Security, traditional IRA and 401(k) distributions, Roth conversions, capital gains, pension distributions, and deferred compensation. Qualified Roth IRA distributions do not count.
This is why the IRMAA Medicare surcharge catches high earners off guard more than any other Medicare cost. The income event feels distant. The bill feels current. In practice, the 2024 tax return sitting in a filing cabinet is the document CMS used to set the 2026 Medicare premium.
The 2026 IRMAA Brackets and What They Actually Cost
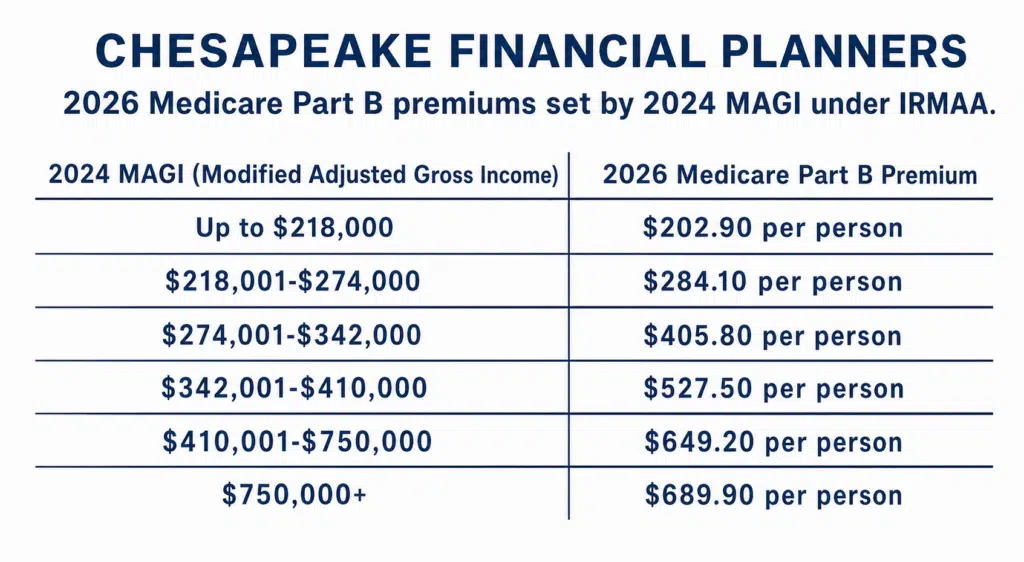
The 2026 Part B base premium is $202.90 per month, based on 2024 MAGI at or below $218,000 for joint filers and $109,000 for single filers. Above those thresholds, the surcharge adds real dollars per person per month:
| 2024 Joint MAGI | 2024 Individual MAGI | 2026 Monthly Part B Premium |
|---|---|---|
| Up to $218,000 | Up to $109,000 | $202.90 |
| $218,001 to $274,000 | $109,001 to $137,000 | $284.10 |
| $274,001 to $342,000 | $137,001 to $171,000 | $405.80 |
| $342,001 to $410,000 | $171,001 to $205,000 | $527.50 |
| $410,001 to $750,000 | $205,001 to $499,999 | $649.20 |
| $750,000+ | $500,000+ | $689.90 |
Part D IRMAA adds a separate monthly surcharge on top — ranging from $14.50 at Tier 1 to $91.00 at Tier 5 — billed by Medicare regardless of which Part D or Medicare Advantage plan you carry.
For a married couple where both spouses are on Medicare and both land in the fourth bracket (joint MAGI $410,001 to $750,000 in 2024), the annual Part B cost reaches $15,580.80. The standard-rate equivalent for the same couple is $4,869.60. The IRMAA surcharge accounts for $10,711.20 in additional cost, sourced entirely from a two-year-old tax return.
How can Roth conversions and RMDs trigger higher Medicare premiums (IRMAA)?
Why Affluent Pre-Retirees Keep Getting Caught Off Guard
"According to Jeff Judge, the most common IRMAA trigger isn't a reckless financial decision. It's a perfectly sound one that nobody ran through a Medicare premium projection." — Jeff Judge, CFP®
According to CMS data, IRMAA affects roughly 8% of all Medicare beneficiaries. Among high-net-worth households approaching retirement, the share is significantly higher — because the income types that trigger IRMAA are the same income sources that define affluent pre-retirement cash flow.
A business sale is the most frequent example in our practice. The transaction is well-structured. The proceeds are invested thoughtfully. The tax planning is in order. Two years later, the Medicare enrollment notice arrives and the surcharge is a surprise to everyone.
Large Roth conversions compressed into a single calendar year are another consistent trigger. Clients who understand the value of building Roth balances before RMDs begin sometimes convert significant amounts in one year without projecting the Medicare cost two years out. Portfolio rebalancing events that crystallize substantial capital gains work the same way. So do deferred compensation payouts and pension distributions that arrived on a schedule set years earlier.
The two-year window reinforces the problem in a specific way. Because the triggering income is already in the past by the time Medicare enrollment begins, there is nothing left to do about the current surcharge. The work that changes the outcome has to happen before enrollment, not after it.
How do you maximize Social Security and Medicare benefits in retirement?
Strategies to Avoid or Reduce IRMAA
The most reliable path to lower IRMAA is to control MAGI during the two years that will become lookback years for your Medicare enrollment date. If you enroll at 65, your year-one premiums are based on income at 63 and year-two premiums reflect income at 64.
Spreading large income events across calendar years. A Roth conversion that would land you in Tier 3 as a single event might fall in Tier 1 if spread across two years. The financial goal stays the same — the schedule changes.
Roth conversions in the gap years. If you retire before Medicare eligibility and Social Security has not started, you often have a window of lower income. Those years are typically the best opportunity to convert pre-tax balances at a lower bracket without compressing into a high-IRMAA year. When does a Roth conversion make financial sense and how do you execute it?
Qualified Charitable Distributions (QCDs). After age 70½, a QCD from a traditional IRA counts toward your RMD but does not raise MAGI. For clients who already give to charity, redirecting giving through a QCD can reduce IRMAA exposure without reducing charitable impact.
Sequencing withdrawals deliberately. In years when other income is high, pulling from Roth or basis-only sources to replace some traditional IRA draws can keep MAGI under the next IRMAA threshold. The savings are concrete: staying below the Tier 1 threshold as a joint filer saves roughly $974 per person per year in Part B alone.
IRMAA appeals via Form SSA-44. For clients who triggered IRMAA through a one-time income event that no longer reflects their financial picture, Form SSA-44 allows a reconsideration request. Qualifying events include retirement, reduction in work hours, divorce, death of a spouse, and loss of income-producing property. The appeal requires documentation of the event and evidence of the income change. Approval is not guaranteed and processing takes time, but it is worth pursuing when the documentation tells a clear story. IRMAA appeal process
The R.U.D.D.E.R. Method™ and IRMAA Planning
At Chesapeake Financial Planners, we work through Medicare premium exposure as part of the R.U.D.D.E.R. Method™ — our six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. IRMAA planning lives in the Uncover and Design steps: we map every anticipated large income event against the two-year lookback window before it is executed, not after.
The core question we ask before any significant income event in the four to five years approaching Medicare eligibility: what will this income look like on a tax return two years from now, and how does that interact with the Part B and Part D brackets? In most cases, the decision itself does not change. The timing or sizing often does.
What is the best retirement income planning strategy?
The Maryland Angle: Aberdeen Proving Ground Retirees Face a Stacked IRMAA Risk
Aberdeen Proving Ground federal employees who transition to retirement face a specific IRMAA stacking risk that rarely gets addressed before it lands on a Medicare bill. The combination of a FERS annuity, a military pension where applicable, Social Security benefits, and TSP Required Minimum Distributions beginning at age 73 can push MAGI into IRMAA territory even without a one-time liquidity event.
Federal and military retirees in Harford County often underestimate this stacking effect because each income source feels modest individually. A $36,000 FERS annuity, a $24,000 military pension, $28,000 in Social Security, and a $40,000 first-year TSP RMD combine to $128,000 of individual MAGI — above the Tier 1 IRMAA threshold for a single filer. If a spouse has similar income, the joint MAGI pushes well into Tier 2 or higher.
Pre-retirement IRMAA projection for this group needs to account for the full stack, not just the primary pension source. That projection is possible three to five years before Medicare enrollment, which is when it is still actionable.
I have worked with multiple Aberdeen Proving Ground families on exactly this situation. The planning levers available — TSP Roth conversions in the last working years, withdrawal sequencing from taxable accounts, QCD planning — are more powerful the earlier they are modeled.
Frequently Asked Questions
What is IRMAA and who pays it?
IRMAA is the Income-Related Monthly Adjustment Amount, an additional Medicare premium charged to beneficiaries whose modified adjusted gross income exceeds defined thresholds. In 2026, about 8% of Part B enrollees pay IRMAA. It is assessed per person, regardless of which spouse's income primarily drove the elevated MAGI, and covers both Part B and Part D premiums.
How does the two-year lookback for IRMAA work?
The Social Security Administration uses the most recent certified tax return when it sets premiums each fall. For 2026 Medicare premiums, that is your 2024 tax return. This means income decisions from two years ago: a business sale, a large Roth conversion, a capital gain, show up in today's Medicare bill with no ability to change the outcome. Planning must happen before the income year closes.
What income counts toward IRMAA MAGI?
MAGI for IRMAA purposes is your Adjusted Gross Income plus tax-exempt interest. It includes wages, traditional IRA and 401(k) distributions, taxable Social Security, Roth conversions, capital gains, pension income, rental income, and deferred compensation payouts. Qualified Roth IRA distributions do not count, which is one reason Roth balances are strategically valuable in retirement income planning.
Can I appeal an IRMAA surcharge?
Yes. Form SSA-44 allows you to request reconsideration when a qualifying life-changing event has permanently reduced your income. Qualifying events include retirement or work reduction, divorce, death of a spouse, and loss of income-producing property. You must file within 60 days of receiving the IRMAA notice, and you need documentation of the event and your new income level. A one-time income spike without a structural income change does not qualify on its own.
Does IRMAA apply to Medicare Advantage plans?
Yes. The IRMAA surcharge applies to Part B and Part D premiums regardless of whether you are enrolled in Original Medicare or a Medicare Advantage plan. If your Medicare Advantage plan includes Part D coverage, the Part D IRMAA still applies and is billed separately by Medicare, not by your Advantage carrier. This is a common misconception that leads to surprise bills among MA enrollees.
How much can IRMAA add to Medicare costs over a decade of retirement?
For a married couple in the fourth IRMAA bracket with both spouses enrolled in Medicare, the annual Part B surcharge is approximately $10,711 above the standard rate. Over ten years at that bracket, that is over $107,000 in additional Medicare costs from Part B alone, before Part D IRMAA is added. This is not a marginal line item. It belongs in any serious retirement income projection for a high-net-worth household.
Can Roth conversions reduce IRMAA exposure?
Roth conversions in the right years can significantly reduce IRMAA exposure. Conversions executed before age 63 are the last ones that will not affect Medicare premiums. Conversions in the pre-Medicare gap years — when earned income has stopped but RMDs have not begun — shift pre-tax balances to Roth at lower tax rates while reducing future RMD income that would otherwise push MAGI into higher IRMAA tiers. When does a Roth conversion make financial sense and how do you execute it?
Work With a Planner Who Maps the Medicare Premium Before the Income Year Closes
IRMAA is not a surprise to a planner who includes it in the retirement income model. It is a predictable function of financial planning decisions made two years before the bill arrives. Chesapeake Financial Planners works with pre-retirees across Harford County and the Baltimore metro area to build that forward projection before large income events are executed.
If you are approaching Medicare eligibility and have a Roth conversion, business sale, or large capital gain on the horizon, schedule a call to run the IRMAA numbers before the income year closes.
This post is adapted from 'Medicare Surcharge Hits High Earners Two Years Late' originally published on Chesapeake Financial Planners' LinkedIn.
Want to go deeper? Our Medicare and Social Security Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


