
What Is the Bucket Strategy for Retirement Income?
Last reviewed: July 2026
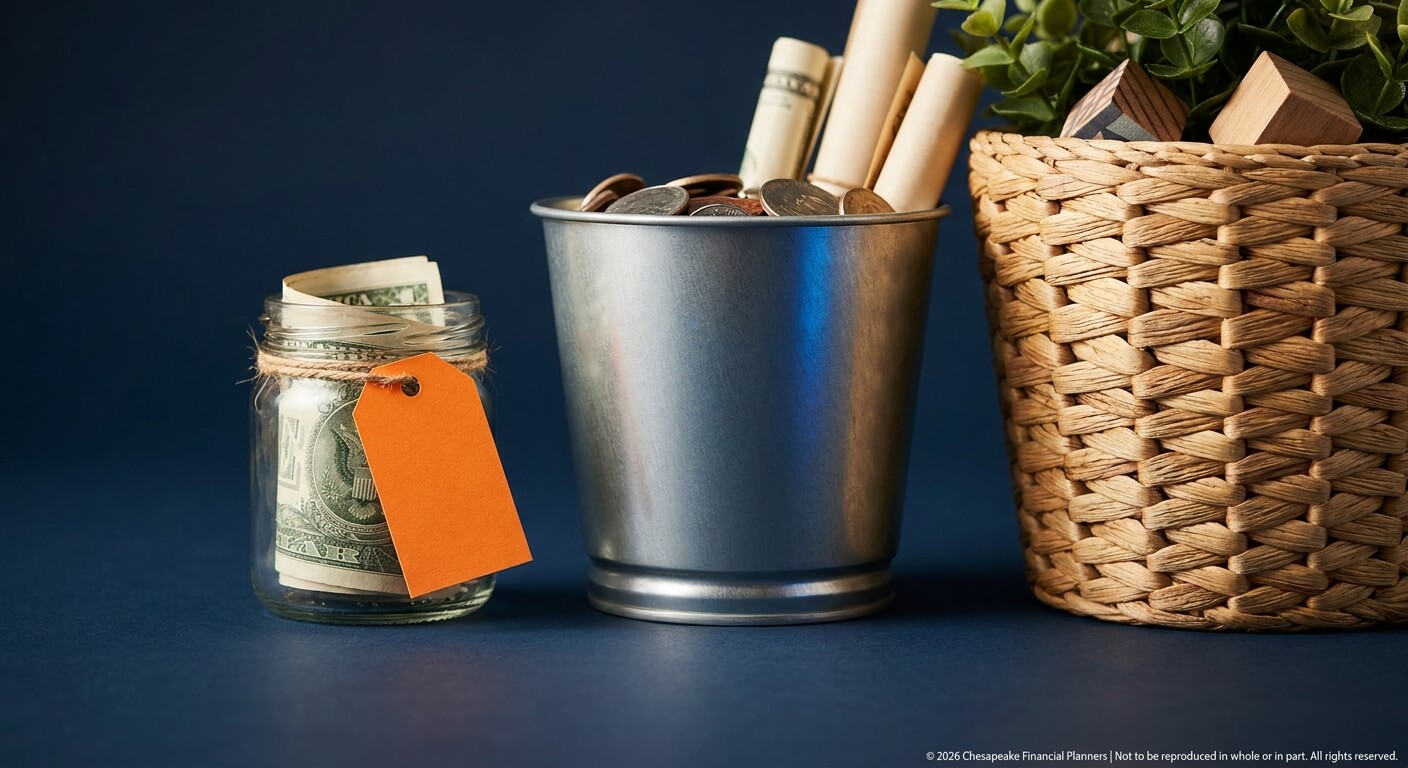
The bucket strategy retirement approach is a method of dividing your retirement savings into separate "buckets" based on when you'll need the money. A short-term cash bucket covers your first one to two years of expenses, a mid-term bucket holds bonds and conservative investments for years three through ten, and a long-term bucket stays invested in stocks for growth. The goal is simple: keep the money you'll spend soon out of the market so a bad year doesn't force you to sell investments at a loss.
Key Takeaways
- The bucket strategy retirement approach splits savings into short, medium, and long-term pools based on when you'll spend the money.
- The cash bucket typically holds one to two years of living expenses to avoid selling stocks in a downturn.
- Sequence-of-returns risk is highest in the first five years of retirement, which is exactly when this strategy helps most.
- In 2026, the IRS requires retirees to begin RMDs at age 73, which affects how you refill buckets.
- The strategy is a framework, not a rule. The right number of buckets depends on your spending and risk tolerance.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement income decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has noticed that the clients who sleep best in retirement aren't the ones with the biggest portfolios. They're the ones who know exactly where next year's grocery money is coming from.
How Does the Bucket Strategy Work in Retirement?
The bucket strategy retirement approach divides your nest egg into three pools, each matched to a different time horizon. You spend from the first bucket, and the other two refill it over time. This keeps your day-to-day income separate from the part of your portfolio that needs to grow.
Here's how the three buckets typically break down:
- Bucket 1 (Cash, years 1-2): Holds one to two years of living expenses in high-yield savings, money market funds, or short-term CDs. This is the money you actually spend. It doesn't move with the stock market.
- Bucket 2 (Income, years 3-10): Holds bonds, bond funds, and conservative dividend payers. This bucket refills Bucket 1 as it's drawn down and provides stability in the middle stretch of retirement.
- Bucket 3 (Growth, years 10+): Stays invested in stocks. Because you won't touch this money for a decade or more, it can ride out market downturns and keep growing.
When stocks have a good year, you trim gains from Bucket 3 to top off Buckets 1 and 2. When stocks fall, you leave Bucket 3 alone and live off cash and bonds instead. That's the whole point. You buy yourself time so you're never forced to sell shares in a down market.
Jeff Judge often tells clients that the buckets aren't really about investing. They're about behavior. When the market drops 20%, the retiree with a full cash bucket doesn't panic, because they know their income is covered for the next two years. That calm is worth more than a fraction of a percent in returns.
What is the best order to withdraw from my 401k, Roth IRA, and taxable accounts in retirement?
Why Does the Bucket Strategy Help With Sequence-of-Returns Risk?
The single biggest threat to a new retiree isn't a low average return. It's a bad return at the wrong time. This is called sequence-of-returns risk, and the retirement bucket approach is built to handle it.
Here's the problem in plain terms. If the market drops sharply in your first few years of retirement and you're selling investments to pay your bills, you lock in those losses permanently. You're selling more shares at lower prices, which means there's less left to recover when the market eventually bounces back. Research from Morningstar shows that the order of returns matters far more in the years right around retirement than at any other point in your life. Jeff Judge notes: "Retiring into a down market and selling growth assets to cover living expenses is one of the most damaging things that can happen to a portfolio, which is why having one to two years of cash set aside means you never have to sell at the worst possible moment."
Two retirees can earn the exact same average return over 30 years and end up with wildly different outcomes, simply because one got hit with a downturn in year two and the other got hit in year twenty. The cash bucket is your buffer. It lets you ride out the bad years without selling growth assets.
The Bureau of Labor Statistics reports that the Consumer Price Index continues to rise year over year, which is another reason the growth bucket matters. According to the Social Security Administration, the 2026 cost-of-living adjustment was 2.8%, which rarely covers a retiree's full spending growth. You need stocks working for you over a long retirement to keep your purchasing power intact.
This is where the R.U.D.D.E.R. Method™ comes in. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Designing a bucket structure happens in the Design and Develop step, where the size of each bucket gets matched to your actual spending and risk tolerance, not a generic rule of thumb.
How Does a Financial Plan Actually Get Built?
How Much Should Go in the Cash Bucket?
The cash bucket should generally hold one to two years of living expenses, though the right amount depends on your other income sources. If you have a pension and Social Security covering most of your fixed costs, you may need a smaller cash bucket. If your portfolio is doing all the heavy lifting, you'll want more.
Start by calculating your annual spending, then subtract any guaranteed income. According to the Social Security Administration, the maximum Social Security benefit at full retirement age in 2026 is $4,152 per month, and the average retired worker benefit is roughly $2,000 per month. Whatever that covers, your buckets need to fill the gap.
A common mistake Jeff sees is retirees who keep far too much in cash out of fear. Holding five or six years of expenses in a savings account feels safe, but it drags down your long-term returns and exposes you to inflation. The cash bucket is a buffer, not a vault. There's a version of being too cautious that quietly costs you a comfortable retirement, and overfilling the cash bucket is one of the most common.
How do I coordinate all my retirement income sources to minimize taxes and maximize income?
How Do RMDs Affect the Bucket Strategy?
Required minimum distributions force you to pull money from tax-deferred accounts whether you need it or not, and they directly affect how you refill your buckets. Once RMDs begin, that mandatory withdrawal often becomes the natural source for topping off your cash bucket each year.
The IRS requires retirees to begin taking RMDs at age 73 as of 2026. If you don't need the full RMD for spending, you don't have to waste it. You can reinvest it in a taxable account that becomes part of your bucket structure, or use it for Roth conversions in lower-income years.
Coordinating RMDs with your bucket refills is where a lot of value gets created or lost. Pull from the wrong account in the wrong year and you can push yourself into a higher tax bracket or trigger higher Medicare premiums. This is exactly the kind of decision that benefits from a written plan rather than a reflex.
Should I max out my 401(k) or invest somewhere else?
Frequently Asked Questions
What is the bucket strategy for retirement income?
The bucket strategy for retirement income divides your savings into separate pools based on when you'll need the money. A cash bucket covers near-term expenses, a bond bucket covers the medium term, and a stock bucket grows for the long term. This structure protects you from selling investments at a loss during a market downturn.
How many buckets should I have in retirement?
Most retirees use three buckets: cash for years one to two, bonds for years three to ten, and stocks for the long term. Some people use only two buckets to keep things simple, while others add a fourth for legacy or healthcare goals. The right number depends on your spending, income sources, and how much complexity you want to manage.
Is the bucket strategy better than the 4% rule?
The bucket strategy and the 4% rule solve different problems, so it's less about better and more about pairing them. The 4% rule tells you roughly how much to withdraw, while the bucket strategy tells you which assets to pull from and when. Many retirees use a withdrawal rate to set the budget and buckets to manage market risk.
What goes in the cash bucket?
The cash bucket holds one to two years of living expenses in safe, liquid accounts. This typically means high-yield savings accounts, money market funds, and short-term CDs. The point is stability and access, not growth, so you never have to sell stocks in a down market to cover your bills.
When do you refill the buckets?
You typically refill the cash bucket annually, pulling from your bond or stock bucket depending on market conditions. In strong market years, you trim gains from stocks to refill cash and bonds. In down years, you leave stocks alone and live off cash, giving the market time to recover before you sell.
Does the bucket strategy protect against inflation?
The bucket strategy protects against inflation through its long-term growth bucket. The stock allocation is designed to outpace rising prices over a multi-decade retirement. The cash and bond buckets don't keep pace with inflation, which is exactly why you keep only a couple years of spending there rather than your whole portfolio.
The bucket strategy retirement approach gives you a clear, repeatable way to turn a lifetime of savings into a paycheck you can count on. If you want a deeper framework for building retirement income that lasts, our retirement income guide walks through drawdown, taxes, and timing in plain language. Download it at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


