
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Part of our guide: Should I Get a Trust or Is a Will Enough?
The most reliable probate avoidance strategies in Maryland are a funded revocable living trust, beneficiary designations on retirement and insurance accounts, and transfer-on-death registrations. Each one moves an asset outside the court process, so it passes directly to your heirs without months of delay, legal fees, or a public record of your estate. The right mix depends on what you own and how much control you want to keep over how your heirs receive it.
Key Takeaways
- A funded revocable living trust keeps your estate out of probate court and out of the public record entirely.
- Maryland probate fees scale with estate value and can reach thousands of dollars on larger estates.
- Beneficiary designations override your will, so an outdated form can send assets to the wrong person.
- In 2026, the federal estate tax exemption is $15 million per person, but Maryland's exemption is far lower.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched families lose more to a poorly funded trust than they ever would have spent setting one up correctly the first time.
What Is Probate and Why Should You Avoid It?
Probate is the court-supervised process of validating your will, paying your debts, and distributing what remains to your heirs after you die. In Maryland, the Register of Wills oversees it, and the process commonly takes six months to two years depending on the size and complexity of the estate.
Three costs make probate worth avoiding. First, time. Your assets are effectively frozen while the court works through inventory, creditor claims, and distribution. Second, money. Maryland charges a probate fee that scales with the value of the estate, and the Maryland Register of Wills publishes a fee schedule that climbs as the estate grows, on top of attorney and executor compensation. Third, privacy. Probate filings are public record. Anyone can pull the court file and see what you owned, what it was worth, and who inherited it.
Jeff often tells clients that the privacy issue is the one that finally moves people. The fees are annoying. The public airing of a family's financial life is what people genuinely want to prevent. For business owners especially, a public probate record can expose ownership details competitors would love to see. As the Consumer Financial Protection Bureau puts it, "Probate is a public process, and it can be expensive and lengthy."
Which Assets Go Through Probate, and Which Avoid It Automatically?
Assets titled only in your name go through probate, while assets with a named beneficiary or a surviving co-owner pass automatically outside it. Knowing which bucket each asset falls into is the starting point, because the goal is to move as much as possible into the second bucket.
Probate generally applies to real estate titled in your name alone, individual bank and investment accounts, vehicles in your name only, and personal property such as furniture and collectibles. These have no built-in way to transfer at death, so the court steps in to decide where they go.
Assets that skip probate automatically include jointly owned property with right of survivorship, accounts with beneficiary designations such as retirement plans and life insurance, anything held in a revocable living trustA trust you create and maintain full control over during your lifetime, with assets transferring seamlessly to heirs at death — bypassing probate. You can change or dissolve it at any time, though unlike an irrevocable trust, it doesn't offer estate tax reduction or creditor protection., and transfer-on-death or payable-on-death accounts.
How Does a Revocable Living Trust Avoid Probate?
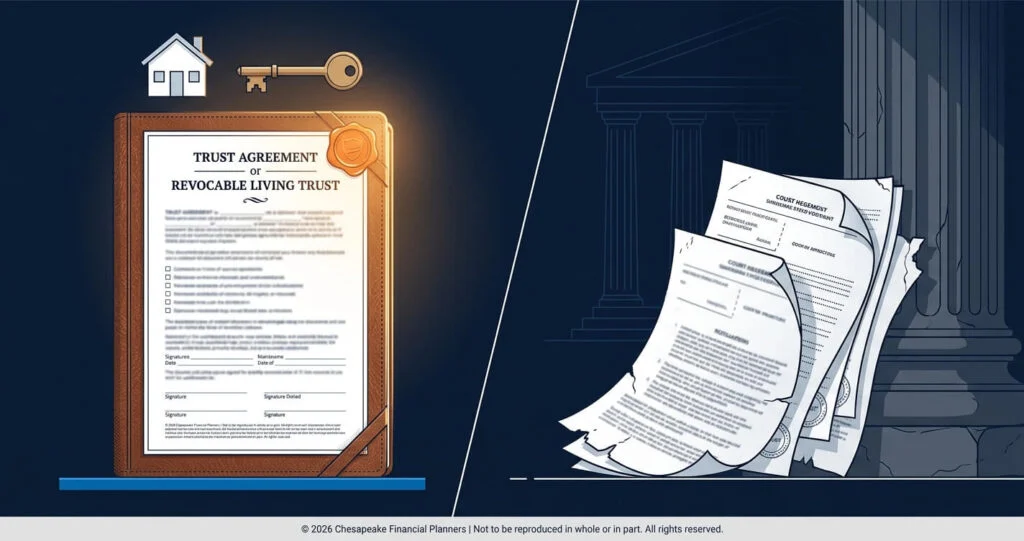
A revocable living trust is the cornerstone of most serious probate avoidanceLegal strategies that allow assets to transfer directly to heirs without going through the court-supervised probate process. Techniques include beneficiary designations, joint tenancy, revocable living trusts, and transfer-on-death accounts — all of which can save your family time, money, and public scrutiny. plans. You create the trust, transfer your assets into it, and serve as your own trustee during your lifetime, so you keep complete control. Because the trust owns the assets rather than you personally, there is nothing in your individual name to probate when you die.
When you pass, your named successor trustee steps in and distributes assets according to your written instructions. No court. No public filing. No waiting period before your family can act. This is why a properly funded trust is among the most effective revocable living trust probate avoidance strategies available to Maryland families.
The catch is funding. A trust only protects the assets you actually retitle into it. Assets to move in usually include your primary and vacation homes, brokerage and bank accounts, business interests, and valuable personal property such as art or collectibles. A trust document sitting in a drawer with no assets inside it does nothing. According to the American Bar Association, an unfunded revocable trust fails to avoid probate precisely because the assets remain titled in the individual's name.
What is a will and do I need one for my estate?
How Do Beneficiary Designations Help You Avoid Probate Court?
Beneficiary designations let certain accounts pass directly to the people you name, skipping probate entirely. Retirement accounts, life insurance, annuities, and many brokerage and bank accounts all allow them, and the designation overrides whatever your will says.
Payable-on-death (POD) designations on bank accounts have a second benefit: the FDIC insures these accounts up to $250,000 per eligible beneficiary, to a maximum of $1,250,000 per owner at the same bank, which can expand coverage on a larger balance.
Review and update beneficiariesThe people or entities designated to receive your assets when you die — through retirement accounts, life insurance policies, or trusts. Keeping beneficiary designations current is one of the simplest but most overlooked parts of estate planning, and outdated designations can completely override what your will says. regularly on your 401(k) and 403(b) plans, traditional and Roth IRAs, life insurance policies, annuities, transfer-on-death brokerage accounts, and payable-on-death bank accounts. The single most common mistake Jeff Judge sees is naming your estate as the beneficiary, which forces those assets straight into probate and, for retirement accounts, can compress the payout timeline for your heirs.
There is a real tax dimension here too. Under the SECURE Act, most non-spouse beneficiaries must empty an inherited IRA within 10 years, which changes how large IRAs should be structured. For high-net-worth families, naming a properly drafted trust as the beneficiary of retirement accounts or life insurance can preserve control, add creditor protection, and coordinate with estate tax planning Maryland residents need to address.
Do I need to update my beneficiary designations after a divorce or major life change?
What Are the Risks of Joint Ownership and Transfer-on-Death Tools?
Joint ownership with right of survivorship and transfer-on-death registrations both avoid probate, but each carries trade-offs that make them poor substitutes for a trust in larger estates. They work, but they remove control and can create tax surprises.
Property held in joint tenancy with right of survivorship passes automatically to the surviving owner, which is why most married couples hold their home this way. The drawbacks show up when you add a non-spouse to the title:
| Concern | Joint Ownership | Transfer-on-Death (TOD/POD) |
|---|---|---|
| Avoids probate | Yes | Yes |
| Control during life | Shared with co-owner | You keep full control |
| Creditor exposure | Co-owner's creditors can attach | None until death |
| Control over how heirs receive assets | None | None |
| Gift tax risk | Adding a non-spouse may be a taxable gift | None |
| Step-up in basis | Only half steps up at first death (non-spouse) | Full step-up |
Adding a non-spouse to a valuable asset can trigger gift tax consequences. The 2026 federal annual gift tax exclusion is $19,000 per recipient, and transfers above that erode your lifetime exemption. Transfer-on-death deeds and payable-on-death bank accounts are simple and usually free, but they give you zero say over how or when beneficiaries receive the money, and they offer no protection from a beneficiary's creditors or divorce.
Jeff's rule of thumb with clients: use joint ownership and TOD tools deliberately, never as the backbone of a real plan. They are fine for convenience accounts and a marital home. They are not a replacement for a funded trust when meaningful wealth or a blended family is involved.
How Do I Protect My Children's Inheritance in a Blended Family?
How Do You Build a Complete Probate-Avoidance Plan?
You build a complete plan by assigning the right transfer tool to each asset, then confirming nothing is left titled in your name alone. For illustration only, a layered plan might look like this:
| Asset | Probate-avoidance tool |
|---|---|
| Primary residence | Revocable living trust (or a transfer-on-death deed where the state allows) |
| Bank accounts | Payable-on-death to spouse, then children |
| Brokerage accounts | Transfer-on-death to spouse, then children |
| Retirement accounts | Named primary and contingent beneficiaries |
| Life insurance | Direct beneficiaries, or a trust if heirs are minors |
One mistake worth checking for is forgetting contingent beneficiaries. If your primary beneficiary dies before you, the asset falls back into your estate and into probate anyway.
This table is general education, not individualized advice. Estate planning requires legal assistance. Neither LPL Financial nor its registered representatives offer legal advice.
Where Does Maryland Estate Tax Fit Into Probate Planning?
Avoiding probate and avoiding estate taxA federal (and sometimes state) tax on the transfer of assets to heirs at death, assessed on the total estate value above the applicable exemption. The federal exemption is $15 million per person in 2026: the 2025 law known as the One Big Beautiful Bill Act set it at that level, indexed for inflation after 2026, with no scheduled sunset. are two different goals, and confusing them costs Maryland families real money. Probate avoidance controls how assets transfer. Estate tax planning controls how much the state and federal government take along the way.
In 2026, the federal estate tax exemption is $15 million per individual. Maryland's estate tax exemption sits far lower at $5 million, according to the Comptroller of Maryland, which means estates that owe nothing federally can still face a Maryland estate tax bill. Maryland also imposes a separate 10% inheritance tax on assets passing to certain non-lineal heirs.
This is where the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, earns its keep. Probate avoidance is one piece of a coordinated plan, not the whole plan.
Who owes Maryland's 10% inheritance tax and what planning options protect non-lineal heirs?
How can I potentially optimize my taxes as my income grows?
Frequently Asked Questions
Does a will avoid probate in Maryland?
No, a will does not avoid probate in Maryland. A will is the document that tells the probate court how to distribute your estate, which means it actually guarantees the probate process rather than preventing it. To skip probate, you need tools like a funded revocable living trust or direct beneficiary designations that transfer assets outside the court.
How much does probate cost in Maryland?
Maryland probate costs include a Register of Wills probate fee that scales with the gross value of the estate, plus attorney fees and executor compensation. The Maryland probate fee schedule increases as the estate grows in value. Larger estates can lose thousands of dollars to combined court, legal, and administrative costs before heirs receive anything.
Is a revocable living trust worth it for a smaller estate?
A revocable living trust can be worth it even for a smaller estate when privacy, real estate in multiple states, or a blended family is involved. The benefit is not only avoiding fees but keeping your affairs off the public record and giving a successor trustee immediate authority. The right answer depends on what you own and your family situation.
What happens if I create a trust but never fund it?
If you create a trust but never fund it, the trust accomplishes nothing and your assets still go through probate. Funding means retitling your home, accounts, and property into the trust's name. This is the most common and costly mistake in do-it-yourself estate planning, because the document exists but controls no assets at death.
Do beneficiary designations override my will?
Yes, beneficiary designations override your will. Assets like retirement accounts, life insurance, and transfer-on-death accounts pass directly to the named beneficiary regardless of what your will says. This is why an outdated designation, such as an ex-spouse left on a 401(k), can send a large asset to the wrong person despite a carefully drafted will.
Can I avoid both probate and Maryland estate tax with the same plan?
You can address both in one coordinated plan, but they require different tools. Probate avoidance uses trusts and beneficiary designations to control how assets transfer. Reducing Maryland estate tax exposure, given the state's $5 million exemption, requires gifting strategies and trust structures aimed at lowering the taxable estate itself.
What is the easiest way to avoid probate?
The easiest way is usually to add beneficiary designations and transfer-on-death registrations to your accounts, which is free and takes minutes. Retirement accounts and life insurance already use beneficiaries; brokerage accounts can add a transfer-on-death (TOD) registration and bank accounts a payable-on-death (POD) one. These assets then pass directly to your named person at death, skipping the court process.
If avoiding probate is on your mind, the next step is understanding how all these pieces fit together for your specific estate. Our estate planning guide walks through the funding, beneficiary, and tax coordination steps in plain language. Download it at chesapeakefp.com to start building a plan that keeps your estate out of court and out of public view.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


