
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Part of our guide: What Are the Different Parts of Medicare and What Do They Cover?
Long-term care insuranceCoverage that pays for care you need due to chronic illness, disability, or cognitive decline — whether in a nursing home, assisted living facility, or at home. Without it, long-term care costs can rapidly deplete a retirement portfolio; the right answer for you depends on your health history, assets, and family support system. is a policy that pays for help with daily living tasks like bathing, dressing, and eating when you can no longer do them on your own. Medicare does not cover this kind of ongoing custodial care, which is exactly why long-term care insurance exists. You likely need some form of long-term care planning if you want to protect your retirement savings from a cost that can run into the hundreds of thousands of dollars.
Key Takeaways
- Long-term care insurance pays for custodial help with daily activities that Medicare and most health plans refuse to cover.
- Roughly 70% of people turning 65 today will need some form of long-term care.
- A private nursing home room runs a national median of about $129,575 per year, per CareScout's 2025 Cost of Care survey (formerly the Genworth survey).
- Hybrid life insurance policies let you fund care without the "use it or lose it" problem of traditional coverage.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate long-term care planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched a single uninsured care event quietly erase a decade of disciplined saving, and it almost always lands on the healthy spouse left behind.
What Is Long-Term Care Insurance?
Long-term care insurance is a contract that reimburses you for the cost of help with daily living when illness, injury, or cognitive decline makes independent living unsafe. It covers custodial care, the day-to-day assistance that health insurance and Medicare deliberately exclude.
Most policies pay benefits once you can no longer perform two of the six activities of daily living, or when you have a cognitive impairment like dementia. Those activities are bathing, dressing, eating, toileting, transferring, and continence. The care itself can happen almost anywhere: in your own home with a paid aide, in an assisted living facility, in a nursing home, or in an adult day program.
This is where long-term care planning starts. Care is not a single event. It is a slow shift in what you can manage alone, and the policy bridges the gap when that shift arrives.
Do I Actually Need Long-Term Care Insurance?
Most people will need long-term care, so the real question is how you plan to pay for it. According to the U.S. Administration for Community Living, about 70% of people turning 65 today will need some type of long-term care, the average person needs that care for roughly three years, and about 20% will need it for longer than five years. Women tend to need more care than men because they live longer.
You may not need insurance if you have enough liquid assets to self-fund a multi-year care event without derailing a surviving spouse. You probably do need a plan if a large care bill would force the sale of a home, drain a retirement account, or shift the burden onto your adult children.
Jeff Judge often tells clients the decision is rarely about the person buying the policy. It is about protecting the spouse or family member who would otherwise pay the price, in dollars and in unpaid caregiving hours. That framing changes the math for a lot of couples.
Long-term care insurance tends to make the most sense for people in the financial middle: enough assets to be worth protecting, but not enough to self-fund years of care comfortably. If your assets are below that range, Medicaid may become the realistic backstop, though it generally requires meeting state eligibility limits, which often means spending down most of what you have first, and it limits your choice of facilities. Medicare.gov notes that Medicaid may cover long-term care for those who meet their state's requirements, and our guide to the Medicaid look-back period explains why timing matters. If your assets are well above that range, you may decide to self-insure and earmark part of your portfolio for potential care costs. Timing matters too: people often apply in their mid-50s to early 60s, while they are still healthy enough to qualify.
How Much Does Long-Term Care Cost Without Insurance?
Long-term care is one of the largest unfunded risks in retirement, and the numbers explain why. CareScout's 2025 Cost of Care survey (formerly the Genworth survey) puts the national median annual cost of a private room in a nursing home at roughly $129,575, with a semi-private room near $114,975. Assisted living runs about $74,400 per year, and non-medical caregiver services, which include homemaker and home health aide care, come to about $80,080 annually based on 44 hours of care per week. The 2025 survey does not list homemaker services and home health aide services as separate lines, so this post does not state separate figures for them.
| Type of care | National median annual cost |
|---|---|
| Non-medical caregiver (homemaker and home health aide care, 44 hours per week) | ~$80,080 |
| Assisted living facility | ~$74,400 |
| Nursing home (semi-private room) | ~$114,975 |
| Nursing home (private room) | ~$129,575 |
In higher-cost states, those figures can run 40% to 60% above the national median. Stretch a care event across three to five years and the total can climb past $300,000, even more in expensive markets. For most households, that is a meaningful share of everything they spent a working lifetime saving. This is where long-term care planning and retirement planning Maryland families do has to connect, because nursing home costs and assisted living costs don't respect a portfolio's withdrawal rate.
These are medians, which means half of all care costs more, and costs vary sharply by region. Costs have tended to rise most years, which is why many policies offer an inflation protection rider.
Why Doesn't Medicare Cover Long-Term Care?
Medicare does not pay for long-term custodial care, which is the single most common and most expensive misunderstanding in retirement. Medicare covers skilled nursing care for short stretches, up to 100 days following a qualifying hospital stay, and some home health services if you are homebound and need skilled care. It does not cover ongoing help with bathing, dressing, or eating, which is exactly the care most people end up needing.
Medicaid does cover long-term care, but only after you have spent down nearly all of your assets to qualify. That is not a plan most families want to default into. Closing this gap is one of the core problems the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process, is built to surface before it becomes a crisis.
What Are My Options for Funding Long-Term Care?
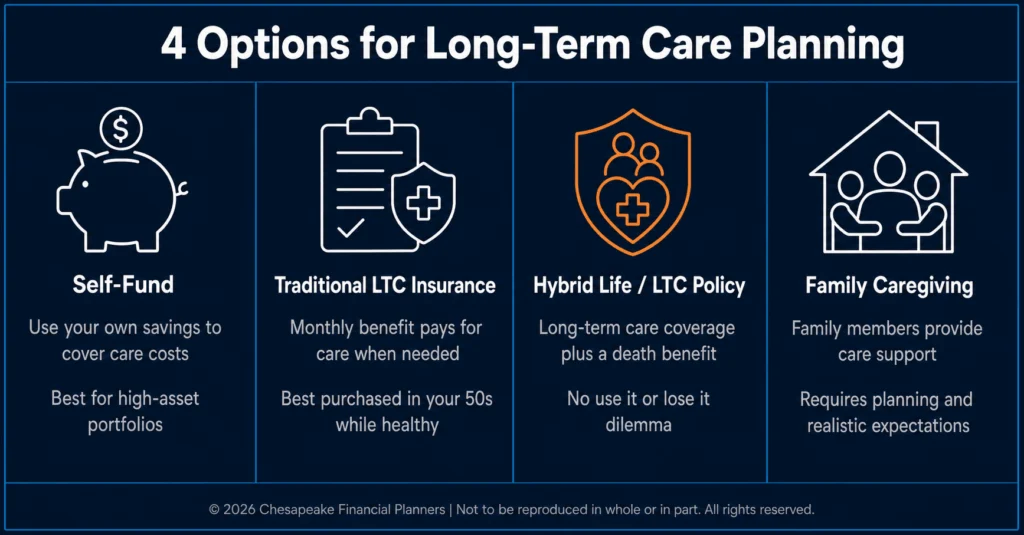
You have three broad paths, and most solid plans blend them. The first is traditional long-term care insurance, which offers the most coverage per premium dollar but comes with "use it or lose it" risk and premiums that can rise over time. The second is hybrid life insurance, a policy that combines a death benefit with a long-term care rider, so your money is never wasted whether you need care or not. The third is self-funding, setting aside dedicated assets to pay for care directly.
Hybrid life insurance has become popular for a reason. If you never need care, your heirs receive the death benefit. If you do need care, the policy advances those funds while you are alive. Jeff has seen this option ease the resistance of clients who hated the idea of paying premiums for coverage they might never use.
There are also non-insurance strategies worth weighing, from health savings accounts to annuities with care riders. Comparing these honestly is the whole game.
Frequently Asked Questions
What does long-term care insurance actually pay for?
Long-term care insurance pays for custodial help with daily activities such as bathing, dressing, eating, toileting, and moving around. It can reimburse care delivered at home, in assisted living, or in a nursing home. Most policies begin paying once you cannot perform two of six daily activities or have a cognitive impairment.
How likely am I to need long-term care?
You have roughly a 70% chance of needing some form of long-term care if you are turning 65 today, according to the U.S. Administration for Community Living. The average person needs care for about three years, and about one in five people will need it for more than five years. Women generally need more care than men because they live longer.
Why won't Medicare pay for my long-term care?
Medicare does not pay for long-term custodial care because the program covers only short-term skilled care, not ongoing help with daily living. Medicare will cover up to 100 days of skilled nursing after a hospital stay and some skilled home health services. Everything beyond that, including most assisted living and nursing home stays, falls on you, insurance, or Medicaid.
What is hybrid life insurance for long-term care?
Hybrid life insurance combines a permanent life insurance death benefit with a long-term care rider that you can tap while living. If you need care, the policy advances funds to cover it; if you never need care, your heirs receive the death benefit. This solves the "use it or lose it" objection many people have to traditional long-term care insurance.
How much does a nursing home cost per year?
A private room in a nursing home costs a national median of roughly $129,575 per year, and a semi-private room runs about $114,975, based on CareScout's 2025 Cost of Care survey (formerly the Genworth survey). Assisted living averages near $74,400 annually. In high-cost states, these figures can run 40% to 60% higher.
Can I just self-fund long-term care instead of buying insurance?
You can self-fund long-term care if you have enough liquid assets to absorb a multi-year care event without harming a surviving spouse or forcing the sale of your home. The risk is duration: a five-year care event can exceed $300,000 and erode a retirement plan built for decades. Self-funding works best as part of a deliberate strategy, not as a default.
Can I just rely on Medicaid for long-term care?
You can, but Medicaid generally requires you to spend down most of your assets first and limits your choice of facilities to those that accept Medicaid. According to KFF, Medicaid is the largest single payer of long-term care in the country, covering about 61% of U.S. spending on long-term services and supports in 2022. For people with assets to protect, planning ahead with insurance may preserve more choice than relying on Medicaid as the default.
When is the best age to buy long-term care insurance?
The window is often described as the mid-50s to early 60s. Buying in this range can balance lower premiums against the risk of being declined for health reasons later, and waiting may cost you the option entirely if your health changes.
Where to Go From Here
The mistake most people make is treating long-term care as a someday problem instead of a decision with a real deadline. Premiums and eligibility both get worse the longer you wait, and care arrives without an invitation. If you want to understand which approach fits your situation, our guide on What Are the Best Alternatives to Long-Term Care Insurance? walks through the trade-offs in detail. You can also see how care costs fit into the bigger picture in our resource on How Much Should I Budget for Healthcare Costs in Retirement?, review how care decisions tie into How Do I Help Aging Parents Financially Without Ruining My Retirement?, and connect it all to What Should You Prioritize Financially in the 5 Years Before Retirement?. Download our retirement planning guide at chesapeakefp.com to map out long-term care insurance before you need it.
Want to go deeper? Our 10 Signs You're Ready for a Certified Financial Planner walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


