
Should I Take Social Security at 62 or Wait Until 70?
Last reviewed: July 2026
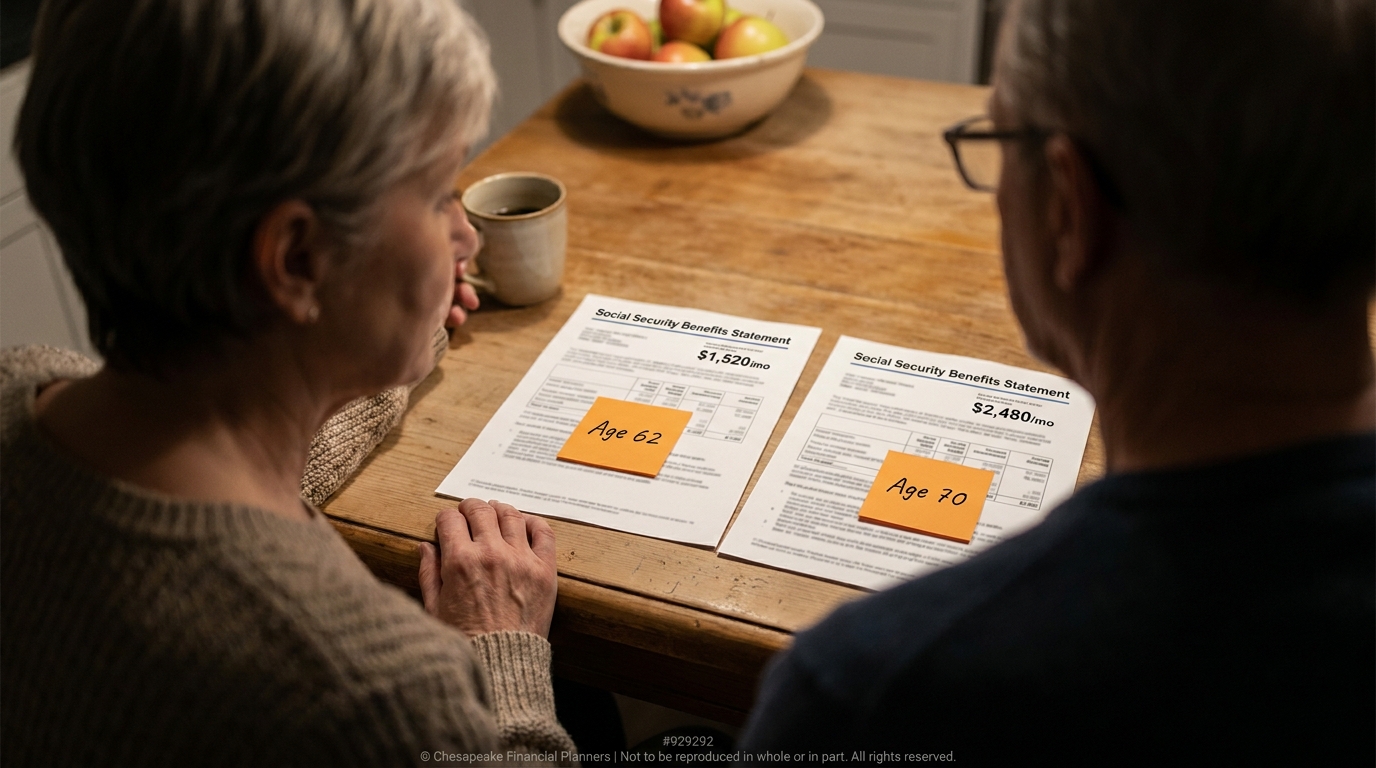
Claiming Social Security at 62 gives you a smaller check now; waiting until 70 gives you a much larger check later. The right answer depends mostly on three things: how long you expect to live, whether you have other income to bridge the gap, and whether a spouse will depend on your benefit after you're gone. For a healthy married couple where one person was the higher earner, delaying the larger benefit to 70 is often the single most valuable retirement income decision available. For a single person in poor health, claiming at 62 frequently wins.
On This Page
- Key Takeaways
- Understanding the Social Security Claiming Timeline
- What Does Claiming at 62 Actually Cost You?
- When Does Claiming Social Security at 62 Make Sense?
- When Is Waiting Until 70 the Better Move?
- What About Claiming at Full Retirement Age?
- How Do Married Couples Coordinate Claiming Decisions?
- How Taxes, Medicare, and the Earnings Test Change the Math
- Frequently Asked Questions
- Where This Leaves You
- Disclosures
Key Takeaways
- Claiming Social Security at 62 reduces your benefit by up to 30% for life; waiting until 70 raises it by up to 77%.
- The Social Security Administration adds 8% in delayed retirement credits for each year you wait past full retirement age, up to age 70.
- Most people who delay from 62 to 70 break even on total lifetime benefits somewhere around age 80 to 82.
- For married couples, the higher earner's claiming age sets the survivor benefit your spouse keeps for life.
- Full retirement age is 67 for anyone born in 1960 or later, the dividing line between reduced and increased benefits.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate Social Security and retirement income decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's take: most people obsess over the breakeven math and ignore the part that matters more, which is that Social Security is the only inflation-protected paycheck you can't outlive, and for a married couple it doubles as life insurance on the higher earner's benefit.
Understanding the Social Security Claiming Timeline
Your monthly Social Security benefit is built around one number: your full retirement age, or FRA. For anyone born in 1960 or later, the Social Security Administration sets FRA at 67. Claim before that age and your benefit shrinks. Claim after it and your benefit grows. The system is designed to pay roughly the same lifetime total to someone with average life expectancy, no matter when they file. The catch is that almost nobody is "average," and the differences add up fast.
How much does each year of waiting change your check?
Every month between 62 and FRA carries a reduction. Every month between FRA and 70 carries a bonus. Here's the shape of it for someone with an FRA of 67:
| Claiming age | Effect on your FRA benefit |
|---|---|
| 62 (earliest) | Reduced by about 30% |
| 65 | Reduced by about 13.3% |
| 67 (full retirement age) | Full benefit, no adjustment |
| 68 | Increased by 8% |
| 70 (latest worthwhile) | Increased by 24% over FRA, up to 77% over the age-62 amount |
The delayed retirement credit is 8% per year, or two-thirds of one percent per month, according to the Social Security Administration. That 8% is guaranteed and inflation-adjusted, which is a return profile you cannot buy anywhere else. One thing worth saying plainly: benefits stop growing at 70. There is no reason to wait past your 70th birthday. If you blink and you're 71 and haven't filed, file immediately. You're leaving money on the table every month.
The cost-of-living adjustment matters here too. The Social Security Administration applied a 2.8% COLA for 2026, and those adjustments compound on whatever base benefit you've locked in. A bigger base benefit means bigger COLAs in raw dollars for the rest of your life. Jeff Judge often points out to clients that this compounding effect is invisible on the day you claim but enormous over a 25-year retirement.
What Does Claiming at 62 Actually Cost You?
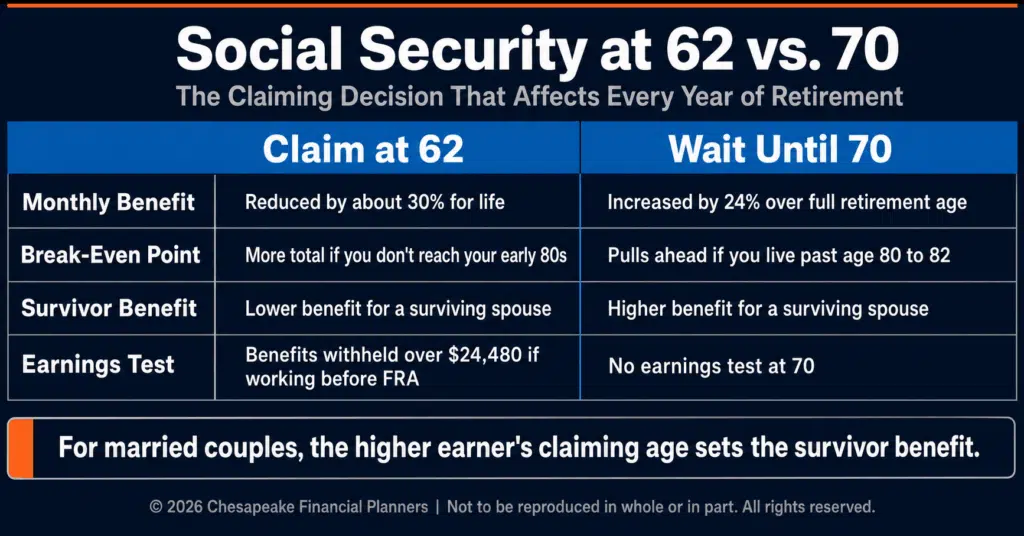
Claiming Social Security at 62 locks in a benefit reduced by up to 30% compared to your full retirement age amount, and that reduction is permanent. The check you take at 62 is the check you keep, adjusted only for annual COLAs, for the rest of your life. There is no do-over after the first 12 months.
Is the reduction really permanent?
Yes, with one narrow exception. The reduction at 62 sticks for life. The only meaningful escape hatch is the "withdrawal of application," which the Social Security Administration allows just once and only within 12 months of filing, and it requires you to repay every dollar you've received. After that window closes, the reduced benefit is set in stone.
Three costs ride along with an early claim, and people routinely underestimate the last two:
- A smaller monthly check for life. You'll receive roughly 25% to 30% less every month than you would at FRA. Over 25 years, that gap is measured in six figures for most middle-income earners.
- A smaller survivor benefit. If you're the higher earner in a marriage, your claiming age sets the floor for what your spouse receives after you die. Claim small at 62 and you've permanently capped your surviving spouse's income.
- The earnings test, if you keep working. For 2026, the Social Security Administration withholds $1 in benefits for every $2 you earn above $24,480 if you're under FRA all year. In the year you reach FRA, the limit jumps to $65,160 with a gentler $1-for-$3 withholding, and the test disappears entirely the month you hit FRA.
A common mistake Jeff sees: someone files at 62, keeps working a part-time job they enjoy, and is stunned when Social Security claws back benefits because of the earnings test. The withheld money isn't lost forever; your benefit is recalculated upward at FRA. But the cash-flow surprise in year one catches people off guard, and it usually means they filed too early for no good reason.
When Does Claiming Social Security at 62 Make Sense?
Claiming Social Security at 62 makes sense when you need the income to live, when your health or family history points to a shorter life expectancy, or when you're single with no survivor to protect. In those situations the larger check at 70 may never arrive or may not matter, and money in hand at 62 wins.
Who should seriously consider an early claim?
Four profiles tend to come out ahead claiming early. First, the person who simply needs the money. If a layoff, a health event, or thin savings means you can't cover expenses any other way, claiming at 62 isn't a strategy debate; it's survival, and that's a perfectly valid reason.
Second, the person in genuinely poor health or with a strong family history of shorter lifespans. The breakeven math is the deciding factor here. If you claim at 62 instead of waiting to FRA at 67, you'd typically need to live to roughly 78 to 80 to come out ahead by waiting. If you have real reason to doubt you'll reach that age, the early check is the rational choice, and you get to enjoy those dollars during years when your health still lets you.
Third, the single person with no spouse depending on a survivor benefit. Singles don't carry the survivor-benefit consideration that often tips married couples toward delaying. The decision collapses to a personal breakeven calculation based on health and longevity. We cover this fully in When Should Single People Claim Social Security Benefits?.
Fourth, the early retiree with no bridge income. If you stop working at 62 and have no pension, no sizable portfolio, and no part-time income to carry you to 70, claiming early may be the only way to fund your lifestyle without depleting what little you have.
The honest downside still applies to all four: a permanently reduced benefit, a smaller survivor benefit if you're married, and exposure to the earnings test if you keep working. Claiming at 62 should be a decision you make on purpose, not a default you back into.
When Is Waiting Until 70 the Better Move?
Waiting until 70 is the better move when you're healthy, expect to live into your 80s or beyond, have other income to live on in the meantime, or are the higher earner in a marriage protecting a surviving spouse. In those cases the 8% annual delayed retirement credit and the larger survivor benefit usually deliver far more lifetime income.
What's the strongest argument for waiting?
The strongest argument is longevity insurance. Social Security is one of the only sources of guaranteed, inflation-adjusted income that lasts as long as you do. By maximizing it, you're buying protection against the single risk that wrecks more retirements than market crashes: living longer than your money. Jeff Judge has watched clients agonize over portfolio returns while ignoring the fact that an extra few hundred dollars a month from Social Security, guaranteed and indexed to inflation, would have done more to protect their retirement than any fund selection.
Several conditions point toward delaying:
- You expect a long life. If you, or you and your spouse together, expect to reach your mid-80s or beyond, delaying typically breaks even around age 80 to 82 and then pulls ahead, often by six figures over a long retirement.
- You have bridge income. If savings, a pension, or part-time work can carry you to 70, every year you wait grows your benefit by 8% in guaranteed, COLA-protected dollars. Building that bridge is its own planning project, and we walk through it in How Do I Create Multiple Income Streams for Retirement?.
- You're the higher-earning spouse. Delaying maximizes the survivor benefit your spouse will live on after you're gone, which we'll cover in detail below.
- You want to hedge solvency uncertainty. Social Security isn't going bankrupt, but the trust fund faces a future shortfall if Congress doesn't act. Locking in a higher benefit doesn't immunize you from a system-wide change, but a larger base gives you more cushion.
The downside of waiting is real and worth naming. You give up eight years of checks between 62 and 70. If you die before the breakeven age, you'll have collected less in total. And you may have to draw harder on your portfolio in the meantime, which is its own tradeoff. The question of whether your savings can carry that load is exactly the kind of thing we model in How Do I Know If I'm On Track for Retirement?.
What About Claiming at Full Retirement Age?
Claiming at full retirement age, which is 67 for anyone born in 1960 or later, gives you 100% of your earned benefit with no reduction and no bonus. For people who want neither the permanent haircut of an early claim nor the wait-and-draw-down tradeoff of delaying to 70, FRA is the sensible middle ground.
Why do so many people land at FRA?
Because it removes two of the biggest frictions at once. At FRA the earnings test vanishes, so you can keep working and earning without Social Security withholding a dime, according to the Social Security Administration. You also stop locking in a reduced benefit. You're not capturing the full 24% bump that waiting to 70 delivers, but you're also not draining your portfolio for three extra years to get there.
FRA tends to suit the person who's stopped working, wants steady income now, and doesn't have a strong reason to believe they'll live exceptionally long or die exceptionally young. It's a reasonable default, not a cop-out. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and a claiming decision like this lives squarely in the "Uncover and Understand" and "Discuss and Decide" stages, where health, income sources, and family situation get mapped before anyone files paperwork.
How Do Married Couples Coordinate Claiming Decisions?
For married couples, the claiming decision is really two decisions that interact, and the most important variable is the survivor benefit. When one spouse dies, the survivor keeps the larger of the two benefits, not both. That single rule reshapes the entire strategy and usually argues for the higher earner delaying as long as possible.
What's the best claiming strategy for couples?
The most common winning pattern: the higher earner delays toward 70 to maximize the survivor benefit, while the lower earner may claim earlier to bring income into the household sooner. Because the survivor inherits the larger check, growing the higher earner's benefit protects whichever spouse lives longer, often the wife, given longevity differences.
| Strategy | Higher earner | Lower earner | Best for |
|---|---|---|---|
| Maximize survivor benefit | Delay to 70 | Claim at 62 to FRA | Couples with one dominant earner and a longevity expectation |
| Both delay | Delay to 70 | Delay to FRA or 70 | Couples with strong savings and long joint life expectancy |
| Both claim early | Claim at 62 | Claim at 62 | Couples needing income now or with health concerns |
Jeff Judge has sat across from too many widows who discovered, too late, that their late husband claimed at 62 and permanently shrank the only check they'd have for the next 20 years. The breakeven math for the higher earner shouldn't be run on that person's life expectancy alone; it should be run on the joint life expectancy of the couple, because that benefit may have to support the survivor for years after the first death. This coordination problem is the heart of How Should Married Couples Coordinate Social Security Claiming?.
How Taxes, Medicare, and the Earnings Test Change the Math
Your claiming decision doesn't happen in a vacuum. It collides with income taxes, Medicare premiums, and the earnings test, and ignoring those interactions is how people make a technically correct claiming choice that costs them money elsewhere.
Will my Social Security benefits be taxed?
Probably, at least in part. Depending on your combined income, up to 85% of your Social Security benefits can be subject to federal income tax, according to the Social Security Administration. The thresholds that trigger this taxation are not indexed to inflation, which means more retirees cross them every year. How and when you claim affects your taxable income, which can ripple into your Medicare premiums.
That Medicare ripple is the part most people miss. Higher income in a given year can push you into an IRMAA surcharge that raises your Medicare Part B and Part D premiums two years later. A poorly timed claim, a large Roth conversion, or a portfolio withdrawal can quietly trigger hundreds of dollars in extra premiums. We unpack that coordination in How does my Social Security claiming decision affect my Medicare premiums?.
The earnings test is the third moving part. As noted earlier, the Social Security Administration set the 2026 earnings limit at $24,480 for those under FRA all year, with $1 withheld for every $2 above it. If you're still working and thinking about claiming at 62, that test can erase much of your benefit in the near term, which is one more reason early claiming and continued full-time work rarely belong together. For where this fits into a broader plan, see How do I create sustainable retirement income streams? and How do I create reliable income from my retirement savings?. Jeff Judge notes: "If you're still pulling a full salary and you claim at 62, the earnings test can claw back so much of your benefit that you've taken on longevity risk in exchange for almost nothing in your pocket today."
Putting it together: the claiming question is never just "62 or 70." It's "how does this choice interact with my taxes, my Medicare premiums, my spouse's future income, and the rest of my retirement plan." That's why a clean breakeven chart, however satisfying, is usually the least important part of the analysis.
Frequently Asked Questions
How much less do I get if I take Social Security at 62?
Taking Social Security at 62 reduces your benefit by about 30% compared to your full retirement age amount if your FRA is 67. That reduction is permanent and applies for the rest of your life, adjusted only by annual cost-of-living increases. The exact percentage depends on your birth year and how many months early you claim.
What is the breakeven age between claiming at 62 and waiting until 70?
The breakeven age between claiming at 62 and waiting until 70 typically falls around age 80 to 82. If you live past that point, delaying to 70 produces more total lifetime benefits. If you don't expect to reach your early 80s, claiming earlier may give you more money over your lifetime. Your exact breakeven depends on your benefit amount and COLA assumptions.
Does my Social Security benefit keep growing after age 70?
No. Your Social Security benefit stops growing once you reach age 70, even if you keep delaying. The 8% annual delayed retirement credit only applies between your full retirement age and 70. There is no financial reason to wait past your 70th birthday, so you should file as soon as you reach that age if you haven't already.
Can I change my mind after I claim Social Security early?
You can change your mind only within a narrow window. The Social Security Administration allows a one-time withdrawal of application within 12 months of claiming, but you must repay all benefits you've received. After that 12-month window closes, your reduced benefit is permanent. There is no general option to undo an early claim once a year has passed.
How does claiming age affect my spouse's survivor benefit?
When you die, your surviving spouse keeps the larger of the two benefits, not both. If you're the higher earner, the age you claim sets the survivor benefit your spouse will live on. Claiming early at 62 permanently lowers that survivor benefit, while delaying to 70 maximizes the income your spouse keeps after you're gone.
Will I owe taxes on my Social Security benefits?
You may owe federal income tax on up to 85% of your Social Security benefits, depending on your combined income from all sources. The income thresholds that trigger this taxation are not adjusted for inflation, so more retirees become subject to it over time. Your claiming and withdrawal strategy directly affects how much of your benefit becomes taxable each year.
Should I claim Social Security at 62 if I'm still working?
Claiming Social Security at 62 while working full time is usually a poor choice because of the earnings test. In 2026, the Social Security Administration withholds $1 in benefits for every $2 you earn above $24,480 if you're under full retirement age all year. That can erase most of your benefit in the near term, making an early claim with continued work rarely worthwhile.
Is Social Security going to run out before I can claim?
Social Security is not going bankrupt, but its trust fund faces a projected shortfall in the coming years if Congress takes no action. Even in that scenario, ongoing payroll taxes would still fund the large majority of scheduled benefits. Claiming a higher benefit by delaying provides a larger base, but no claiming strategy fully insulates you from a future legislative change.
Where This Leaves You
The choice between claiming Social Security at 62 and waiting until 70 isn't a math problem with one clean answer; it's a judgment call that depends on your health, your income sources, your spouse, and how the decision interacts with taxes and Medicare. At Chesapeake Financial Planners, we model these tradeoffs with pre-retirees every week, running the joint life expectancy, the survivor benefit, and the tax ripple before anyone files. If you're weighing when to claim Social Security at 62 or whether to wait, a second opinion costs you nothing. Visit chesapeakefp.com to learn more.
Want to go deeper? Our Medicare and Social Security Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


