

What Is the R.U.D.D.E.R. Method™? A Six-Step Financial Planning Framework
Last reviewed: July 2026
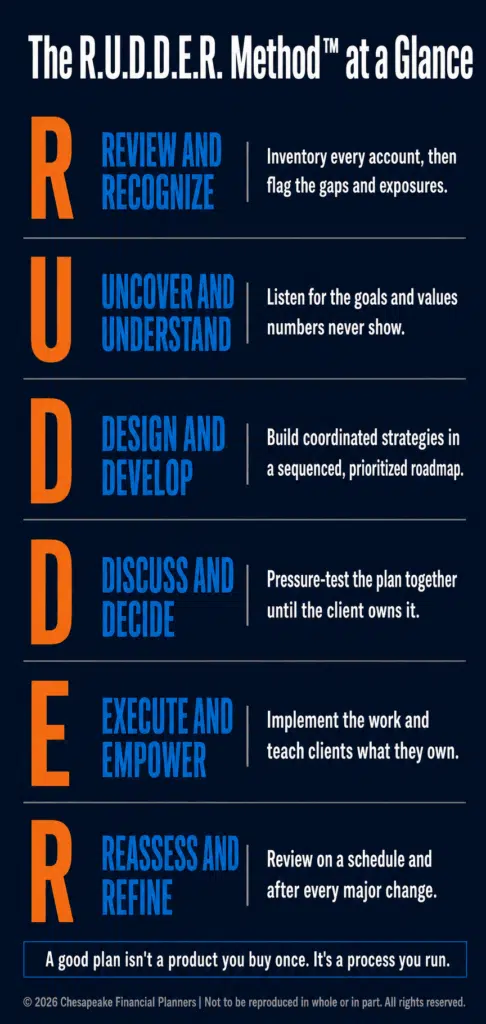
The R.U.D.D.E.R. Method™ financial planning framework is Chesapeake Financial Planners' six-step process for building, implementing, and maintaining a coordinated plan. The letters stand for Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. It exists because most people don't have a single financial problem. They have a coordination problem: a 401(k) in one place, an old IRA in another, an insurance policy nobody has looked at in years, and no single plan tying any of it together.
A good plan isn't a product you buy once. It's a process you run, and then keep running. The six steps below are the order Chesapeake works in, and the order is the point. Skip a step, and everything after it gets weaker. Run them in sequence, and a pile of disconnected accounts turns into something that actually functions as a plan.
On This Page
- Key Takeaways
- Why a Process Beats a Product in Financial Planning
- The Six Steps of the R.U.D.D.E.R. Method
- A Full Walkthrough: The R.U.D.D.E.R. Method in Practice
- Why the Sequence Matters
- How the Framework Coordinates Your CPA and Estate Attorney
- Who the R.U.D.D.E.R. Method Is For
- The 2026 Numbers the Plan Runs On
- Frequently Asked Questions
- Disclosures
Key Takeaways
- The R.U.D.D.E.R. Method™ is a six-step framework that moves you from scattered accounts to one coordinated, actively maintained financial plan.
- The sequence is the point: you can't design a sound strategy before you understand someone's full picture and what actually matters to them.
- For 2026, the 401(k) employee deferral limit rises to $24,500 and the IRA limit to $7,500, the kind of figures the framework builds around.
- Every step produces a concrete output, not a status summary, so the plan gets used instead of filed in a drawer.
- The framework fits anyone managing real complexity: pre-retirees, business owners, and couples coordinating their finances for the first time.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners across Harford County and the Baltimore metro area build coordinated financial plans since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. In his experience, the clients who struggle most aren't the ones who made big mistakes; they're the ones whose good individual decisions were never connected to each other.
Why a Process Beats a Product in Financial Planning
Why do most financial plans never get implemented?
Most financial planning conversations start in the wrong place. They open with a product question: which fund, which annuity, how much life insurance. Those questions have real answers. But the answers are close to meaningless until you know what the money is actually for. A coordinated financial planning approach flips the order. It starts with the person and the full picture, and only then moves to the product.
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step financial planning framework that carries a client from a first honest review of their whole situation all the way through implementation and ongoing maintenance. It's a six-step financial plan with a deliberate sequence, not a checklist you can run in any order you like. Each step depends on the one before it.
Jeff Judge has watched the alternative play out for years. "Someone will have a solid income, decent savings habits, and a business succession situation that's completely unprotected," he says. "Or they've been funding a taxable brokerage account for years while their HSA sat at zero. Those aren't catastrophic in isolation. Together, they're real problems." None of those issues is a product failure. Each one is a coordination failure, and no single product fixes it.
The cost of having no process tends to show up in the details nobody owned. Miss a required minimum distribution and you're exposed to a penalty on the amount you should have taken out. Under current law, RMDs begin at age 73 following the SECURE 2.0 changes. A process assigns that deadline to someone. A product sale leaves it sitting in a blind spot until it's expensive. What are the rules and strategies for required minimum distributions?
In Jeff's experience, the fragmentation rarely comes from carelessness. It comes from good decisions made one at a time, years apart, by people who were busy living their lives. A 401(k) opened at a first job, a brokerage account started after a bonus, a term policy bought when the first child arrived, an old IRA rolled halfway and then forgotten. Each choice made sense on its own. Stacked together without a process to connect them, they drift out of alignment, and nobody is assigned to notice. The R.U.D.D.E.R. Method™ exists to put that ownership somewhere, so the pieces get reviewed as one picture rather than six unrelated errands handled on different days.
There's a behavioral reason process beats product, too. Research on retirement readiness consistently finds that having a written plan changes saving behavior. The Employee Benefit Research Institute reports each year that workers who have calculated their retirement needs and follow a plan report meaningfully higher confidence than those who have not. A product purchase doesn't produce that effect. A process that ends in a written, owned plan does. The difference isn't the product on the shelf. It's whether anyone built the structure around it.
The Six Steps of the R.U.D.D.E.R. Method™
What are the six steps, in order?
Each step has a specific job and ends in a concrete output. Here is what happens at each stage, and why it sits where it does in the sequence.
Step 1: Review and Recognize. The framework opens with an honest inventory. Chesapeake gathers every account, policy, debt, and document, then recognizes what's working, what's exposed, and what's simply missing. This is where old 401(k)s nobody rolled over and policies nobody updated come back into view. The output is a clear, current picture of where you actually stand, not where you assume you stand. The Recognize half does real work here. It's not enough to list the accounts. Someone has to look at the list and flag the gaps: the disability coverage that ended when a job changed, the IRA that's still in a target-date fund built for a retirement date that no longer matches the plan, the estate documents dated before the second child was born.
Step 2: Uncover and Understand. This is where the plan stops being generic and becomes yours. Jeff spends more time here than anywhere else in the process. "You can build a technically sound plan that misses the mark entirely for someone's life," he says. "The U step is where you find out what actually matters. Get it wrong here and the rest of the plan doesn't hold." It also surfaces what a spreadsheet never shows: a parent who may need care, two partners with genuinely different risk tolerances, a business owner who doesn't actually want to sell the company everyone assumes is their exit. The work in this step is mostly listening. The numbers tell you what someone has. The conversation tells you what they're for, and those are rarely the same thing until someone asks.
Step 3: Design and Develop. With priorities clear, Chesapeake designs strategies across the areas that matter for your situation: retirement income, investment allocation, tax planning, insurance and risk, and estate coordination. Then it develops those strategies into specific, sequenced recommendations. Not everything happens at once. The plan identifies which moves carry the most weight early, which ones depend on something else being in place first, and what can reasonably wait. The output is a working roadmap with priorities, sequence, and accountability. This is also where the 2026 numbers come in. A 50-year-old who can defer up to the $8,000 catch-up contribution on top of the base 401(k) limit has a different design than someone who maxed out years ago and needs the next dollar to go somewhere tax-efficient. The design step turns priorities into a sequence the numbers actually support.
Step 4: Discuss and Decide. Recommendations nobody understands don't get followed. The second D is a working conversation, not a presentation. Chesapeake walks through each proposed strategy, compares options, and pressure-tests assumptions until the plan clearly fits the life it's meant to serve. Jeff treats this as non-negotiable. "If you can't explain back to me why we're doing something, we haven't done our jobs yet," he says. "The Discuss step is where the plan becomes yours." The output is specific: what moves forward, in what order, and the immediate next steps. The Decide half matters as much as the Discuss half. A conversation that ends without decisions is just a meeting. This step ends with choices written down, so there's no ambiguity about what was agreed to and no drift in the weeks afterward.
Step 5: Execute and Empower. Decisions made, the actual work starts. Account openings, investment changes, beneficiary updates, policy adjustments, and coordination with your CPA and estate attorney all happen in this step. Chesapeake handles the implementation rather than handing you a to-do list and a handshake. The Empower half is about knowledge: clients who understand what they own and why are the ones who stay committed when conditions get rough. The execution work is where most do-it-yourself plans stall. People know what to do and never get to it, because the steps are tedious and easy to defer. Owning the implementation is what closes the gap between a good plan on paper and a plan that's actually in place.
Step 6: Reassess and Refine. A plan that isn't maintained quietly goes stale. Life changes, tax law changes, and goals shift. "A lot of firms will build you a good plan and check in once a year," Jeff says. "That's not enough. Life doesn't wait for your annual review." Chesapeake reviews each plan on a set schedule and after major events, then makes targeted course corrections that keep it aligned with where you are now. Contribution limits move most years, tax brackets adjust for inflation, and rules like the RMD age have changed twice in recent legislation. A plan built on last year's numbers needs the Reassess step to stay accurate. What is the best retirement income planning strategy? tax planning strategies estate planning coordination
What ties the six steps together is that each one ends in something concrete: an inventory, a written set of priorities, a strategy document, a record of the decisions made, a completed set of transactions, and an updated plan. None of them ends in a vague status update. That discipline is deliberate. A step that produces an actual output is a step you can check, hand off to a CPA or attorney, and build on later. It is also how a plan stays usable instead of turning into a binder nobody opens after the first month.
A Full Walkthrough: The R.U.D.D.E.R. Method™ in Practice
What does the framework actually look like for a real household?
Consider a married couple in their late fifties, both still working, with what looked from the outside like a strong position. Walking them through all six steps shows why the structure matters more than any single recommendation.
In Review and Recognize, Chesapeake pulled together everything: two 401(k)s, an old 403(b) from a previous employer that had never been moved, a joint brokerage account, a small inherited IRA, two term life policies, and a will drafted eleven years earlier. The inventory alone surfaced two problems nobody had flagged. One spouse's old 403(b) was sitting in a high-cost fund lineup. The will still named a guardian for children who were now adults. Neither was catastrophic. Both were the kind of thing that goes unnoticed without someone assigned to look.
In Uncover and Understand, the conversation changed everything. The couple assumed they'd both work to 65 and retire together. But one spouse had an aging parent two states away and quietly expected to step back from work within three years to help with caregiving. That single fact reshaped the entire plan. The retirement date wasn't a shared 65 anymore. It was a staggered exit, with one income stopping years before the other. A design built on the original assumption would have been wrong from the start.
In Design and Develop, Chesapeake built around the real timeline. The plan front-loaded retirement contributions in the years before the earlier exit, made use of the 2026 IRA contribution limit of $7,500 for both spouses, and sequenced a partial rollover of the old 403(b) into a lower-cost account. It also flagged the eventual gap between the first spouse's retirement and the second's, where a temporary income bridge would be needed.
In Discuss and Decide, the couple pushed back on the contribution front-loading, worried it would strain cash flow. Chesapeake walked through the trade-offs, adjusted the timeline, and landed on a version they were both comfortable funding. That negotiation is the point of the step. The plan that gets followed is the one the client helped shape, not the one handed down.
In Execute and Empower, the rollover was completed, contributions were adjusted, beneficiaries were updated, and the eleven-year-old will was sent to an estate attorney for a refresh. The couple finished the step understanding not just what changed but why each piece connected to their staggered retirement timeline.
In Reassess and Refine, eighteen months later, the caregiving situation accelerated and the earlier retirement moved up a year. Because the plan had built the income bridge into the design, the adjustment was a course correction, not a crisis. That's what the sixth step buys: a plan that bends with real life instead of breaking.
Why the Sequence Matters
Can you skip a step in the R.U.D.D.E.R. Method™?
The order isn't decorative, and the steps don't shuffle. You can't design an effective strategy before you understand someone's priorities. You can't make a sound decision without first seeing the trade-offs laid out. You can't execute well on something you were never given the chance to understand. And none of it holds together without ongoing maintenance built into the relationship from the start.
There is a quieter cost to skipping steps. Every shortcut transfers risk onto the client without anyone saying so out loud. A portfolio built before someone understood the client's timeline can look fine on paper and only reveal its mismatch years later, when the money is finally needed and the allocation turns out to be wrong for the moment. Running Uncover and Understand before Design and Develop is what keeps that kind of mismatch from being built in at the very start, where it is hardest to spot and most expensive to unwind.
Picture what happens when a step gets skipped. Jump straight from a quick review to product recommendations, and you've skipped Uncover and Understand entirely. The result is a technically fine portfolio aimed at the wrong target: aggressive allocation for someone who needs to retire early to care for a parent, or a sell-the-business exit plan for an owner who never wanted to sell. The math is correct. The plan is wrong. Every step downstream inherits that error.
That's also why the Empower step earns its place. "An empowered client doesn't need to call every time the market drops three percent," Jeff says. "They understand their plan well enough to know that volatility is part of the strategy, not a reason to abandon it." A plan you understand is a plan you'll actually keep when it's tested. The research backs this up. FINRA and other investor-education bodies note that investors who understand their strategy are far less likely to make the kind of reactive moves that lock in losses during downturns. What Is Market Volatility and How Should I Handle It?
Consider a couple who came in with what looked like a healthy balance sheet: strong income, a nearly paid-off mortgage, and a brokerage account they had funded faithfully for a decade. The quick product answer would have been a portfolio adjustment. Running the sequence first surfaced the real exposures instead: an unfunded buy-sell agreement tied to the husband's business and a beneficiary designation that still named a relative who had passed away. Neither of those shows up if you jump straight to recommendations. The sequence is what forces those questions into the open before any money moves, which is exactly why Chesapeake treats the order as the framework itself rather than a formality.
How the Framework Coordinates Your CPA and Estate Attorney
Where do other professionals fit into the R.U.D.D.E.R. Method™?
A financial plan that ignores your tax advisor and your estate attorney isn't a coordinated plan. It's a portfolio with blind spots. The R.U.D.D.E.R. Method™ builds that coordination into the structure rather than leaving it to chance, and it happens at specific steps for specific reasons.
The groundwork starts in Review and Recognize, where the inventory captures not just accounts but documents: the most recent tax return, the will, any trusts, powers of attorney, and beneficiary designations. Most coordination failures trace back to a missing document nobody asked for early. A will that contradicts a beneficiary form is a common one, and beneficiary designations override the will every time. Catching that in the first step means it gets fixed before it becomes a probate problem.
Tax coordination lives mostly in Design and Develop and Execute and Empower. A Roth conversion strategy, the timing of capital gains, the order accounts get drawn down in retirement: each of these has a tax consequence that your CPA needs to see before it happens, not after. Chesapeake builds those moves into the design and then loops in the CPA during execution so the plan and the tax return agree with each other. As the IRS notes in its retirement guidance, the rules around contribution limits and distributions carry real tax weight, and getting the sequence wrong can cost more than the strategy saves.
Estate coordination runs through Execute and Empower and gets revisited in Reassess and Refine. When account titling, beneficiary updates, and trust funding need to happen, Chesapeake works alongside the estate attorney so the legal documents and the actual accounts line up. A trust that's never funded does nothing. A beneficiary form that contradicts the estate plan undoes the attorney's work. The framework treats these professionals as part of one team running the same plan, which is the only way the pieces actually fit together when it matters.
For business owners, this coordination matters even more, because a single decision can touch the personal return, the business return, and the estate plan all at once. The framework keeps all three professionals working from the same picture instead of each solving for their own slice in isolation. business exit planning
Who the R.U.D.D.E.R. Method™ Is For
Is this framework only for people near retirement?
The framework fits anyone managing real financial complexity. That includes professionals five to ten years from retirement who need to connect accounts, income streams, taxes, and estate documents into a single plan. It includes business owners running personal and company finances at the same time. It includes people working through an inheritance, a divorce, or a business exit, and couples combining two separate financial pictures into one coordinated plan for the first time.
Complexity isn't only a function of how much you have, though larger balances raise the stakes. The federal estate and gift tax basic exclusion sits at $15,000,000 per individual for 2026, so the vast majority of families fall under it, yet still benefit from coordinating beneficiaries, account titling, and tax strategy in one place rather than leaving each piece to chance. The framework is what keeps those pieces talking to each other.
Coordination matters just as much for households combining their finances for the first time. Two people arrive with two sets of accounts, two saving habits, and two ideas about what the money is for. Left side by side, those become two plans running in parallel and occasionally working against each other. The R.U.D.D.E.R. Method™ treats them as one picture from the Review and Recognize step forward, so decisions about retirement timing, account titling, and beneficiaries reflect a single shared set of priorities rather than a compromise stitched together after the fact.
What changes from person to person is the content inside each step. The specific recommendations, the products, the sequence of moves, all of it flexes to the individual. The six-step financial plan structure underneath stays exactly the same. planning after an inheritance
Business owners feel this need most acutely, because their personal and company finances borrow from each other constantly. A retirement plan decision made for the company changes the owner's personal tax picture. A succession plan or a sale reshapes household cash flow for years afterward. The R.U.D.D.E.R. Method™ keeps both ledgers in view at the same time, so a move on the business side is checked against its effect on the personal side before it happens. For an owner carrying both responsibilities, that coordination is often the difference between a plan that holds together and a set of decisions that quietly pull in different directions.
The 2026 Numbers the Plan Runs On
Which figures does the framework build around in 2026?
A framework is only as good as the numbers it runs on, and those numbers change most years. The Design and Develop step builds around the current-year limits, and the Reassess and Refine step updates them as they shift. Here are the 2026 figures the plan works with.
| Account or Threshold | 2026 Figure | Source |
|---|---|---|
| 401(k) employee deferral limit | $24,500 | IRS |
| 401(k) catch-up (age 50+) | $8,000 | IRS |
| IRA contribution limit | $7,500 | IRS |
| HSA contribution (self-only) | $4,400 | IRS |
| Estate and gift tax exclusion (per individual) | $15,000,000 | IRS |
| RMD beginning age | 73 | IRS / SECURE 2.0 |
According to the IRS, the 401(k) employee deferral limit is $24,500 for 2026, and the IRA limit is $7,500. These aren't trivia. They're the inputs the framework optimizes around. A 55-year-old who can stack the $8,000 catch-up on top of the base deferral has a meaningfully different design than someone who can't. The HSA self-only contribution limit of $4,400 is one of the most underused tax-advantaged dollars in most plans, and the Review step is where Chesapeake usually finds it sitting empty.
The point of tying the framework to these numbers is that they move. Limits rise with inflation, the RMD age has changed twice in recent legislation, and the estate exclusion is scheduled to shift again. A plan built once and never updated drifts out of step with the rules within a year or two. The Reassess and Refine step exists precisely so the plan keeps running on current numbers rather than the ones that were true the day it was built.
Frequently Asked Questions
What does R.U.D.D.E.R.™ stand for?
R.U.D.D.E.R.™ stands for Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. These are the six steps of Chesapeake Financial Planners' financial planning framework, run in that specific order because each step depends on the work completed in the one before it.
Is the R.U.D.D.E.R. Method™ a product I have to buy?
No, the R.U.D.D.E.R. Method™ is a planning process, not a product. It's the structured sequence Chesapeake Financial Planners uses to build, implement, and maintain a coordinated financial plan. The framework focuses on understanding your full picture first, then designing strategies that fit, rather than starting with a fund, annuity, or insurance policy.
Can you skip a step in the R.U.D.D.E.R. Method™?
You shouldn't, because the sequence is the point. Each step produces an output the next step needs. Skipping Uncover and Understand, for example, means designing strategies before knowing what actually matters to you, which produces a technically sound plan aimed at the wrong target. Every shortcut quietly transfers risk onto the client.
Who is the R.U.D.D.E.R. Method™ designed for?
The framework fits anyone managing real financial complexity: professionals five to ten years from retirement, business owners coordinating personal and company finances, people navigating an inheritance, divorce, or business exit, and couples combining two financial pictures for the first time. The structure stays the same while the content inside each step flexes to your situation.
How does the R.U.D.D.E.R. Method™ handle taxes and estate planning?
The framework coordinates your CPA and estate attorney directly into the process. Tax strategy is built during Design and Develop and executed alongside your CPA, while estate moves like account titling, beneficiary updates, and trust funding happen during Execute and Empower with your attorney. This keeps your plan, tax return, and legal documents aligned rather than working against each other.
How often is a plan reviewed under this framework?
Plans are reviewed on a set schedule and after any major life event, not just once a year. The Reassess and Refine step exists because life changes, tax law changes, and contribution limits move most years. As Jeff Judge puts it, life doesn't wait for your annual review, so the framework builds ongoing maintenance into the relationship from the start.
What 2026 figures does the R.U.D.D.E.R. Method™ build around?
The framework builds around current-year limits, including the 2026 401(k) deferral limit of $24,500, the IRA limit of $7,500, the HSA self-only limit of $4,400, and the estate exclusion of $15,000,000 per individual. The Design step optimizes around these numbers, and the Reassess step updates them as they change each year.
If this framework matches the kind of coordination your situation needs, our guide to building a complete financial plan walks through each step in more depth. Download it at chesapeakefp.com to see how the R.U.D.D.E.R. Method™ financial planning process turns scattered accounts into one plan that actually works together.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


