

What is the most tax-efficient charitable giving for high-net-worth donors?
Last reviewed: July 2026
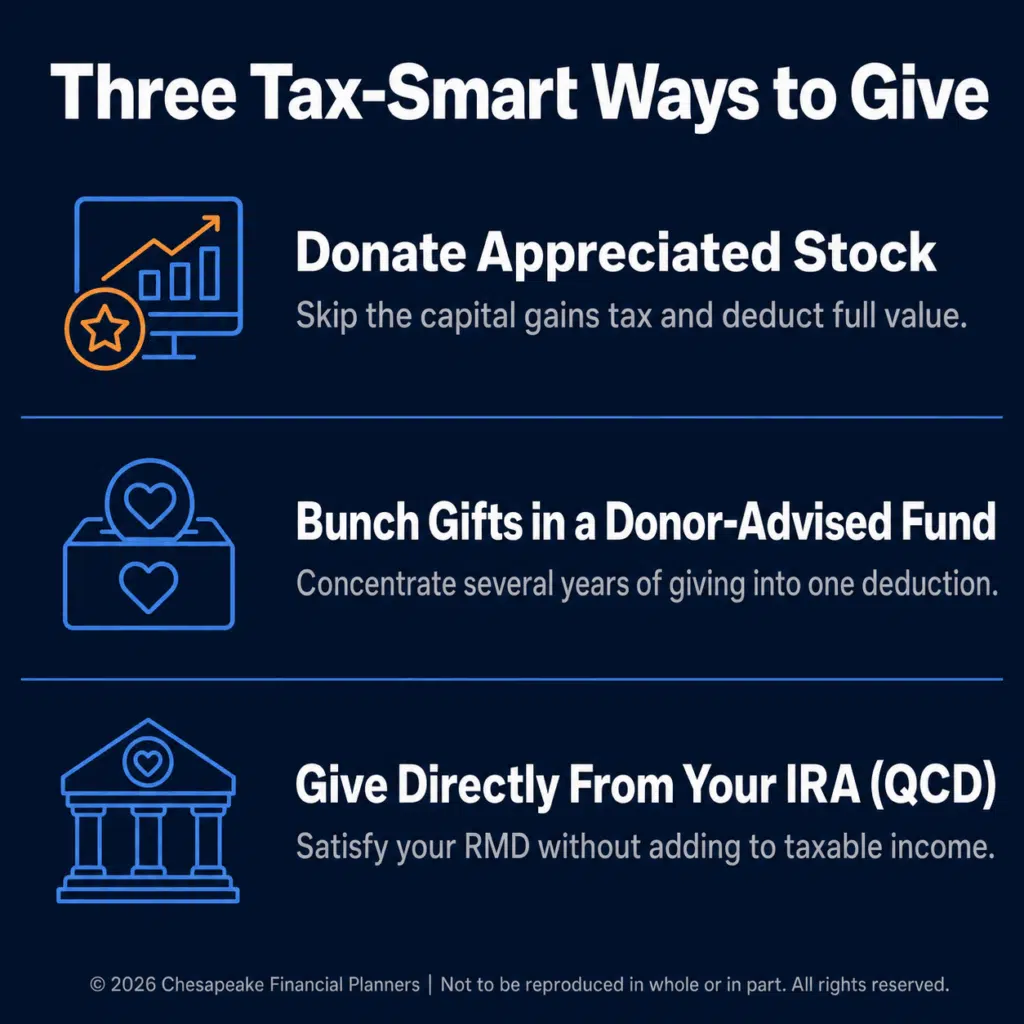
The three pillars of tax-efficient charitable giving for high-net-worth donors are donating appreciated stock, bunching gifts through a donor-advised fund, and making qualified charitable distributions from an IRA after age 70½. Each does something cash cannot: appreciated stock erases capital gains tax, a donor-advised fund lets you clear the standard deduction in one big year, and a QCD gives straight from your IRA without the money ever counting as income. This guide explains how each one works and when to use it.
Key Takeaways
- Donating appreciated stock avoids capital gains tax and still deducts the full fair market value, making it more efficient than giving the same amount in cash.
- A donor-advised fund lets you bunch several years of giving into one year to clear the 2026 standard deduction of $32,200 for couples.
- A qualified charitable distribution can send up to $111,000 per person from an IRA to charity in 2026 without adding to taxable income.
- Cash gifts deduct up to 60% of AGI; gifts of appreciated property are capped at 30%, per IRS rules.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area give more tax-efficiently since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: the donors who get the biggest tax benefit are not the ones who give the most, they are the ones who give the right asset through the right vehicle.
Why is the asset you donate the heart of tax-efficient charitable giving?
The asset you donate matters more than the amount because giving the wrong asset can leave a large tax benefit on the table even when your generosity is identical. Write a check for $50,000 and you give $50,000. Donate $50,000 of stock you bought years ago for $10,000, and you give the same $50,000 to charity while also escaping the capital gains tax you would have owed on the $40,000 gain. Same gift to the charity, very different result for you.
This is the core idea behind tax-efficient giving: match the asset to the goal. Highly appreciated, long-held positions are the best candidates to donate directly, because the embedded gain is exactly what you avoid. Cash is the least efficient asset to give if you hold appreciated investments you could donate instead. The IRS allows a deduction of up to 60% of your adjusted gross income for cash gifts to public charities, but caps gifts of appreciated capital gain property at 30%, so larger gifts may need to be spread across years. As the IRS states, "Beginning with tax year 2026, if you do not itemize, you may deduct up to $1,000 ($2,000 if filing jointly) of your cash contributions to certain qualified organizations."
There is a timing wrinkle new for 2026 that raises the value of planning. The One Big Beautiful Bill added a 0.5%-of-AGI floor on itemized charitable deductions, meaning the first half-percent of your income in gifts no longer counts. That nudges donors toward concentrating gifts into fewer, larger years rather than giving the same modest amount annually.
How does a donor-advised fund make your giving more efficient?
A donor-advised fund makes giving more efficient by separating the year you take the tax deduction from the years you actually support charities, which solves the standard-deduction problem. You contribute a lump sum to the fund, claim the full deduction in that year, and then recommend grants to your chosen charities over time while the balance stays invested.
The reason this matters is the standard deduction. For 2026 it is $32,200 for married couples filing jointly, and if your annual giving plus other itemized deductions fall below that, your gifts produce no separate tax benefit. By "bunching" several years of intended giving into one contribution, you push your itemized deductions above the standard deduction in that year and take the standard deduction in the off years. You capture a benefit you would otherwise lose, and the charities still receive steady support.
A donor-advised fund also pairs perfectly with appreciated stock. You can fund it with securities rather than cash, avoiding the capital gains tax and deducting fair market value, then let the fund handle liquidation and grant distribution. As Jeff Judge puts it, "A donor-advised fund is the closest thing to a private foundation without the cost, the filings, or the headache, and for most families it does the same job."
When does a qualified charitable distribution beat every other option?
A qualified charitable distribution beats every other giving method once you are subject to required minimum distributions, because it satisfies the RMD without the money ever counting as income. Starting at age 70½, you can transfer up to $111,000 per person directly from your IRA to charity in 2026, and that transfer is excluded from your taxable income entirely.
The power is in what it avoids. A normal RMD is taxed as ordinary income and raises your adjusted gross income, which can drag up the taxation of your Social Security and push you into higher Medicare premium brackets. A QCD sidesteps all of that, because the money never lands in your AGI. For a retiree who gives anyway and faces an RMD they do not need for living expenses, directing it to charity as a QCD is often the single most efficient gift available.
The rules are specific and worth getting right. The funds must transfer directly from your IRA custodian to a qualifying public charity, never passing through your hands; donor-advised funds and private foundations do not qualify as QCD recipients. You must be at least 70½ on the date of the distribution, which is earlier than the age 73 when RMDs begin. Run these through a real process. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and the QCD-versus-RMD decision lives in Design and Develop, where giving and income planning come together.
Related Topics Worth Reading
These three core strategies connect to the broader charitable and estate picture. The related topics below go deeper.
- The full menu of charitable strategies for wealthy families, including trusts and foundations. Donor-advised fund, private foundation, or QCD: which giving strategy fits me?
- How donor-advised funds work in detail, including investment and grant mechanics. How Do Donor-Advised Funds Work for Tax Savings?
- The complete guide to qualified charitable distributions for retirees. How Can I Donate From My IRA and Reduce Taxes?
- How bunching deductions interacts with the standard deduction year to year. How Can Bunching Charitable Deductions Save Me on Taxes?
- Why donating appreciated stock beats selling it first and giving cash. How Much Will I Pay in Capital Gains Tax?
Frequently Asked Questions
What is the most tax-efficient way to donate to charity?
The most tax-efficient way to donate for most high-net-worth donors is giving long-held appreciated stock directly, which avoids the capital gains tax a sale would trigger and still deducts the full fair market value. For donors over 70½ with required minimum distributions, a qualified charitable distribution from an IRA is often even better because the gift never counts as taxable income at all.
How much can I deduct for charitable donations?
You can deduct cash gifts to public charities up to 60% of your adjusted gross income, while gifts of appreciated capital gain property are capped at 30% of AGI, per IRS Publication 526. Amounts above these limits can generally be carried forward for up to five years. Beginning in tax year 2026, a 0.5%-of-AGI floor also applies to itemized charitable deductions, and the IRS notes non-itemizers can additionally deduct up to $1,000 ($2,000 if filing jointly) of cash gifts.
Can I use a donor-advised fund and a QCD together?
You can use both, but not for the same dollars, because a qualified charitable distribution cannot be made to a donor-advised fund. Many donors use a QCD to satisfy their RMD tax-free and separately fund a donor-advised fund with appreciated stock for their broader giving. Coordinating the two lets you address both income-tax timing and capital gains in the same year.
What is the QCD limit for 2026?
The qualified charitable distribution limit for 2026 is $111,000 per individual, per IRS Publication 590-B. Each spouse with their own IRA can give up to that amount. You must be at least 70½ on the date of distribution, and the funds must go directly from your IRA custodian to a qualifying public charity to be excluded from your taxable income.
Is it better to donate stock or cash?
Donating long-held appreciated stock is usually better than donating cash, because you avoid the capital gains tax on the appreciation and still deduct the full fair market value. Giving cash means you potentially pay tax on the gains elsewhere and donate after-tax dollars. The main reason to give cash is if you have no appreciated assets or need to give more than the 30%-of-AGI limit on property allows.
Putting these strategies to work
The difference between an average giver and a tax-efficient one is rarely how much they give; it is which asset they give and through which vehicle. Tax-efficient charitable giving through appreciated stock, a donor-advised fund, and a qualified charitable distribution covers most high-net-worth situations, and these vehicles often work best in combination. At Chesapeake Financial Planners, we coordinate these strategies with clients and their CPAs every year. If you are weighing how to give more efficiently, a second opinion costs you nothing. Visit chesapeakefp.com to learn more.
Want to go deeper? Our Tax-Smart Charitable Giving Playbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


