

How Does RSU Vesting Tax Withholding Work and Is Yours Too Low?
Last reviewed: July 2026
Yes, RSU vesting taxes are often higher than what your employer withholds, and this gap catches tech employees off guard every spring. Most companies withhold federal tax on vested RSUs at a flat 22% supplemental rate, but if you are a high earner, your actual marginal rate is likely 32%, 35%, or 37%. That difference becomes a surprise tax bill when you file. Understanding RSU vesting tax withholding is the single most overlooked piece of equity compensation planning for the engineers, product managers, and executives we work with across Harford County and the Baltimore metro.
On This Page
- Key Takeaways
- How Do RSU Vesting Taxes Actually Work?
- Why Does Your Employer's 22% Withholding Usually Fall Short?
- How Much Extra Tax Do You Actually Owe on Vested RSUs?
- What Should You Do When Withholding Does Not Cover Your Bracket?
- How Do RSU Taxes Interact With Maryland State Income Tax?
- Should You Sell Vested Shares Right Away?
- The R.U.D.D.E.R. Method Applied to RSU Planning
- Frequently Asked Questions
- Disclosures
Key Takeaways
- Employers typically withhold federal tax on RSUs at a flat 22% supplemental rate, which is below the top marginal rate of 37%.
- The 2026 supplemental wage rate stays at 22% for vesting income up to $1 million, then jumps to 37% above that.
- RSUs are taxed as ordinary income at vesting based on the fair market value of the shares on that date.
- A high earner in the 35% bracket faces a 13-point withholding gap that must be covered through estimated payments or extra withholding.
- Selling vested shares immediately avoids capital gains complications but does not eliminate the original ordinary income tax owed at vesting.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate equity compensation and tax planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has seen too many tech professionals treat their RSU vesting statement like a paycheck, only to discover in April that the IRS sees it very differently.
How Do RSU Vesting Taxes Actually Work?
Restricted stock units are taxed as ordinary income the moment they vest. The taxable amount equals the fair market value of the shares on the vesting date, multiplied by the number of shares that vest. If 500 shares vest at $80 per share, you have $40,000 of ordinary income added to your W-2 that year, whether or not you sell a single share.
This is the part that trips people up. You did not receive cash. You received stock. But the IRS treats that stock value as wages, and it gets reported in Box 1 of your W-2 right alongside your salary. According to the IRS, the income is recognized at vesting regardless of whether you hold or sell the shares.
What is the taxable event for an RSU?
The taxable event is vesting, not granting and not selling. When your company grants RSUs, nothing is taxed because the units have no value you can access yet. When they vest, ownership transfers to you and the fair market value becomes taxable ordinary income. I often tell clients that the grant date is a promise and the vesting date is a paycheck, and only the paycheck gets taxed.
Your company handles this by recording the vesting value as supplemental wages. They then withhold federal income tax, Social Security, Medicare, and applicable state tax. The problem is not that they fail to withhold. The problem is how much they withhold relative to what you actually owe.
Why Does Your Employer's 22% Withholding Usually Fall Short?
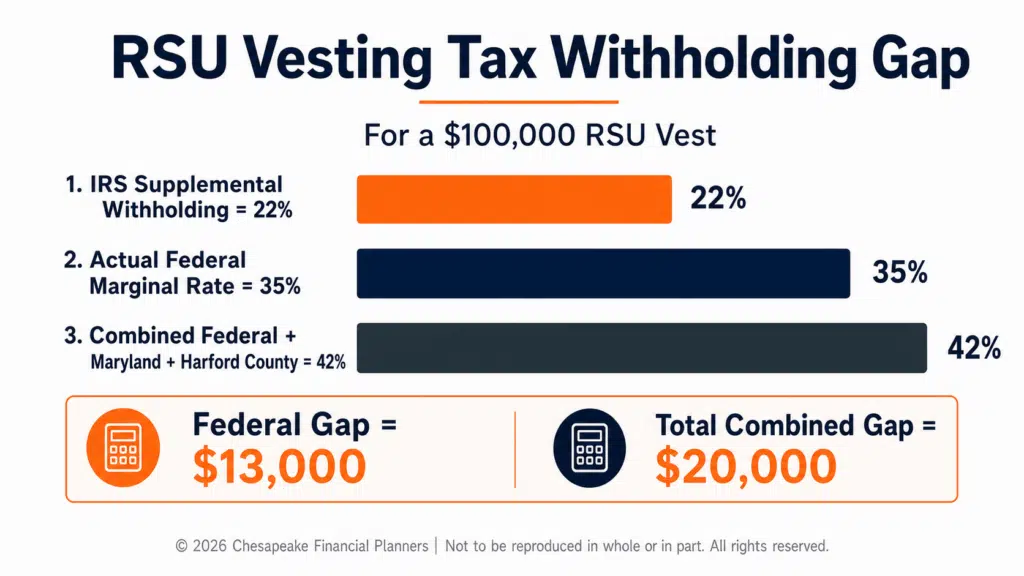
Your employer withholds federal tax on RSU vesting income using the flat supplemental wage rate, which is 22% for amounts up to $1 million in a calendar year. According to IRS Publication 15, supplemental wages above $1 million are withheld at 37%. For most employees, the 22% rate applies, and that is exactly where the shortfall comes from.
If your total income puts you in the 32%, 35%, or 37% marginal tax bracket, withholding 22% on a chunk of income means you are underwithheld by 10 to 15 percentage points on that income. On $40,000 of vesting income, a 13-point gap is $5,200 you still owe when you file.
How does the supplemental rate compare to your marginal rate?
The supplemental rate is a flat withholding convenience, not your actual tax rate. Your marginal rate depends on your total taxable income. For 2026, the IRS sets the 37% top bracket for single filers with taxable income above $640,600 and married filing jointly above $768,700. The 35% bracket begins at $256,225 for single filers. A senior engineer earning $250,000 in salary plus $80,000 in RSU vesting is solidly in the 35% bracket, but their RSUs were only withheld at 22%.
Here is the core mismatch laid out plainly:
| Situation | Federal withholding on RSUs | Actual marginal rate | Gap to cover |
|---|---|---|---|
| Mid-level employee, $150K income | 22% | 24% | 2 points |
| Senior employee, $260K income | 22% | 35% | 13 points |
| Executive, $500K income | 22% | 35% | 13 points |
| Top earner, over $640K income | 22% | 37% | 15 points |
The math is not complicated, but the surprise is real. I've watched clients in the Baltimore tech corridor get a four-figure or five-figure tax bill simply because nobody told them the 22% withholding was a floor, not a final number.
Why isn't my 22% RSU withholding enough, and what will I owe?
How Much Extra Tax Do You Actually Owe on Vested RSUs?
To calculate your true RSU tax liability, multiply the vesting value by your marginal federal rate, then subtract what was already withheld at 22%. The remainder is what you owe beyond your existing withholding.
Take a concrete example. Suppose $100,000 of RSUs vest during the year and you sit in the 35% bracket. Your federal tax on that income is $35,000. Your employer withheld $22,000. You owe $13,000 more in federal tax than was withheld, before factoring in state tax and the additional Medicare surtax.
Does the additional Medicare tax apply to RSU income?
Yes, the 0.9% additional Medicare tax applies to wages, including RSU vesting income, above $200,000 for single filers and $250,000 for married filing jointly. Employers are required to withhold this once your wages cross $200,000, but the thresholds for what you actually owe depend on your filing status and combined household income, so couples can still owe more at filing.
There is also the net investment income tax to keep in mind once you sell appreciated shares, though that applies to the gain after vesting, not the vesting income itself. According to IRS guidance, the 3.8% net investment income tax applies to investment gains above the same $200,000 and $250,000 thresholds. Maryland adds its own 2% surtax on net capital gains for filers with federal AGI over $350,000, which can apply when you hold vested shares and later sell them at a gain.
What Should You Do When Withholding Does Not Cover Your Bracket?
When your employer's RSU withholding falls short, you have three practical levers: increase your regular paycheck withholding, make quarterly estimated tax payments, or set aside cash to cover the gap at filing. The right choice depends on how large the shortfall is and whether you want to avoid an underpayment penalty.
The IRS expects you to pay tax as you earn it. If you underpay by enough, you owe an underpayment penalty on top of the tax. According to the IRS, you can generally avoid the penalty by paying the smaller of 90% of your current-year tax or 100% of your prior-year tax (110% if your prior-year adjusted gross income exceeded $150,000).
How do you adjust withholding to cover the RSU gap?
You adjust withholding by submitting a new Form W-4 to your employer requesting additional federal tax withheld from each paycheck. This is the cleanest fix for many people because withholding is treated as paid evenly throughout the year, which sidesteps the timing rules that trip up estimated payments. I prefer this approach for clients who would rather not write quarterly checks. I have clients add a fixed extra amount per paycheck right after a vesting event so the gap closes automatically.
How do I fill out a W-4 so I don't owe or overpay?
If your vesting is concentrated in one quarter, estimated payments may make more sense because you can pay close to when the income hits. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. We use the Review and Recognize step here to map out the full vesting calendar before the year starts, so the tax surprise never becomes a surprise.
One thing the numbers never capture: the emotional whiplash of seeing a strong year of equity comp turn into a tax bill that feels like a penalty for success. The clients who plan ahead never feel that. The clients who wait until April almost always do.
How Do RSU Taxes Interact With Maryland State Income Tax?
RSU vesting income is also subject to Maryland state income tax and the local county income tax where you live, which for our Harford County clients adds a meaningful layer on top of the federal gap. Maryland uses a graduated state rate that now tops out at 6.5% as of the 2026 tax year — HB 352 (2025) added new high-income brackets of 6.25% and 6.5% above the former 5.75% top rate — and Harford County levies a local income tax on top of that.
According to the Comptroller of Maryland, the 5.75% rate applies to taxable income above $250,000 for single filers and $300,000 for joint filers, and for 2026 HB 352 (2025) added a 6.25% bracket on income above $500,000 ($600,000 for joint filers) and a 6.5% top bracket above $1 million ($1.2 million for joint filers). Harford County's local income tax rate is layered on residents' Maryland taxable income, which means a tech employee living in Bel Air or Forest Hill is paying both state and county tax on every vested share.
Does Maryland withhold enough on RSU vesting in Harford County?
Maryland state withholding on supplemental wages often lands in the same shortfall trap as federal withholding for high earners in Harford County. Many employers apply a flat state supplemental rate that does not account for the combined state-plus-county burden a Maryland resident actually owes. For a Forest Hill resident in the top state bracket, the combined state and county rate can approach 9%, well above many default withholding settings.
This is exactly why we built a tech-employee tax practice serving Harford County and the broader Baltimore metro. Chesapeake Financial Planners sits in Forest Hill, minutes from Bel Air, and a large share of our equity-comp clients commute to tech and biotech employers across the region. We map the federal, state, and county layers together because looking at any one in isolation produces a wrong answer.
What strategies can Harford County residents use to reduce their Maryland state income tax?
Should You Sell Vested Shares Right Away?
Selling vested RSU shares immediately is often the cleanest move because it removes single-stock concentration risk and produces little to no additional capital gain. When shares vest, your cost basis equals the fair market value already taxed as ordinary income, so selling that same day usually creates a near-zero gain or loss.
The ordinary income tax at vesting is owed no matter what you do with the shares afterward. Holding does not undo it. If you hold and the stock rises, you face capital gains tax on the appreciation when you eventually sell. If you hold and the stock falls, you have already paid ordinary income tax on a value you no longer have.
What is the difference between RSU income tax and capital gains tax?
RSU income tax is the ordinary income tax owed on the share value at vesting, while capital gains tax applies only to any appreciation after vesting. If shares vest at $80 and you sell later at $100, the $80 was ordinary income and the $20 gain is a capital gain. According to the IRS, holding the shares more than a year after vesting qualifies the gain for long-term capital gains rates, which are lower than ordinary rates.
Many of our clients adopt a simple rule: sell at vest, then redeploy the proceeds into a diversified plan. That keeps you from betting your tax-paid dollars on a single employer's stock price. I often point out that an employee already has enormous financial exposure to their company through their salary and benefits, so doubling down through concentrated stock rarely makes sense once you look at the whole picture.
What is the best financial planning strategy for a tech company employee with equity compensation?
The R.U.D.D.E.R. Method™ Applied to RSU Planning
We run equity compensation decisions through the same six-step framework we use for every financial plan. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine.
How Does the R.U.D.D.E.R. Method™ Apply to RSU Tax Planning?
The R.U.D.D.E.R. Method™ turns a vague "deal with it in April" instinct into a front-loaded action plan: the Review step maps your full vesting calendar in January, the Uncover step calculates the exact withholding gap across federal, Maryland, and Harford County tax, and the Design step converts that gap into a concrete W-4 adjustment or estimated payment schedule. For tech employees in Forest Hill, Bel Air, and across the Baltimore metro who vest quarterly, running this process before the first vest of the year eliminates the spring surprise entirely. The Reassess step revisits the numbers after each vest because stock price changes and year-to-date income both shift the marginal rate calculation.
For RSUs, Review and Recognize means pulling your full vesting schedule for the year. Uncover and Understand means calculating your true marginal rate across federal, Maryland state, and Harford County tax. Design and Develop produces a withholding-and-estimated-payment plan. Discuss and Decide weighs the sell-at-vest versus hold question against your concentration risk. Execute and Empower puts the W-4 changes or quarterly payments in motion. Reassess and Refine checks the plan after each vesting event, because stock prices and brackets both move.
How should you plan for equity compensation, RSUs, and stock options?
This is not theory. It is the exact process we walk through with tech employees who book a call after getting burned by an unexpected RSU tax bill the prior year.
Frequently Asked Questions
Why does my employer only withhold 22% on my RSUs?
Your employer withholds 22% because that is the flat federal supplemental wage rate the IRS allows for amounts up to $1 million per year. It is a withholding convenience, not a calculation of your actual tax bracket. High earners in the 32% to 37% brackets are underwithheld because the flat rate sits below their true marginal rate, leaving a gap they must cover separately.
How much extra tax will I owe on my RSUs?
You will owe the difference between your marginal tax rate and the 22% already withheld, multiplied by your vesting income. A person in the 35% bracket with $100,000 in vesting owes roughly $13,000 more in federal tax than was withheld, before state and county tax. The exact figure depends on your total income, filing status, and state of residence.
Are RSUs taxed twice?
No, RSUs are not taxed twice, but they involve two separate taxable events. The share value is taxed as ordinary income at vesting. If you later sell for more than the vesting value, only the additional appreciation is taxed as a capital gain. The original vesting value is never taxed again, so selling immediately at vest avoids any second tax beyond the gain.
Should I increase my paycheck withholding or pay estimated taxes for RSUs?
Increasing paycheck withholding is usually simpler because withholding counts as paid evenly across the year, which avoids estimated-payment timing penalties. Estimated quarterly payments make sense when your vesting is concentrated in one period. Many tech employees add extra W-4 withholding right after a vesting event so the federal and state gap closes automatically without writing quarterly checks.
Do I owe Maryland and Harford County tax on RSU vesting?
Yes, RSU vesting income is subject to Maryland state income tax — up to a 6.5% top rate for 2026 after HB 352 (2025) added 6.25% and 6.5% high-income brackets above the former 5.75% top rate — and the Harford County local income tax for residents. Employers often underwithhold at the state level using a flat supplemental rate that ignores the combined state-plus-county burden. A Forest Hill or Bel Air resident in the top bracket can face a combined state and county rate approaching 9% on vested shares.
What happens if I do not cover the RSU withholding gap?
If you do not cover the gap, you owe the remaining tax when you file and may face an underpayment penalty. The IRS expects tax paid as income is earned. You generally avoid the penalty by paying 90% of your current-year tax or 110% of your prior-year tax if your prior-year adjusted gross income exceeded $150,000. Planning withholding around vesting dates prevents both the bill shock and the penalty.
Does selling my RSU shares at vesting reduce my tax bill?
No, selling at vesting does not reduce the ordinary income tax you already owe on the vested share value. That tax is locked in the moment shares vest. Selling immediately does prevent additional capital gains complications and removes single-stock concentration risk, which is why many advisors recommend it. The proceeds can then fund estimated taxes or a diversified investment plan.
Ready to put a plan around your RSU vesting taxes? Jeff Judge and the Chesapeake team serve tech employees and business owners across Harford County and the Baltimore metro from our Forest Hill office. If you want to stop guessing what you owe and stop getting surprised in April, schedule a free fit call at chesapeakefp.com. Understanding your RSU vesting tax withholding now is far cheaper than discovering the gap at filing.
This post is adapted from 'RSU Vesting Taxes Higher Than Your Employer Withholds' originally published on Jeff Judge's LinkedIn.
Want to go deeper? Our Tech Equity Tax Traps Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


