

How Do Qualified Charitable Distributions Work and Who Benefits Most?
Last reviewed: July 2026
A qualified charitable distribution (QCD) lets anyone age 70½ or older transfer money directly from a traditional IRA to a qualified charity without paying income tax on the withdrawal. In 2026 you can give up to $111,000 per year this way, and the gift counts toward your required minimum distribution. The people who benefit most are retirees who already give to charity, take the standard deduction, and want to keep their taxable income down.
Key Takeaways
- A QCD lets IRA owners age 70½+ give up to $111,000 in 2026 directly to charity, tax-free.
- A QCD satisfies your required minimum distribution while keeping the gift out of your adjusted gross income entirely.
- Lowering AGI through a QCD can reduce Medicare IRMAA surcharges and the tax on your Social Security benefits.
- The money must move directly from the IRA custodian to the charity; a personal reimbursement does not qualify.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement and charitable giving decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that a QCD is one of the few moves in the tax code where the charity wins, the IRS collects nothing, and the donor still comes out ahead.
Most retirees who give to charity write a check from their checking account and assume they will deduct it. After the standard deduction nearly doubled, that deduction often disappears. A QCD fixes the problem from a different angle. Instead of chasing a deduction you may never get, you simply keep the income off your return in the first place.
What Is a Qualified Charitable Distribution and How Does It Work?
A qualified charitable distribution is a direct transfer of funds from your IRA custodian to an eligible charity. The amount you give is excluded from your taxable income for the year. That exclusion is the entire point. You never report the distribution as income, so it never inflates your adjusted gross income.
Here is the mechanical difference from a normal gift. With a regular donation, the IRA distribution lands in your income first, then you try to claim an itemized deduction to offset it. With a QCD, there is no income to offset because the money goes straight to the charity. According to the IRS, the maximum QCD is indexed for inflation and stands at $111,000 per individual in 2026. A married couple with separate IRAs can each give up to that limit.
The strategy fits cleanly into the kind of structured planning we use with clients. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A QCD usually surfaces during the Review and Recognize step, when we look at where a retiree's required distributions and charitable habits collide.
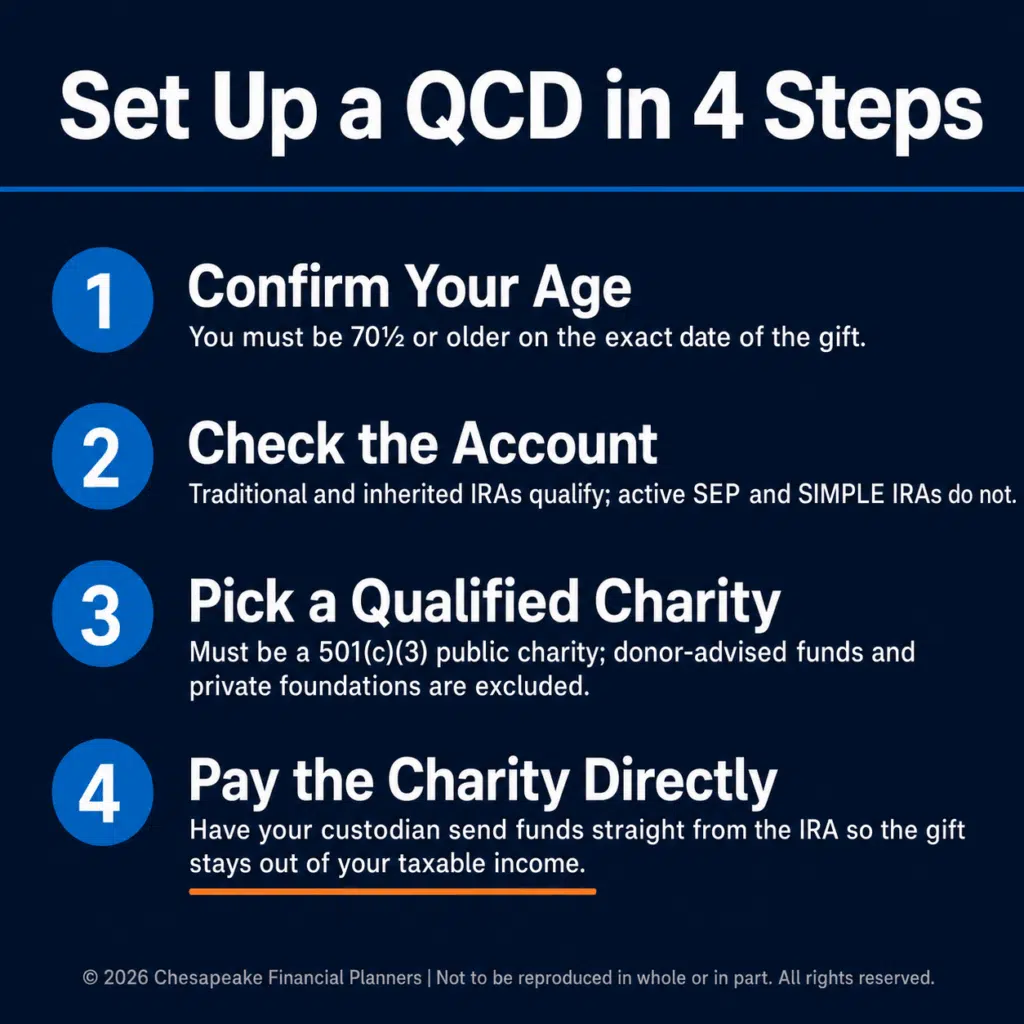
How to Set Up a Qualified Charitable Distribution Step by Step
Setting up a QCD is more administrative than complicated. Follow these steps in order and the gift qualifies cleanly.
- Confirm you are age 70½ or older. Eligibility starts on the exact date you turn 70½, not the calendar year you reach it. This rule is set by IRS guidance and is non-negotiable.
- Confirm the account is eligible. Traditional IRAs and inherited IRAs qualify. Active SEP and SIMPLE IRAs receiving employer contributions do not. Employer plans like 401(k)s are not eligible until you roll them into an IRA.
- Confirm the charity is qualified. The recipient must be a 501(c)(3) public charity. Donor-advised funds, private foundations, and supporting organizations are excluded.
- Tell your custodian to pay the charity directly. The check or transfer must go from the IRA to the charity. If the money touches your personal account first, it becomes taxable income and the QCD is lost.
- Get a written acknowledgment. Request the same contemporaneous receipt you would for any deductible gift. You need it if the IRS asks.
- Report it correctly at tax time. Your 1099-R will show the full distribution. You or your preparer enters the taxable amount as zero and writes "QCD" next to the line.
Jeff has watched clients lose the tax benefit on a sizable gift because the custodian mailed the check to the donor instead of the charity. The fix is simple: confirm the payee in writing before the distribution leaves the account.
Who Benefits Most From a Qualified Charitable Distribution?
The QCD is not for everyone, and it is worth being honest about that. The retirees who gain the most share a specific profile.
You benefit most if you are age 70½ or older, already donate to charity, and take the standard deduction rather than itemizing. The IRS sets the 2026 standard deduction at $16,100 for single filers and $32,200 for married couples filing jointly. Many retirees fall under those thresholds and get no tax value from charitable checks. A QCD restores the benefit by keeping the income off the return entirely.
The second group is anyone whose adjusted gross income brushes up against an income-based threshold. Lower AGI can mean a smaller Medicare IRMAA surcharge, less of your Social Security taxed, and a lower exposure to the net investment income tax. A QCD is one of the cleanest levers a retiree has to manage AGI, because the dollars never enter the calculation. For many high-net-worth clients, the IRMAA savings alone justify the strategy before the charitable benefit is even counted.
How does a donor-advised fund work and who should consider using one?
QCD vs. Standard Deduction vs. Direct Donation
When two or more giving methods are on the table, it helps to see them side by side.
| Method | Reduces AGI | Requires itemizing | Age requirement | Counts toward RMD |
|---|---|---|---|---|
| QCD from IRA | Yes | No | 70½+ | Yes |
| Cash gift + itemize | No | Yes | None | No |
| Cash gift + standard deduction | No | No | None | No |
The table makes the advantage obvious. A QCD is the only method that lowers your adjusted gross income, and AGI is the number that drives Medicare costs, Social Security taxation, and several stealth taxes. A direct cash gift only helps if you itemize, and most retirees no longer do.
How Can Bunching Charitable Deductions Save Me on Taxes?
How a QCD Interacts With Your Required Minimum Distribution
A QCD can satisfy all or part of your required minimum distribution for the year, up to the QCD limit. This is where the strategy earns its keep. If you are required to withdraw $40,000 and you do not need the money, you can direct that amount to charity as a QCD. The RMD is satisfied, and not a dollar of it shows up as taxable income.
Timing matters. The QCD must occur before you take the rest of your RMD as cash, because the first dollars out of the IRA count toward the RMD. Once you have already withdrawn your full RMD, you cannot retroactively reclassify it as a QCD. Plan the charitable transfer early in the year if you intend it to offset the distribution.
What Are the Best Tax Strategies for High Net Worth Individuals?
Frequently Asked Questions
What is the QCD limit for 2026?
The QCD limit for 2026 is $111,000 per individual, according to the IRS. The cap is indexed for inflation, so it rises in most years. A married couple who each own a traditional IRA can give up to $111,000 apiece, for a combined $222,000 in tax-free charitable gifts.
Do I have to be taking RMDs to make a QCD?
No, you do not have to be taking required minimum distributions to make a QCD. Eligibility begins at age 70½, while RMDs now begin at age 73 for most people. That gap gives you a window where you can give from your IRA tax-free even before any distributions are required.
Can I make a QCD to a donor-advised fund?
No, you cannot make a QCD to a donor-advised fund, a private foundation, or a supporting organization. The IRS excludes those entities specifically. The recipient must be a qualified 501(c)(3) public charity that receives the funds directly from your IRA custodian to keep the distribution tax-free.
How does a QCD lower my taxes if I do not itemize?
A QCD lowers your taxes by excluding the gifted amount from your adjusted gross income, which works whether or not you itemize. A standard charitable deduction only helps if you itemize. A QCD keeps the income off your return entirely, so even standard-deduction filers get the full benefit.
Will a QCD reduce my Medicare premiums?
A QCD can reduce your Medicare premiums by lowering your adjusted gross income below an IRMAA surcharge threshold. Medicare uses your AGI from two years prior to set premiums. Because a QCD keeps IRA income off your return, it can move you into a lower IRMAA tier and shrink your monthly Part B and Part D costs.
What to Do Next
A qualified charitable distribution is one of the few strategies where giving generously and cutting your tax bill point in the same direction. If you are 70½ or older and already write checks to charity, this is worth a serious look before your next required distribution.
Want to go deeper? Our Tax-Smart Charitable Giving Playbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


