

When Should Business Exit Planning Start Before a Sale?
Last reviewed: July 2026
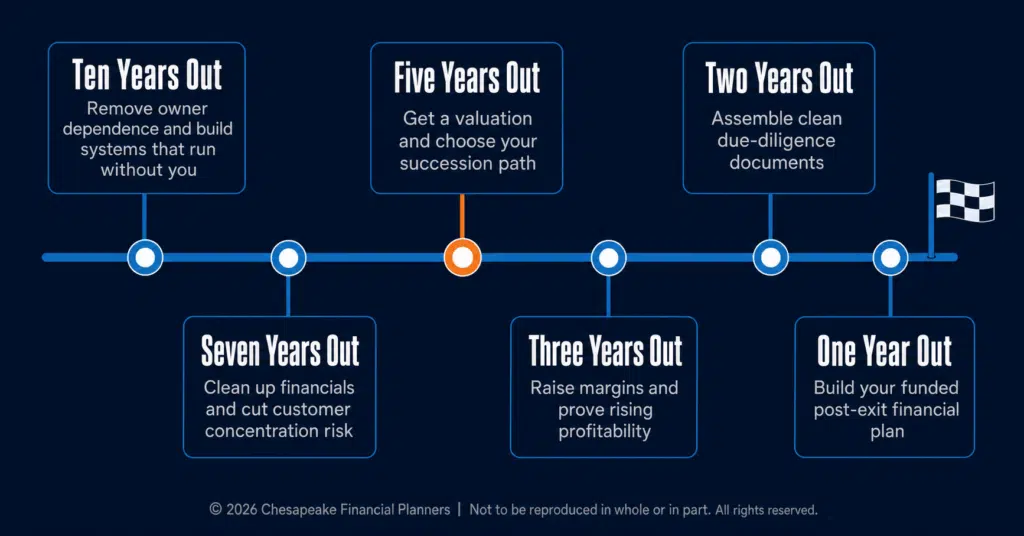
Business exit planning should start roughly ten years before you intend to sell, not the year you decide to. The owners who get the best price and the cleanest transition treat the exit as a decade-long project: they remove their personal dependence from the business early, clean up the financials, get a real valuation, then spend the final years optimizing profit and locking down their own post-sale finances. Start late and you lose leverage, accept a lower number, and hand a chunk of the proceeds back in taxes you could have planned around.
On This Page
- Key Takeaways
- What's on this page
- Why does business exit planning take so long?
- What should you do 10 and 7 years before a sale?
- When should you get a business valuation and pick a successor?
- How do you raise value in the final three years?
- What does due diligence demand two years out?
- How do you build a post-exit financial plan in Maryland?
- Frequently Asked Questions
- Disclosures
Key Takeaways
- Begin business exit planning about ten years out; the earlier you start, the more negotiating leverage and value you control.
- The U.S. Census Bureau reports over half of U.S. business owners are age 55 and over, so the sell-or-transfer wave is already here.
- Buyers weigh your trailing three-year financials most heavily; the last stretch before a sale carries outsized weight on price.
- A Maryland owner faces a $5,000,000 state estate tax exemption, far below the federal $15M, which changes how sale proceeds get planned.
- Your exit only works if your personal financial plan is funded; build it before the deal closes, not after.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate exits, sales, and succession since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's recurring observation: the owners who call him the year before a sale are almost always leaving money on the table that earlier planning would have captured.
Why does business exit planning take so long?
Business exit planning takes years because the things that drive your sale price cannot be fixed quickly. You can repaint a storefront in a weekend. You cannot build a management team that runs without you, prove three years of clean rising margins, or restructure for taxes in the final quarter before closing. Each of those takes time, and buyers can tell the difference between a business that was built to sell and one that was dressed up at the last minute.
The demographics make this urgent. The U.S. Census Bureau found that over half of U.S. business owners are age 55 and over, which means a large share of privately held companies will change hands over the next decade. When a wave of owners tries to sell at once, buyers get to be selective. The business that has its house in order stands out; the one that does not competes on price.
There is a personal-finance dimension too. A SCORE analysis found that 34% of small business owners have no retirement savings plan for themselves, which means for a third of owners the business sale is the retirement plan. If the entire plan rides on one transaction, the stakes on getting that transaction right are enormous, and a rushed exit puts both the company and the owner's future at risk.
Why can't you just prepare in the last year?
You cannot compress exit prep into the last year because the highest-value improvements compound over time. Buyers pay for systems, predictability, and a track record, none of which appear on demand. Jeff Judge often tells Harford County owners that the work you do eight years out is invisible at the time and decisive at the closing table. The owner who delegates real authority in year two of a ten-year runway has a sellable company; the one who tries to delegate in the final six months just looks like a flight risk to a buyer.
What does comprehensive financial planning look like for a business owner?
What should you do 10 and 7 years before a sale?
Ten years out, the single most valuable move is removing owner dependence. A business that runs on your relationships, your judgment, and your presence is worth less and is harder to sell, because the buyer is really buying you, and you are leaving. Strengthen your management bench, document your processes, push decision-making down, and build recurring revenue that does not need your hand on it. Buyers pay for systems, not personalities. This is also when long-term tax structuring should begin, because the earlier your entity and ownership structure are aligned, the fewer tax surprises hit you at exit.
Seven years out, the focus shifts to the financials and to concentration risk. Buyers examine financial stability closely, so clean bookkeeping, reviewed or audited financials, and predictable cash flow all raise your valuation. Just as important, reduce customer concentration. If one client represents an outsized share of revenue, a buyer sees a single point of failure and discounts the price accordingly. The same logic applies to supplier and key-employee concentration. Every liability you eliminate in this window strengthens your negotiating position later.
This is the stage where a structured planning process earns its keep. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For an owner a decade out from a sale, the Review and Recognize step is where you take an honest inventory of how dependent the business is on you, and the Reassess and Refine step is what keeps the plan current as the business and the market change over the years ahead.
What makes a business worth less to a buyer?
A business is worth less to a buyer when it depends on the owner, carries concentrated revenue, or shows messy financials. Those three issues raise a buyer's perceived risk, and buyers price risk by paying less. The fix is unglamorous: build a team that does not need you, spread revenue across many clients, and keep books a buyer's accountant can trust without a forensic dig.
When Is Business Equity Concentration Risk a Liability?
When should you get a business valuation and pick a successor?
Get a formal business valuation about five years before you intend to exit. A professional valuation gives you a baseline: it shows where your company actually stands today and, more useful, where the gaps are between today's number and the number you want. Owners routinely guess high on their own value, and a valuation replaces that guess with evidence you can act on while there is still time to move it. Treat the first valuation as a diagnostic, not a verdict.
Five years out is also when you commit to a succession path, because each path requires different preparation, financing, and governance. The choice is not just emotional; it changes who your buyer is and how the deal gets financed.
| Succession path | Best fit | Main preparation needed |
|---|---|---|
| Internal successor | A capable employee ready to lead | Leadership development, financing the buyout, retention agreements |
| Family transfer | Next-generation family in the business | Governance rules, estate and gift planning, fairness to non-active heirs |
| Management buyout | A strong existing leadership team | Deal financing, equity structuring, seller-note terms |
| External buyer or strategic acquirer | Owner wants a clean break or top price | Market-ready financials, broker or M&A advisor, due-diligence readiness |
Each route interacts with your personal plan differently. A family transfer leans heavily on Maryland estate and gift planning; an external sale leans on getting the financials and legal house buyer-ready. Picking the path early lets you prepare for that specific buyer rather than scrambling to fit whoever shows up.
Should you use an internal successor or an outside buyer?
Choose an internal successor when continuity, culture, and a willing capable leader matter more than top dollar, and choose an outside buyer when maximizing price and making a clean break matter most. Internal transfers are often smoother and slower-paying; external sales can pay more but demand far more diligence prep. Neither is automatically right; the right answer depends on your number and your timeline.
How Do I Know What My Business Is Worth Before Selling?
What do Maryland residents need to know about estate planning?
How do you raise value in the final three years?
In the final three years, raise value by improving margins, refining pricing, and proving consistent profitability, because buyers evaluate trailing three-year performance most heavily. This window carries more weight than the years before it. A buyer looking at your company in the year of sale is reading the last three years of results as the best available predictor of the next three, so a strong, rising trend in this stretch translates almost directly into a higher offer.
Margins are the lever most owners underuse. Refining pricing strategy, trimming the work that does not pay, and tightening operations all flow to the bottom line, and because many businesses sell on a multiple of earnings, a dollar of added profit can become several dollars of added sale price. This is also where the Qualified Business Income deduction, made permanent at 20% by the IRS for pass-through owners, matters: how you take income and structure the business in these years affects both your tax bill now and the entity a buyer inherits.
Leadership is the other half of the equation. Strengthen your second-in-command and the layer beneath them. A capable leadership team that an acquirer can keep protects value and reassures the buyer that the transition will be smooth after you walk away. In Jeff's experience with Bel Air and Forest Hill owners, the businesses that command premium offers are the ones where the founder can take a two-week vacation and nothing breaks. That single test tells a buyer more than any pitch deck.
How much does an extra point of margin affect sale price?
An extra point of margin can move the sale price by several times its annual dollar value because many businesses sell on a multiple of earnings, often somewhere between three and six times. If a business sells at a 5x multiple, one additional dollar of sustainable annual profit can add roughly five dollars to the price. That math is why margin work in the final three years pays off more than almost anything else an owner can do.
What does due diligence demand two years out?
Two years out, due diligence prep means assembling clean corporate records, contracts, financial statements, compliance documents, HR files, and intellectual property documentation so a buyer's team finds no surprises. Buyers scrutinize every detail, and every unanswered question or missing document either slows the deal or becomes a reason to chip the price down. The goal of this stage is to remove friction so negotiations move quickly and from a position of strength.
Start by getting the legal and corporate side in order. Resolve outstanding legal issues, finalize key agreements with customers and suppliers, confirm that leases and licenses are transferable, and make sure all intellectual property is properly owned and documented by the business rather than informally held by you. A buyer who finds a tangle of unsigned contracts or unclear IP ownership will either walk or rewrite the terms in their favor.
Jeff Judge has watched deals stall for months over problems that two years of preparation would have erased: a missing operating agreement, a handshake supplier deal with no paper, an employee classification issue. None of those are hard to fix with lead time. All of them are expensive to fix under deal pressure, when the buyer holds the leverage and the clock is running.
What documents do buyers ask for first?
Buyers ask first for three to five years of financial statements, tax returns, major customer and supplier contracts, the corporate formation and ownership documents, and any leases or loan agreements. Having these organized and current signals a well-run business and shortens diligence. A disorganized data room signals risk, and risk is what buyers use to justify a lower price or tougher terms.
How do you build a post-exit financial plan in Maryland?
Build your post-exit financial plan in the final year before the sale by calculating how much you actually need from the transaction to fund your lifestyle, retirement, and goals, then addressing the tax exposure before the deal closes. Your exit only succeeds if your personal plan is secure. The sale price is not the finish line; the after-tax, after-reinvestment income it produces for the rest of your life is. Run that number first, because it tells you whether the offer on the table is actually enough.
Taxes are where Maryland owners need local guidance, not national rules of thumb. At the federal level, the estate and gift tax exemption sits at $15M per person and $30M per couple under current law, with a top rate of 40%. Maryland is stricter. The state sets its own estate tax exemption at $5,000,000 per person, and Maryland is one of the few states that also levies an inheritance tax. A liquidity event that pushes a Forest Hill or Bel Air owner's estate past $5 million triggers Maryland estate tax planning that the federal numbers alone would never flag.
This is the stage to align every moving part with the liquidity event ahead: your estate plan, any trusts, charitable strategies, and your investment plan. Lifetime gifting can help, since the annual gift tax exclusion lets you move $19,000 per recipient ($38,000 for a married couple) each year without touching your lifetime exemption. Done across several years and several heirs, that adds up. The owners who plan the tax and estate side before signing keep more of the proceeds; the ones who wait until after closing discover the options they no longer have.
For owners across Harford County and the Baltimore metro, this is the heart of what we do at Chesapeake Financial Planners. Our office sits in Forest Hill, a few minutes from Bel Air, and we work with business owners face to face or virtually, the same relationship whether you are around the corner or running a company from out of state. Because we sit inside the Maryland tax environment every day, the post-exit plans we build account for the state estate tax and inheritance tax that catch out-of-area advisors off guard.
How is selling a business in Maryland different from other states?
Selling a business in Maryland differs because of the state's own estate and inheritance taxes layered on top of federal rules. Maryland's $5,000,000 estate tax exemption is far below the federal $15M, so a sale that creates real liquidity can expose a Maryland owner's estate to state tax that a national plan would miss. Maryland also imposes an inheritance tax on certain heirs, which shapes how proceeds are gifted and inherited.
How do I choose a fee-based fiduciary financial advisor in Harford County?
Frequently Asked Questions
How many years before selling should I start exit planning?
Start exit planning about ten years before you intend to sell. A decade gives you time to remove owner dependence, clean up financials, get a valuation, optimize profitability over the buyer-critical trailing three years, and build your personal post-sale plan. Even a five-year runway helps, but the longer the lead time, the more value and negotiating leverage you control at the table.
What makes a business sell for a higher price?
A business sells for a higher price when it runs without the owner, shows clean and rising three-year financials, and carries low customer concentration. Buyers pay for predictable systems and a low-risk transition, not for a founder's personality. Strong margins matter most because many businesses sell on a multiple of earnings, so improving profitability in the final years compounds directly into a higher sale price.
Do I need a business valuation if I'm not selling yet?
Yes, get a valuation roughly five years out even if you are not selling yet. A professional valuation gives you a baseline that shows where your company stands and where the gaps are between today's value and your target number. It turns a guess into evidence you can still act on, while there is enough time to close those gaps before you go to market.
How does selling a business affect my estate taxes in Maryland?
Selling a business can expose a Maryland owner to state estate tax because Maryland's exemption is $5,000,000 per person, far below the federal $15M. A liquidity event that pushes your estate above $5 million may trigger Maryland estate tax, and Maryland also levies an inheritance tax on certain heirs. Coordinating the sale with estate and gift planning before closing helps reduce that exposure.
What is the QBI deduction and does it matter when selling?
The Qualified Business Income (QBI) deduction lets eligible pass-through owners deduct up to 20% of qualified business income, and the IRS made it permanent for tax years after 2025. It matters in the years before a sale because how you structure income and the entity affects both your current tax bill and the business a buyer inherits. Coordinating it with your overall exit tax plan can preserve more of your proceeds.
Should I transfer my business to family or sell to an outside buyer?
Transfer to family when continuity, culture, and keeping the business in the family matter more than top dollar; sell to an outside buyer when maximizing price or making a clean break matters most. Family transfers lean heavily on Maryland estate and gift planning, while outside sales demand market-ready financials and full due-diligence prep. The right path depends on your target number, timeline, and who is ready to lead.
Can I do exit planning myself or do I need an advisor?
You can handle parts of exit planning yourself, but the tax, estate, and valuation pieces usually warrant an advisor, especially in Maryland with its separate estate and inheritance taxes. An advisor coordinates the business sale with your personal financial plan so the proceeds actually fund your retirement. The cost of professional guidance is typically small against the tax and pricing mistakes it prevents.
Most owners do not get a second chance at this. You sell the business you spent decades building exactly once, and the runway you give yourself decides how much of that value you actually keep. If you are a business owner in Harford County or the Baltimore metro weighing an exit in the next several years, now is the right time to put a plan around it. Jeff Judge and the Chesapeake team work through exit and succession planning with owners every week. Schedule a free fit call.
A version of this article originally appeared in Baltimore Business Journal.
Want to go deeper? Our Business Sale Timeline Planner walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


