
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Part of our guide: How Do I Maximize My 401(k) Employer Match?
Whether you should max out your 401(k) or invest elsewhere depends on three things: your emergency fund, your high-interest debt, and the quality of your plan's investment options. If you have cash reserves, no expensive debt, and decent fund choices, maxing out your 401(k) is usually the right move because of the tax shelter and high contribution limit. If any of those three are missing, your extra dollars belong somewhere else first. Knowing where to max out your 401k and where to redirect savings is the difference between a good plan and a great one.
Key Takeaways
- The 2026 401(k) employee contribution limit is $24,500, or $32,500 if you are 50 or older.
- Always contribute enough to capture the full employer match before sending money anywhere else.
- Skip maxing out if you lack an emergency fund or carry credit card debt above roughly 8%.
- A taxable brokerage account adds flexibility your 401(k) cannot, since it has no age-59½ lockup.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate retirement savings decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often points out that the people who ask whether to max out their 401(k) are usually optimizing the wrong number; the order in which you fund your accounts matters far more than squeezing the last dollar into any single one.
When Should You Max Out Your 401(k)?
You should max out your 401(k) when you have a funded emergency reserve, no high-interest debt, and your plan offers low-cost investment options. Under those conditions, the 401(k) is the most efficient wealth-building account most people have access to.
The 2026 employee contribution limit is $24,500, according to the IRS. If you are 50 or older, you can add an $8,000 catch-up for a total of $32,500. Workers ages 60 through 63 get an even larger catch-up of $11,250 under SECURE 2.0 rules. That is a large block of tax-advantaged space compared with an IRA, which the IRS caps at $7,500 in 2026 ($8,600 with the catch-up at 50+).
Three things make maxing out attractive. First, the tax shelter: a Traditional 401(k) lowers your taxable income now, and a Roth 401(k) gives you tax-free withdrawals later. Second, growth happens without annual tax drag. In a taxable account, you owe tax on dividends and realized gains every year, which quietly slows compounding. Third, 401(k) assets carry federal creditor protectionLegal strategies designed to prevent creditors from reaching your assets in the event of a lawsuit or bankruptcy. Certain accounts — like IRAs and 401(k)s — have built-in protections by law, while others require deliberate planning through trusts, LLCs, or state-specific exemptions. under ERISA, which matters if you are a business owner or in a high-liability profession.
There is also a behavioral edge. The money leaves your paycheck before you ever see it, so you never get the chance to spend it. Jeff has watched that automatic discipline build more wealth for clients than any clever investment pick, simply because the contributions never stopped.
When Should You Invest Somewhere Else Instead?
You should invest somewhere other than your 401(k) when you have no emergency fund, when you carry high-interest debt, or when your plan's funds are expensive and limited. In those cases, redirecting dollars produces a better outcome than stuffing more into the plan.
Start with cash. Before maxing any retirement account, hold three to six months of expenses in a high-yield savings account. Retirement accounts punish early access, and a 10% penalty is the last thing you want when a real emergency hits. Building an emergency reserve always comes before maxing contributions.
Next, look at debt. Credit card balances at 18% to 25% interest are a financial fire. Paying them off is a guaranteed return no investment can match, so clear them before you chase the contribution limit. The Federal Reserve reports average credit card interest rates well above 20%, which makes this an easy call.
Then look at your plan itself. Some employer plans offer only high-fee funds with expense ratios above 1%. According to Morningstar, low-cost index funds often run a fraction of that. If your plan is expensive, contribute enough to capture the match, then move extra dollars to a Roth IRA or a low-cost taxable account.
Flexibility is the other reason to look elsewhere. A 401(k) generally locks money until 59½. If you want options before then, a taxable brokerage account has no age restriction and no penalty.
This is also the moment to think about tax diversificationSpreading investments across multiple asset classes, sectors, and geographies so a loss in one area doesn't devastate your entire portfolio. It's the financial equivalent of not putting all your eggs in one basket — and it's one of the few strategies that can reduce risk without necessarily reducing expected returns.. If every retirement dollar sits in a Traditional account, you are setting up a large tax bill in retirement. Splitting contributions between pre-tax and Roth, then layering in taxable savings, gives you control over which bucket you draw from later. The choice between a Roth IRAA retirement account funded with after-tax dollars where your money grows completely tax-free and qualified withdrawals in retirement are also tax-free — including all the gains. There are no Required Minimum Distributions during your lifetime, making the Roth one of the most flexible and powerful long-term savings tools available. vs 401kAn employer-sponsored retirement savings account that lets you contribute pre-tax dollars, reducing your taxable income today while your money grows tax-deferred until retirement. Many employers also match contributions — which is essentially free money you don't want to leave on the table. often comes down to where you expect your tax bracket to land. Jeff Judge notes: "Concentrating every retirement dollar in a traditional pre-tax account feels efficient now, but when required minimum distributionsMandatory annual withdrawals from tax-deferred retirement accounts — like traditional IRAs and 401(k)s — that the IRS requires starting at age 73. RMDs are taxed as ordinary income, and failing to take them triggers a steep penalty, making proactive RMD planning a critical part of any retirement income strategy. hit and you have no Roth or taxable bucket to draw from, you've handed yourself a tax problem with no good exit."
What Is the Right Savings Priority Order?
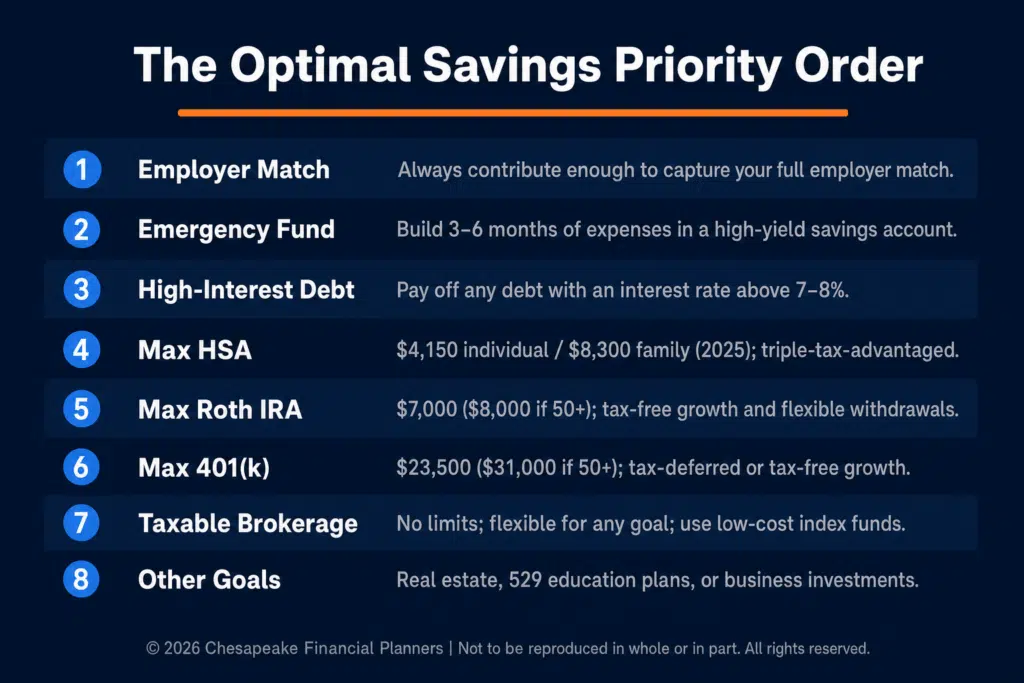
The right retirement savings priority order funds the highest-value dollars first and works down. This sequence keeps you from over-funding one account while neglecting a more urgent need.
- Capture the full employer match. Contribute enough to get every matching dollar. A 50% match is an instant 50% return, and nothing else on this list beats it.
- Pay off high-interest debt. Anything above roughly 8% gets cleared next, because the guaranteed return beats market expectations.
- Build the emergency fund. Three to six months of expenses in liquid, accessible cash.
- Max a Roth IRA if eligible. Tax-free growth and more flexible withdrawal rules than a 401(k).
- Return to the 401(k) and work toward the limit. Now the tax-advantaged space earns its keep.
- Open a taxable brokerage account. This is where flexibility and tax diversification come in once the tax-advantaged accounts are full.
At Chesapeake Financial Planners, we run this exact sequence through the R.U.D.D.E.R. Method™, Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. The framework keeps the decision tied to your full picture rather than a single account.
A Health Savings AccountA triple-tax-advantaged account available to those enrolled in a high-deductible health plan: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. At 65, you can withdraw for any reason and pay ordinary income tax — making the HSA one of the most powerful savings vehicles available. deserves a mention too. If you have a high-deductible health plan, an HSA offers a triple tax benefit that can outrank even the 401(k) for some savers.
Should I Pay Off Debt or Invest My Extra Money?
How much should I save in an emergency fund during a job change?
Roth 401(k) or Traditional 401(k): Which Should I Choose?
Frequently Asked Questions
Should I max out my 401(k) before opening a Roth IRA?
Not necessarily. The smarter order is to capture your full employer match in the 401(k) first, then fund a Roth IRA, then return to max the 401(k). A Roth IRA gives you tax-free growth and more flexible withdrawal rules, so it often earns priority over the final dollars of your 401(k) contribution.
What is the 401(k) contribution limit for 2026?
The 2026 employee contribution limit is $24,500, according to the IRS. If you are 50 or older, you can add an $8,000 catch-up for a combined total of $32,500. Workers ages 60 through 63 qualify for a larger $11,250 catch-up under SECURE 2.0, pushing their total higher still.
Is a taxable brokerage account ever better than a 401(k)?
A taxable brokerage account is better when you need access to money before age 59½ or want tax diversification. It has no contribution limit, no age restriction, and no early-withdrawal penalty. The tradeoff is that you owe tax on dividends and realized gains each year, so it works best after you have captured your match and tax-advantaged space.
Should I keep contributing if my 401(k) has high fees?
Contribute enough to capture the full employer match even in a high-fee plan, because the match outweighs the fees. Beyond the match, redirect extra dollars to a low-cost Roth IRA or taxable account. If your plan funds carry expense ratios above 1%, those costs compound against you over decades and erode returns meaningfully.
Does maxing out my 401(k) lower my taxes?
Yes, if you use a Traditional 401(k). Contributions reduce your taxable income in the year you make them, so a $24,500 contribution in the 24% bracket saves roughly $5,880 in federal tax. A Roth 401(k) does not lower taxes now but delivers tax-free withdrawals in retirement, which can be the better deal depending on your future bracket.
Deciding whether to max out your 401k or invest elsewhere is rarely a one-account question. It depends on your debt, your cash reserves, your plan's fund lineup, and how you want your retirement income taxed years from now. If you want a second set of eyes on where your next dollar should go, Jeff Judge and the Chesapeake team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


