Last reviewed: October 2026
If you set your 401(k) contribution percentage the week you were hired and your RSUs now vest in large tranches, it's probably too low for this year. That rate was sized to a starting salary, not to equity income that can push you into the 32% bracket or higher. Raising your deferrals before a known vest pulls dollars out of your top bracket, up to the 2026 elective deferral limit of $24,500.
Key Takeaways
- Your 401(k) contribution percentage is calibrated to salary, but RSU vesting can lift total pay far above it within a few years.
- Employers often withhold a flat 22% federal rate on supplemental wages like RSU vests, even when your actual bracket is higher.
- Pre-tax deferrals up to $24,500 in 2026 reduce the income taxed at your highest marginal rate, including Maryland and county tax.
- Review your contribution rate at every new grant, promotion, and open enrollment, which is usually two or three checkpoints a year.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate equity compensation and tax planning since earning his CFP® certification in 2013, by using Chesapeake's signature process, the R.U.D.D.E.R. Method™. "The contribution rate you pick at hire is a placeholder," Jeff says. "Nobody tells you it was never meant to last four years."
Why Does the 401(k) Contribution Percentage You Set at Hire Stop Making Sense?
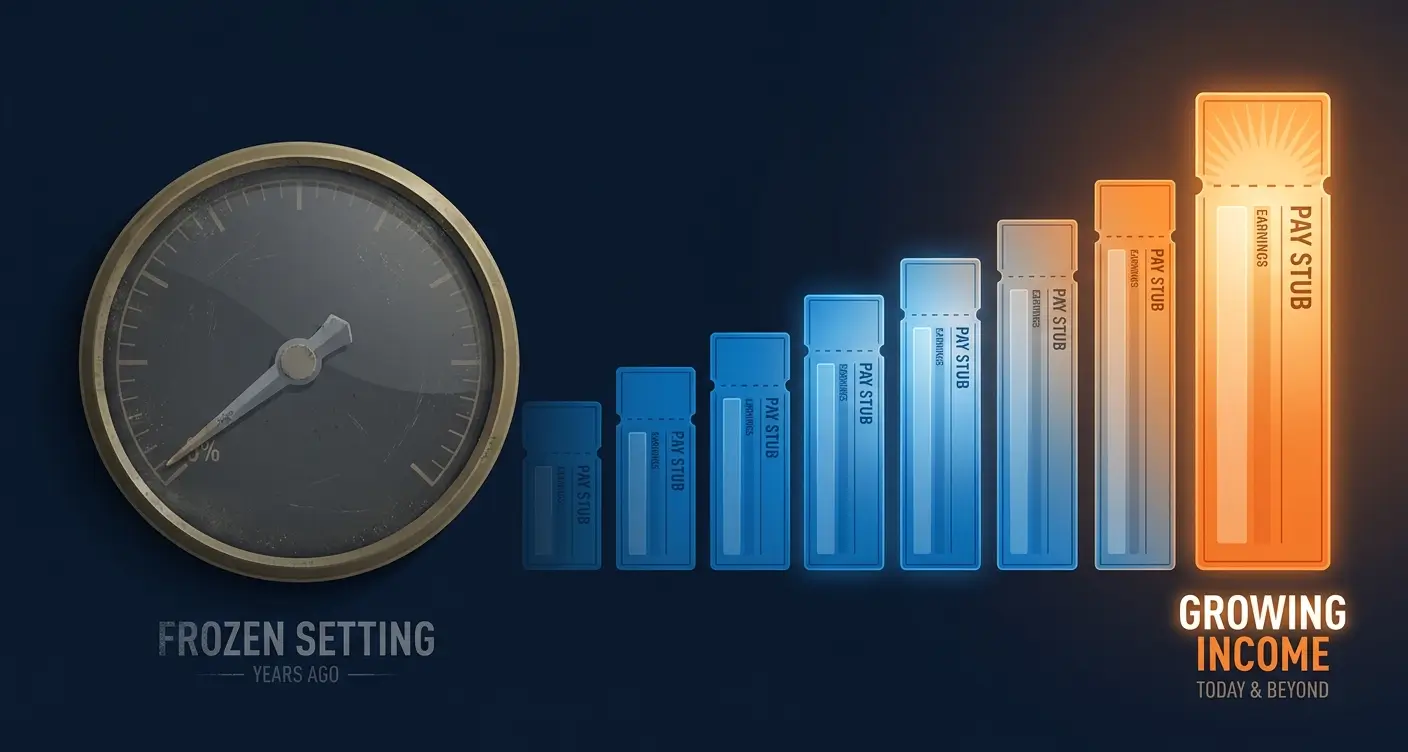
Because it was sized to a number that no longer describes your income. A client of mine vested $340,000 of RSUs one March. His 401(k) rate had been set at 6% the week he started, four years earlier, when base salary was the only income anyone planned around. The vest alone pushed him from the 24% bracket into the 32% bracket, and he had no extra pre-tax room set aside to soften it. A choice made in week one was still running his tax plan in year four.
HR hands every new hire an enrollment form and a default percentage. Most people pick something reasonable, capture the match, and move on. That's sensible on day one. The trouble is that equity doesn't arrive evenly:
- Grants typically vest over four years, and many are back-loaded.
- Refresh grants stack on top of the original award.
- Promotions bring new grants with their own schedules.
By year three or four at a growing company, total compensation can look nothing like the salary that set the original election. When I ask clients when they last looked at their contribution percentage, the answer is rarely "when my pay changed." It's "when I got the auto-escalation notice," or "I don't think I ever have."
Why do analytical people miss this? Because it doesn't feel like a decision. Engineers who track vesting schedules in spreadsheets and know what AMT is still treat the 401(k) election as a setting they configured once. It isn't complicated. It just isn't on anyone's checklist.
How Does RSU Vesting Change Your Tax Bracket?
RSU shares count as ordinary wage income when they vest, and employers commonly withhold federal tax at a flat supplemental rate of 22% on the first $1,000,000 of supplemental wages for the year, rising to 37% above that. If salary plus vesting income lands you in the 32% or 35% bracket, the 22% withholding falls short and the gap becomes an April bill. For a single filer in 2026, the 32% bracket starts at $201,775 of taxable income, per the IRS 2026 inflation adjustments.
"The withholding gap gets all the attention," Jeff Judge says. "The lever sitting right next to it, your own pre-tax deferral rate, almost never does."
Pre-tax 401(k) contributions reduce the income taxed at your top marginal rate in the first place. If you know a big vest is coming, raising your deferral rate in the months before it, or front-loading contributions early in the year, moves dollars out of your highest bracket and into savings instead of into a tax bill. Our guide on why 22% RSU withholding isn't enough covers the withholding side in detail.
There's a cap. Someone earning $180,000 in salary with a $150,000 vesting year won't close the gap through the 401(k) alone. But the room that does exist is often sitting unused because the rate never moved.
Which Years Make an Outdated Contribution Rate Most Expensive?
The mismatch is worst in the years total pay jumps the most:
- The first big vest after a promotion, when a larger grant starts paying out.
- A job change with a new-hire grant, which often begins vesting within a year.
- A refresh grant vesting on top of the original award, stacking two schedules into one tax year.
Those are also the years the original election is furthest from reality. I worked with a software engineer whose total compensation went from $140,000 to $310,000 over three years as her grants matured and she moved into a senior role. Her 401(k) rate stayed at 8% the whole time. Because the percentage applied only to base salary, which grew slowly, the share of her total pay going in pre-tax shrank exactly as her marginal rate climbed. Nobody chose that outcome. The form kept running on autopilot.
That's the mechanical trap. Base pay might rise a few percent a year, while all-in compensation can jump 30% or more once RSUs vest at scale. A rate calibrated to the smaller, slower number can't track the larger, faster one.
Can you contribute beyond $24,500? Workers 50 and older can add an $8,000 catch-up, and those aged 60 to 63 can add $11,250 instead. Under SECURE 2.0 rules taking effect for 2026, higher earners whose prior-year FICA wages exceeded $150,000 generally must make catch-up contributions as Roth, so that slice won't lower this year's taxable income. Confirm how your plan applies the rule.
What Is the Second 401(k) Lever Most People Never Adjust?
If your plan allows after-tax contributions with an in-plan Roth conversion, often called a mega backdoor Roth, there's a second lever next to the first. The IRS caps total annual additions to a 401(k) at $72,000 for 2026, counting your deferrals, employer contributions, and after-tax dollars. Someone who finally raises their pre-tax rate often stops there, unaware the after-tax bucket could absorb tens of thousands more.
I've reviewed plan documents for clients who had been at the same company six years and never knew the feature existed. It wasn't mentioned at onboarding, and it lives in a document most employees never open. In a high-vesting year it matters more, because once the pre-tax limit fills, redirecting extra cash into an after-tax bucket instead of a taxable brokerage account is one of the few remaining ways to keep more of that year's income growing in a tax-advantaged wrapper. Our guide to the mega backdoor Roth for high earners explains the mechanics and the plan features you need.
What if cash flow won't allow it? Raising deferrals ahead of a vest assumes you can live on a smaller paycheck for a few months. A mortgage sized to take-home pay, a spouse with variable income, or a thin emergency fund can make that unrealistic. In that case, run the comparison anyway, know what the extra tax costs, and choose on purpose. "Not this year" is a legitimate answer. Never running the numbers isn't.
How Should Maryland Tech Employees Recheck Their Contribution Rate?
Maryland adds weight to the decision. Maryland calculates state income tax starting from federal adjusted gross income, so pre-tax deferrals generally reduce your Maryland and county taxable income too, not just federal. On top of state rates, local tax is withheld at 3.06% in Harford County and 3.20% in Baltimore County for 2026, and RSU income carries that layer as well.
Here's the arithmetic I run with clients, and it takes about fifteen minutes with a pay stub and a bracket table:
| Step | What to check | Example |
|---|---|---|
| 1 | Projected W-2 income for the year, including the vest | Salary plus a $50,000 vest |
| 2 | Where that total lands against the bracket thresholds | $30,000 of the vest falls into a bracket 10 points higher |
| 3 | Extra federal tax on that slice | Roughly $3,000 |
| 4 | Unused pre-tax room before the annual limit | $15,000 left at your current rate |
| 5 | Deferral increase before the vest date | Redirecting half the room closes a meaningful part of the gap |
Coordinate with whoever prepares your return, too. A CPA who knows a large vest lands in October can tell you whether raising deferrals, adjusting withholding, or paying an estimate makes the most sense for your bracket. For tech and biotech employees across Bel Air, Towson, and the Baltimore corridor, we build that review into the calendar. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Each new grant triggers Reassess and Refine, so the contribution rate gets revisited before the vest, not after the tax bill.
Frequently Asked Questions
What 401(k) contribution percentage should I use in a big RSU vesting year?
There's no single right percentage, but in a big vesting year it should usually be higher than the rate you chose at hire. Project your total income including the vest, find the bracket it lands in, and raise deferrals enough to use your remaining room under the $24,500 limit before the vest date.
Do 401(k) contributions reduce taxes on RSUs?
401(k) contributions don't change how RSUs are taxed, but pre-tax deferrals lower your total taxable wages for the year. Because RSU income stacks on top of salary, every pre-tax dollar you defer comes off income that would otherwise be taxed at your highest marginal rate, federal and Maryland.
Why is my RSU tax withholding too low?
Employers often withhold a flat 22% federal rate on supplemental wages such as RSU vests, up to $1,000,000 for the year. If your salary plus vesting income puts you in the 32%, 35%, or 37% bracket, that flat rate falls short, and the difference shows up as a balance due in April.
How often should I review my 401(k) contribution rate?
Review your 401(k) contribution rate whenever your equity picture changes: each new grant, each promotion, and each open enrollment period. For most tech employees that means two or three checkpoints a year. Jeff Judge suggests pairing each review with a quick projection of the year's total taxable income.
Can I contribute more than the 401(k) limit with RSU income?
The $24,500 elective deferral limit for 2026 applies regardless of income, plus catch-up amounts at 50 and older. If your plan allows after-tax contributions with in-plan Roth conversions, total annual additions can reach $72,000, which lets high earners keep more of a big vesting year in a tax-advantaged account.
Does Maryland tax RSU income?
Yes. Maryland taxes RSU income as wages when shares vest, at state rates plus county local tax, which is withheld at 3.06% in Harford County for 2026. Because Maryland starts from federal adjusted gross income, pre-tax 401(k) deferrals generally reduce Maryland taxable income as well.
Is It Time to Recheck Your Rate Before the Next Vest?
Your 401(k) contribution percentage from week one is a default, not a strategy. Ready to put a plan around yours? Jeff Judge and the Chesapeake Financial Planners team serve families and business owners across Harford County and the Baltimore metro. Schedule a free fit call before your next grant vests.
A version of this article was originally published on Jeff Judge's LinkedIn.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply.
Traditional IRA account owners have considerations to make before performing a Roth IRA conversion. These primarily include income tax consequences on the converted amount in the year of conversion, withdrawal limitations from a Roth IRA, and income limitations for future contributions to a Roth IRA. In addition, if you are required to take a required minimum distribution (RMD) in the year you convert, you must do so before converting to a Roth IRA.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.
Chesapeake Financial Planners | 2402 Scotlon Ct, Forest Hill, MD 21050 | (410) 652-7868 | www.chesapeakefp.com
© 2026 Chesapeake Financial Planners | Not to be reproduced in whole or in part. All rights reserved.


