
How Does Financial Stress Affect Your Mental Health?
Last reviewed: July 2026
Financial stress affects your mental health by triggering chronic anxiety, disrupted sleep, and difficulty concentrating, and it works in both directions: money worries fuel anxiety, and anxiety makes it harder to manage money. This two-way loop is why so many people feel stuck. The good news is that the cycle is breakable. Small, deliberate financial moves lower stress, and lower stress restores the clear thinking you need to make better money decisions. The link between financial stress and mental health is real, but it is not permanent.
Key Takeaways
- Financial stress and mental health feed each other in a two-way loop where money worry and anxiety each make the other worse.
- Roughly 4 in 10 U.S. adults report money negatively affects their mental health, per Bankrate's survey series.
- The American Psychological Association consistently names money among the top sources of stress for U.S. adults.
- Acknowledging the connection, getting clear on your numbers, and stacking small wins are proven ways to break the cycle.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate the emotional side of money decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often tells clients that the spreadsheet is the easy part. The hard part is the 2 a.m. worry that no formula fixes on its own.
How Are Financial Stress and Mental Health Connected?
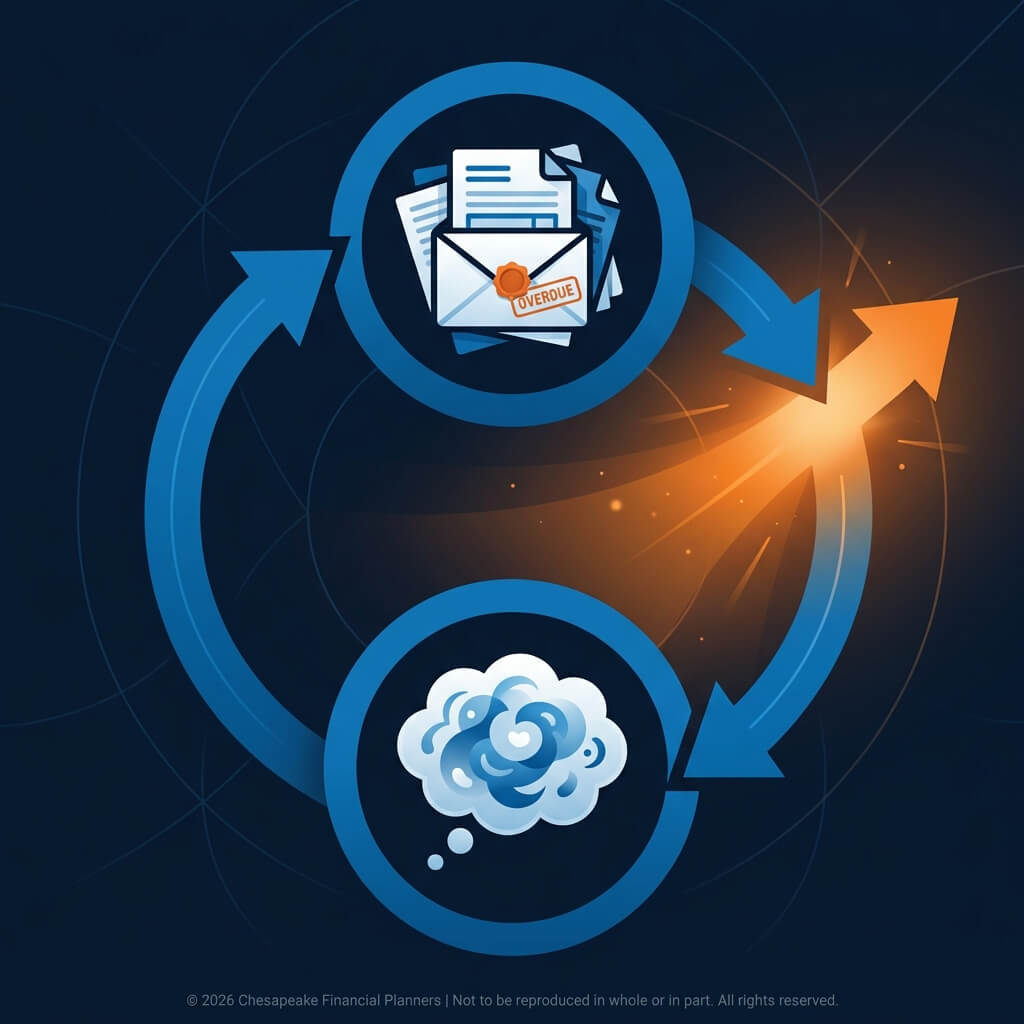
Financial stress and mental health are connected through a two-way loop. Money strain raises your stress hormones and keeps your nervous system on alert, which shows up as poor sleep, irritability, and trouble focusing. At the same time, anxiety and depression make routine money tasks feel impossible, so bills go unopened and decisions get delayed. That avoidance creates new problems, which raises the stress again. Jeff Judge notes: "The avoidance loop is what I watch for — when anxiety about money makes it impossible to open the mail, the pile just gets taller, and a bigger pile creates more anxiety, so the first move is almost always getting the numbers out of your head and onto paper."
The American Psychological Association has tracked money as a leading source of stress for U.S. adults across years of its national surveys. Bankrate's research found that roughly 4 in 10 Americans say money negatively affects their mental health, citing it more often than work or physical health. The pattern holds across income levels, which is why even high earners describe lying awake over money.
For women, the strain often runs deeper. Persistent pay gaps and career interruptions for caregiving compound over time. The U.S. Bureau of Labor Statistics continues to report that women working full time earn meaningfully less than men on a median weekly basis, and that earnings gap widens the long-term savings and security gap that drives money anxiety.
Here is the part most people miss. Because the relationship runs both ways, progress in one area lifts the other. A single financial win lowers anxiety. Clearer thinking produces better financial choices. The loop that traps you can also pull you forward once you tilt it the right way.
What Are the Warning Signs That Money Stress Is Hurting Your Health?
The warning signs that money stress is hurting your health are physical, emotional, and behavioral. Physically, you may notice disrupted sleep, headaches, a racing heart when bills arrive, or appetite changes. Emotionally, you might feel persistent dread, shame about your situation, or a short fuse with the people you love.
The behavioral signs matter most because they quietly make things worse. Watch for avoidance, where you stop opening statements or checking balances. Watch for money paralysis, where every decision feels too heavy to make. And watch for impulse spending used to soothe the very anxiety the spending creates.
In Jeff's experience, the clients who struggle most are not the ones with the worst numbers. They are the ones who have stopped looking. The avoidance feels protective in the moment, but it removes the information you need to act. If you recognize two or three of these signs in yourself, treat that as a signal to engage, not a verdict on your character.
How Do You Break the Financial Stress Cycle?
You break the financial stress cycle by treating the emotional side and the practical side as one problem, then working both with small, repeatable steps. Trying to fix everything at once almost always backfires and deepens the sense of helplessness. The approach below moves you forward without demanding a perfect plan up front.
Acknowledge the connection and get appropriate support
Start by accepting that financial stress affecting your mental health is normal, not a personal failing. Addressing the emotional side is part of solving the money problem, not separate from it. If anxiety or low mood is persistent, consider working with a therapist alongside your financial plan. The National Institute of Mental Health offers guidance on finding mental health support. Pairing emotional support with practical planning is strategic, not weak.
Get clear on your current reality
Financial anxiety thrives in ambiguity. Not knowing exactly where you stand usually feels worse than facing hard numbers. List your income, write down every debt with its rate and minimum payment, track one month of spending without judgment, and calculate your net worth. Most people find that seeing the full picture, even a tough one, lowers anxiety more than avoiding it. You cannot solve what you refuse to look at.
Stack small, achievable wins
When you feel overwhelmed, pick one action you can finish this week. Automate $25 per paycheck into savings. Add $20 to your highest-rate debt. Unsubscribe from the retailer emails that trigger impulse buys. Each win proves change is possible and makes the next step easier. This is also how you begin building an emergency fund, which is one of the single most effective anxiety reducers in personal finance.
Build systems that cut daily decision fatigue
Every money decision drains mental energy, and that fatigue compounds stress. Automate bill payments and savings contributions. Use a simple spending plan with clear categories. Keep separate accounts for fixed expenses and discretionary spending. The goal is fewer daily decisions so you reserve your focus for the choices that truly matter.
Reframe your relationship with money
Shame and comparison amplify financial stress. Replace "I'm terrible with money" with "I'm learning to manage money better." Stop measuring your situation against people whose full story you cannot see. Practice self-compassion when you slip. As Jeff puts it, the story you tell yourself about money shapes your behavior as much as any budget does.
This is also where a repeatable process helps. Chesapeake Financial Planners uses the R.U.D.D.E.R. Method™, a six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A defined process replaces the chaos of constant ad hoc decisions with steady, low-stress momentum.
How Much Should I Have in My Emergency Fund?
What is the best way to pay off debt quickly?
Why Do Your Money Values Matter More Than Your Investment Choices?
What are the fundamentals of personal financial planning?
Frequently Asked Questions
Can financial stress cause physical health problems?
Yes, financial stress can cause physical health problems. Chronic money worry keeps stress hormones elevated, which is linked to sleep disruption, headaches, high blood pressure, and weakened immune function. The body does not separate financial stress from other threats, so prolonged money anxiety produces the same wear-and-tear effects as other chronic stressors over time.
Is it normal for money worries to affect my mental health?
Yes, it is completely normal for money worries to affect your mental health. The American Psychological Association has repeatedly found money ranks among the top sources of stress for U.S. adults, and Bankrate's research shows roughly four in ten people say money harms their mental health. You are not unusual or weak for feeling this. It is one of the most common stressors there is.
How can I reduce financial anxiety quickly?
You can reduce financial anxiety quickly by replacing ambiguity with facts and taking one small, concrete action today. List your income, debts, and spending so you know exactly where you stand. Then complete a single step, such as automating a $25 transfer to savings. Clarity plus one finished action lowers the sense of helplessness faster than waiting for a perfect plan.
Should I see a therapist or a financial planner for money stress?
Often the answer is both, working in parallel. A therapist gives you tools to manage the anxiety, avoidance, and shame around money, while a financial planner builds the practical structure that removes the underlying pressure. Because financial stress and mental health are linked in a two-way loop, addressing only one side usually leaves the cycle intact.
Does financial stress affect women differently than men?
Yes, financial stress often affects women differently. Persistent pay gaps reported by the U.S. Bureau of Labor Statistics, combined with career interruptions for caregiving, widen women's long-term savings and security gaps. Those structural factors can intensify financial anxiety, which is why many women report a heavier mental load around money even at the same income level as male peers.
If you found this helpful, our financial wellness resources cover building stability and reducing money anxiety in more depth. Download our planning starter guide at chesapeakefp.com to take the first practical step toward breaking the cycle between financial stress and mental health.
This content is not intended to provide mental health treatment or medical advice. If you are experiencing persistent distress, please consult a qualified mental health professional.
Want to go deeper? Our 10 Signs You're Ready for a Certified Financial Planner walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


