
What are the fundamentals of personal financial planning?
Last reviewed: July 2026
Personal finance basics are the core money skills that hold a financial life together: budgeting, building an emergency fund, managing debt, saving and investing for the future, protecting yourself with insurance, and planning for retirement and your estate. Master these six and almost every other money decision gets easier. You do not need to be wealthy or a numbers person to get them right; you need a simple framework and the discipline to follow it.
On This Page
- Key Takeaways
- What Personal Finance Basics Actually Cover
- How to Build a Budget and Emergency Fund
- How Saving, Investing, and Debt Fit Together
- Protecting and Planning: Insurance, Retirement, and Estate
- Related Topics Worth Reading
- Frequently Asked Questions
- Starting where you are
- Disclosures
Key Takeaways
- Personal finance basics are six core areas: budgeting, emergency savings, debt management, saving and investing, insurance, and retirement and estate planning.
- A common starting target is three to six months of expenses in an emergency fund before investing aggressively.
- Tax-advantaged accounts are the foundation of long-term saving; you can contribute up to $24,500 to a 401(k) and $7,500 to an IRA in 2026.
- The order matters: stabilize cash flow and high-interest debt first, then build wealth.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area build financial foundations since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: the people who end up wealthy are rarely the ones with the fanciest investments, they are the ones who nailed the boring basics early and kept at them.
What Personal Finance Basics Actually Cover
Personal finance basics are the foundational habits and decisions that determine your financial security, and they break down into six connected areas. None of them requires advanced math or a large income to start. What they require is a system and consistency, because financial health is built far more by steady habits than by occasional big moves.
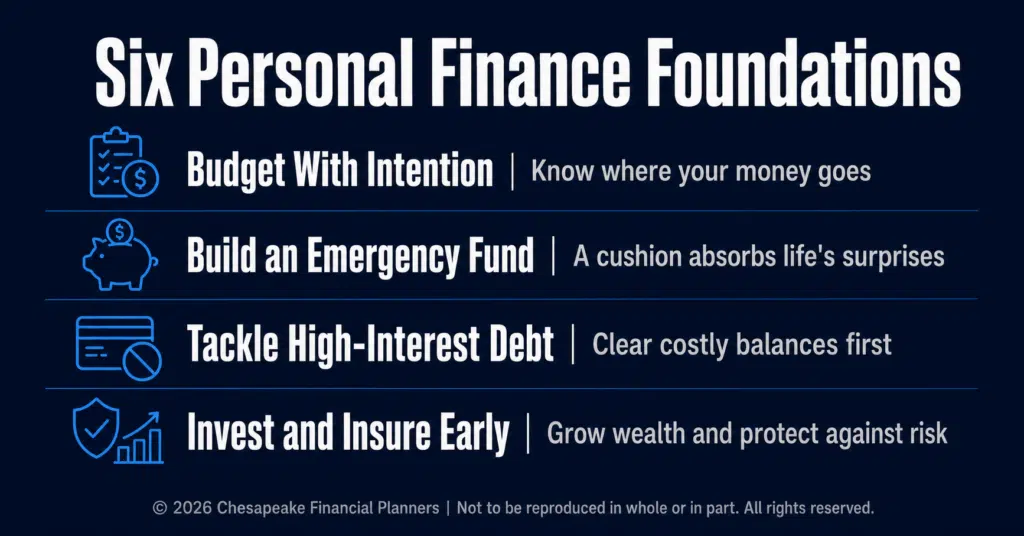
The six areas are budgeting and cash flow, emergency savings, debt management, saving and investing, insurance and risk protection, and retirement and estate planning. They build on each other in a rough order. Cash flow comes first, because you cannot do anything else until you know what comes in and what goes out. Protection and emergency savings come next, so a single bad month does not undo your progress. Then comes the wealth-building work of saving, investing, and planning for the long term.
Think of it as a foundation, not a checklist you finish. You revisit each area as your life changes, but the fundamentals stay the same whether you earn $50,000 or $500,000. The dollar amounts scale; the principles do not.
How to Build a Budget and Emergency Fund
A budget is simply a plan for where your money goes, and an emergency fund is cash set aside so a surprise does not derail that plan. Together they are the foundation everything else rests on, because you cannot invest, insure, or plan well on top of unstable cash flow.
Start by tracking what actually comes in and goes out for a month or two; most people are surprised by the gap between what they think they spend and what they do. A popular framework allocates roughly half of after-tax income to needs, about 30% to wants, and at least 20% to saving and debt payoff, though the right split depends on your situation. The Consumer Financial Protection Bureau offers free worksheets and tools for building a budget, which is a practical place to begin.
The emergency fund is the safety net under the budget. A common guideline is three to six months of essential expenses held in a savings account you can reach quickly, with the higher end for variable income or a single-earner household. As the Consumer Financial Protection Bureau puts it, "Setting up a dedicated savings or emergency fund is one essential way to protect yourself, and it's one of the first steps you can take to start saving." This is the buffer that keeps a job loss or a medical bill from becoming credit card debt. Jeff Judge often tells clients that the emergency fund is the least exciting and most important money they will ever set aside, because it is what lets every other part of the plan survive a bad year.
How Saving, Investing, and Debt Fit Together
Saving, investing, and debt payoff are the wealth-building core of personal finance, and the order you tackle them in matters as much as the effort. The general sequence is to cover the essentials first, then attack high-interest debt, then build long-term investments, because each step makes the next one safer.
High-interest debt, such as credit card balances, usually comes first after a starter emergency fund, since paying off a balance charging high interest is a guaranteed return no investment can promise. Once that is under control, the focus shifts to investing through tax-advantaged accounts, which are the engine of long-term wealth. In 2026 you can contribute up to $24,500 to a 401(k) and $7,500 to an IRA, with an extra $8,000 catch-up in the 401(k) once you turn 50, and capturing any employer match on a 401(k) is the closest thing to free money in personal finance. The SEC's beginner guide to investing explains how to spread savings across asset classes suited to your time horizon.
The mistake I see most often is people treating these as either-or when they are a sequence. As Jeff puts it, "You do not have to choose between paying off debt and investing forever; you have to choose what comes first, and then you do both." Get the order right, automate the contributions, and time does the heavy lifting through compounding.
Protecting and Planning: Insurance, Retirement, and Estate
Insurance, retirement planning, and estate basics are the protective and forward-looking pillars that keep your foundation from cracking under a major life event. The wealth you build means little if a single uninsured disaster or an unplanned death can unravel it, which is why protection belongs in the basics, not the advanced course.
Insurance transfers risks you cannot afford to carry yourself. Health insurance, adequate auto and homeowners or renters coverage, disability insurance to protect your income, and life insurance if others depend on you are the core policies most households need. Retirement planning is the long game: contributing consistently to tax-advantaged accounts, knowing roughly what you will need, and understanding how Social Security fits in. Estate basics round it out, and they are simpler than people fear: a will, beneficiary designations kept current, and powers of attorney for finances and healthcare cover most families. Jeff Judge notes: "Most families are surprised to learn that a current will, updated beneficiary designations, and durable powers of attorney for finances and healthcare will cover the vast majority of estate planning scenarios they are actually likely to face."
A repeatable process keeps all six areas working together instead of in isolation. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. It is built to make sure the basics are not just set up once and forgotten, but reviewed and adjusted as your life moves through its stages.
Related Topics Worth Reading
Each personal finance basic has its own deeper guide. Start with the foundations below.
- How to build an emergency fund and how much is enough. How Much Should I Have in My Emergency Fund?
- The fundamentals of investing for beginners. How do I start investing as a beginner?
- How to pay off debt efficiently with the avalanche or snowball method. What Is the Best Way to Pay Off Debt Fast?
- Setting the right mix of stocks and bonds for your age. How should my investment mix change as I get closer to retirement?
- The estate planning documents every adult should have. What Are the Basics of Estate Planning for High Net Worth?
Frequently Asked Questions
What are the basics of personal finance?
The basics of personal finance are six core areas: budgeting and cash flow, building an emergency fund, managing debt, saving and investing, protecting yourself with insurance, and planning for retirement and your estate. They build on each other, starting with stable cash flow and protection, then moving to long-term wealth building. Mastering these fundamentals matters more than any single investment choice.
How much should I have in an emergency fund?
A common guideline is to keep three to six months of essential living expenses in an easily accessible savings account. Lean toward six months or more if your income is variable, you are self-employed, or your household relies on a single earner. The emergency fund exists to cover surprises like a job loss or medical bill without forcing you into high-interest debt, protecting the rest of your plan.
Should I pay off debt or invest first?
After building a small starter emergency fund, you should generally pay off high-interest debt like credit cards before investing, because eliminating a high interest rate is a guaranteed return no investment can match. The main exception is capturing an employer 401(k) match, which is effectively free money worth grabbing even while paying down debt. Once high-interest debt is gone, shift the focus to investing.
How much can I contribute to a 401(k) and IRA in 2026?
In 2026, you can contribute up to $24,500 to a 401(k) and up to $7,500 to an IRA, per the IRS. Those age 50 and older can add catch-up contributions, and savers between 60 and 63 qualify for a higher 401(k) catch-up. Contributing enough to capture your full employer match should be a top priority, since that match is an immediate return on your savings.
Do I need a financial advisor to manage the basics?
You do not strictly need a financial advisor to handle personal finance basics, since budgeting, emergency savings, and steady investing can be done on your own with discipline. An advisor adds the most value as your situation grows more complex, around retirement timing, tax strategy, business ownership, or estate planning, and as a behavioral check that keeps you on plan during volatile markets.
Starting where you are
The reassuring truth about personal finance basics is that they reward consistency far more than brilliance, so you can start exactly where you are and improve from there. Pick the area that feels weakest, whether that is cash flow, debt, or saving, and strengthen it this month. If you found this helpful and want a roadmap built around your goals, our team at Chesapeake Financial Planners can help you put the fundamentals in place. Visit chesapeakefp.com to learn more about building a foundation that lasts.
Want to go deeper? Our Why Financial Advice Isn’t Just for Retirees walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This material is for educational purposes only. Insurance products contain exclusions, limitations, and terms for keeping them in force. Please contact a qualified insurance professional for costs and complete details.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


