
What Do Business Owners Most Often Forget to Plan Before Exiting?
Last reviewed: July 2026
Business owners most often forget to plan their personal independence number, their tax strategy around the sale, a current business valuation, a succession plan, and what life looks like after the exit. The business is usually the owner's single largest asset, yet the personal financial side of leaving it gets almost no attention until the deal is already on the table. By then, most of the planning options have already closed. Effective business owner exit financial planning connects the value of the company to the owner's personal retirement picture years before the sale.
Key Takeaways
- Most owners never calculate their independence number, the net after-tax sale proceeds that actually make personal retirement viable.
- Tax planning around a sale needs a three-to-five-year runway; once the deal is signed, most strategies close.
- According to the Exit Planning Institute, most owners expect to exit within a decade but few have a written transition plan.
- The Section 1202 QSBS exclusion can shelter up to $10 million in gain when the holding and entity rules are met.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate business exits and succession decisions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched owners walk into a sale knowing every number about their company and almost nothing about whether the proceeds will actually fund the rest of their life.
Why Is the Business Exit the Most Overlooked Financial Event?
For most business owners, the business is the largest asset they own. It frequently represents 70 to 80 percent of total net worth. Yet most owners spend decades thinking about building the company and almost no time thinking about what happens when they leave it. That is the gap that quality business owner exit financial planning is built to close.
The disconnect isn't about apathy. The business took every available hour for thirty years, and nobody helped the owner connect it to the personal financial picture. Jeff Judge has worked with owners across every kind of transition: voluntary sales, forced exits, family successions, and sudden liquidity events. "Business owners are exceptional at building," he says. "They're often completely unprepared for leaving. Not because they don't care about the outcome, but because building consumed everything and the personal side never got attention."
According to the Exit Planning Institute's State of Owner Readiness research, a large majority of owners intend to transition out within ten years, yet only a minority have a written transition plan in place. The gap between intention and preparation costs money, time, and sometimes the outcome itself.
What Are the Five Things Business Owners Most Often Forget?
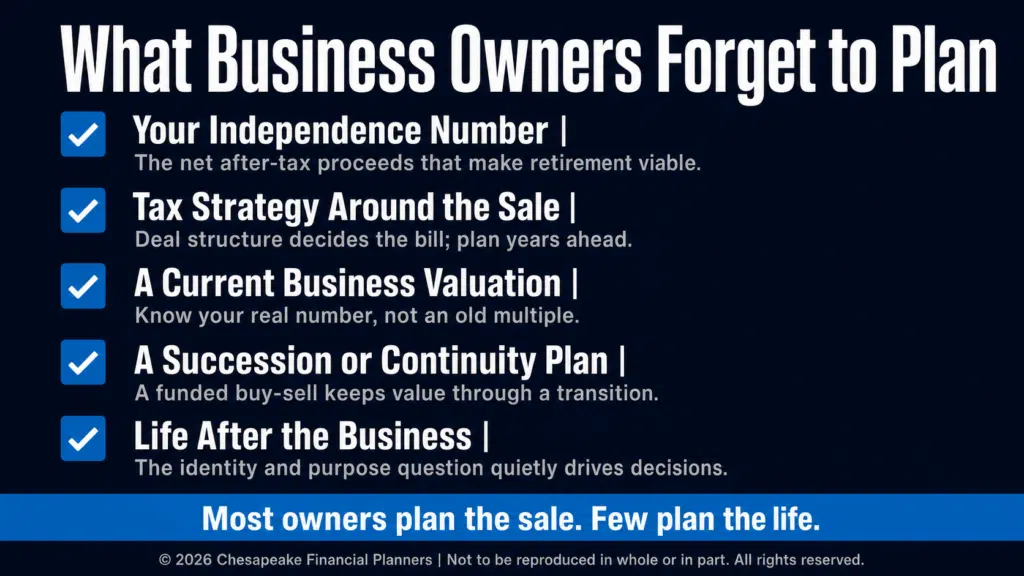
A complete business exit planning process surfaces the items owners overlook. These five show up most consistently.
1. Their personal independence number. Many owners don't actually know whether they can retire if the business sells at the expected valuation. Answering the question requires knowing the real after-tax proceeds, how much personal income those proceeds can support, what other assets exist outside the business, and what the intended lifestyle actually costs. Jeff makes this a priority: "Every owner should know their number, the net proceeds that make personal retirement viable. Without it, they can't negotiate intelligently or decide whether to sell now, grow first, or keep holding."
2. Tax strategy around the sale. The tax bill from a business sale is among the largest financial events a person experiences. Whether proceeds are taxed as ordinary income or capital gains depends on deal structure. The difference between an asset sale and a stock sale alone can mean six figures on a mid-market transaction. Planning three to five years ahead opens options: the Section 1202 Qualified Small Business Stock exclusion can shelter up to $10 million of gain when the rules are met, and installment sales, charitable remainder trusts, and entity restructuring all carry lead times. Once the deal is signed, those doors close.
3. A current business valuation. Owners often carry a mental valuation based on a revenue multiple they heard years ago. Real valuations depend on the industry, customer concentration, how replaceable the owner is, recurring versus project revenue, and margin quality. A current valuation tells the owner whether proceeds will support personal goals, identifies value drivers worth improving before going to market, and prevents painful surprises during due diligence.
4. A succession or continuity plan. What happens to the business if the owner can't run it tomorrow, not eventually but now? Key person insurance, a documented management structure, and a funded buy-sell agreement determine whether the business holds its value through a transition. An agreement drafted when the company was worth $500,000 may not function when it's worth $3 million and the valuation method has been outrun by growth.
5. Life after the business. Most owners haven't answered the underlying question: what do you actually want to do after the exit? The financial plan is solvable. The identity and purpose question is harder, and it quietly drives financial decisions. An owner who hasn't thought it through is more likely to sign a long earn-out that keeps them tethered to the company. Sometimes that's the right call. Sometimes it's avoidance dressed up as deal structure.

How Does the R.U.D.D.E.R. Method™ Address Business Owner Planning?
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. For business owners, each step extends past the personal balance sheet into the company itself.
The Review and Recognize step examines entity structure, owner compensation, key person risk, and exactly how the business intersects with the personal picture. The Uncover and Understand step surfaces the harder question of what the owner wants life to look like after the exit, before deal structure quietly answers it for them. The Design and Develop step coordinates the exit strategy and the personal plan as one exercise rather than two separate plans reconciled at the last minute. The Reassess and Refine step tracks progress against the exit timeline and updates both plans as valuation changes, tax law shifts, or the intended exit date moves.
Jeff's summary captures the integration: "The personal plan and the business plan should be the same plan. Most people keep them separate until they're forced to connect them at the exit. By then, options have closed."
For owners weighing the broader picture, it helps to understand How do business owners plan for retirement differently? and to think through What are the best exit strategies for business owners?. A funded What Is a Buy-Sell Agreement and Why Do Business Partners Need One? sits at the center of most continuity plans.
When Should Business Owners Start This Planning?
The short answer is three to five years before the intended exit, and earlier if the exit is uncertain. That runway gives enough time to restructure for tax efficiency, build a management team, improve value drivers, and align the personal financial plan with realistic sale proceeds. Owners who are still deciding whether to sell benefit from starting even sooner, because the planning process is what reveals the preference. The most common mistake isn't starting late. It's not starting at all. Many owners who already know When should I start valuing my business for a future sale? still postpone the personal side until the buyer is at the table.
Frequently Asked Questions
When should business owners start exit planning?
Business owners should start exit planning three to five years before the intended exit. That window gives enough time to address tax structure, improve value drivers, build a management team, and coordinate the personal financial plan with realistic sale proceeds. Earlier is better, and starting at all is what most owners have never done.
What if I'm not sure when or how I want to exit?
Uncertainty is a useful starting point, not a reason to wait. The R.U.D.D.E.R. Method™'s Uncover and Understand step works directly with ambiguity. Understanding your available options and their consequences is what helps you form a preference. You don't need to have decided how or when to exit before beginning the planning process.
Does Chesapeake coordinate with my CPA and business attorney?
Yes. Business exit planning requires coordination across financial planning, tax strategy, and legal structure, so Chesapeake works alongside your existing CPA and attorney. Where a transaction needs specialized expertise, such as a valuation specialist or M&A counsel, the team can recommend qualified professionals and keep everyone aligned around one integrated plan.
What if the business is a partnership with co-owners?
Partnerships add real complexity: differing exit timelines, different personal financial situations, and sometimes different views on valuation and succession. That makes a funded buy-sell agreement and clear governance documents more important, not less. The planning process needs to account for every owner's situation so the transition doesn't destabilize the business or the partners.
How much of my net worth is usually tied up in the business?
For most owners, the business represents roughly 70 to 80 percent of total net worth, which is why a sale is such a consequential financial event. Concentration at that level means the exit decision drives the entire retirement plan. Diversifying proceeds and stress-testing the personal plan against a realistic valuation are central to the process.
Plan the Exit Before It Plans You
The business exit is one of the most consequential financial events in an owner's life, and the parts owners forget are usually the parts that cost the most. Solid business owner exit financial planning connects the company to the personal picture early enough to keep your options open. If this was helpful, our business owner exit planning guide walks through the full process in depth. Download it at chesapeakefp.com.
Want to go deeper? Our Business Sale Tax Planning Guide walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


