

What does comprehensive financial planning look like for a business owner?
Last reviewed: July 2026
Comprehensive financial planning for a business owner coordinates five areas that most plans treat separately: retirement saving through owner-friendly plans, tax strategy built around your business structure, an exit or succession plan for the day you leave, estate planning that accounts for an illiquid business, and protection against the risks that threaten both your company and your family. The defining challenge is that your business is usually your largest asset, your primary income source, and your retirement plan all at once, which means decisions in one area ripple through the others. A real plan ties them together.
On This Page
- Key Takeaways
- Why is financial planning different for business owners?
- What retirement plans work best for business owners?
- How should business owners approach tax planning?
- How do business owners plan an exit or succession?
- How do estate planning and risk protection fit in?
- Related Topics Worth Reading
- Frequently Asked Questions
- Building a plan as ambitious as your business
- Disclosures
Key Takeaways
- A business owner's plan must coordinate retirement, tax, exit, estate, and protection planning, because the business sits at the center of all five.
- Owner-friendly retirement plans can shelter far more than a standard 401(k); the 2026 defined contribution limit is $72,000, plus catch-ups.
- The 20% qualified business income deduction was made permanent in 2025, a central tax consideration for pass-through owners.
- Most owners have too much net worth tied up in one illiquid asset; diversification and an exit plan address that concentration.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has advised business owners across Harford County and the Baltimore region on retirement, tax, and succession planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff's view: most owners pour everything into the business and assume the business will fund everything later, and the job of real planning is to make sure that assumption is actually true, with money and structure outside the business to back it up.
Why is financial planning different for business owners?
Financial planning is different for business owners because the business is simultaneously their biggest asset, their income, and often their intended retirement fund, which concentrates risk in a way an employee never faces. When one entity plays all three roles, a problem in the business threatens everything at once.
An employee's paycheck, retirement account, and net worth are spread across separate, mostly independent sources. An owner's are fused: a downturn can cut income, stall retirement saving, and erode the value of the asset they planned to sell, all in the same quarter. On top of that, owners carry decisions employees never make, choosing and funding a retirement plan, structuring the business for taxes, planning an eventual exit, and protecting the enterprise from liability and disruption.
This concentration is the through-line of every section below. Good planning for an owner is largely about deliberately building value and security outside the business, so the whole financial life does not rise and fall with one company. Jeff Judge often tells owners that the goal is to make the business a contributor to their wealth, not the sole container for it, because a single illiquid asset is a fragile foundation for a retirement.
What retirement plans work best for business owners?
The retirement plans that work best for business owners are the ones that let owners shelter far more income than a standard employee plan, chiefly the Solo 401(k), SEP-IRA, and, for higher earners, defined benefit and cash balance plans. Choosing the right one depends on your income, whether you have employees, and how much you want to contribute.
A Solo 401(k) suits owners with no employees (other than a spouse) and allows contributions as both employee and employer, letting you reach a high total. A SEP-IRA is simple to administer and allows employer contributions of up to 25% of compensation. Both are bounded by the overall defined contribution limit, which the IRS set at $72,000 for 2026, with the employee 401(k) deferral portion limited to $24,500 (plus an $8,000 catch-up at 50 and older, and a larger catch-up for those aged 60 to 63). For owners with strong, stable profits who want to save aggressively, a defined benefit or cash balance plan can allow contributions well beyond those limits, because the contribution is actuarially determined to fund a future pension benefit.
The right choice is a planning decision, not a default. A high-earning solo consultant might maximize a Solo 401(k); a professional-practice owner in their 50s trying to catch up might add a cash balance plan; an owner with several employees must weigh the cost of contributing on their behalf. The IRS overview of retirement plans for small businesses lays out the options, but matching them to your cash flow and goals is where an advisor earns their keep. Owners who use these plans well often shelter several times what a typical employee can.
How should business owners approach tax planning?
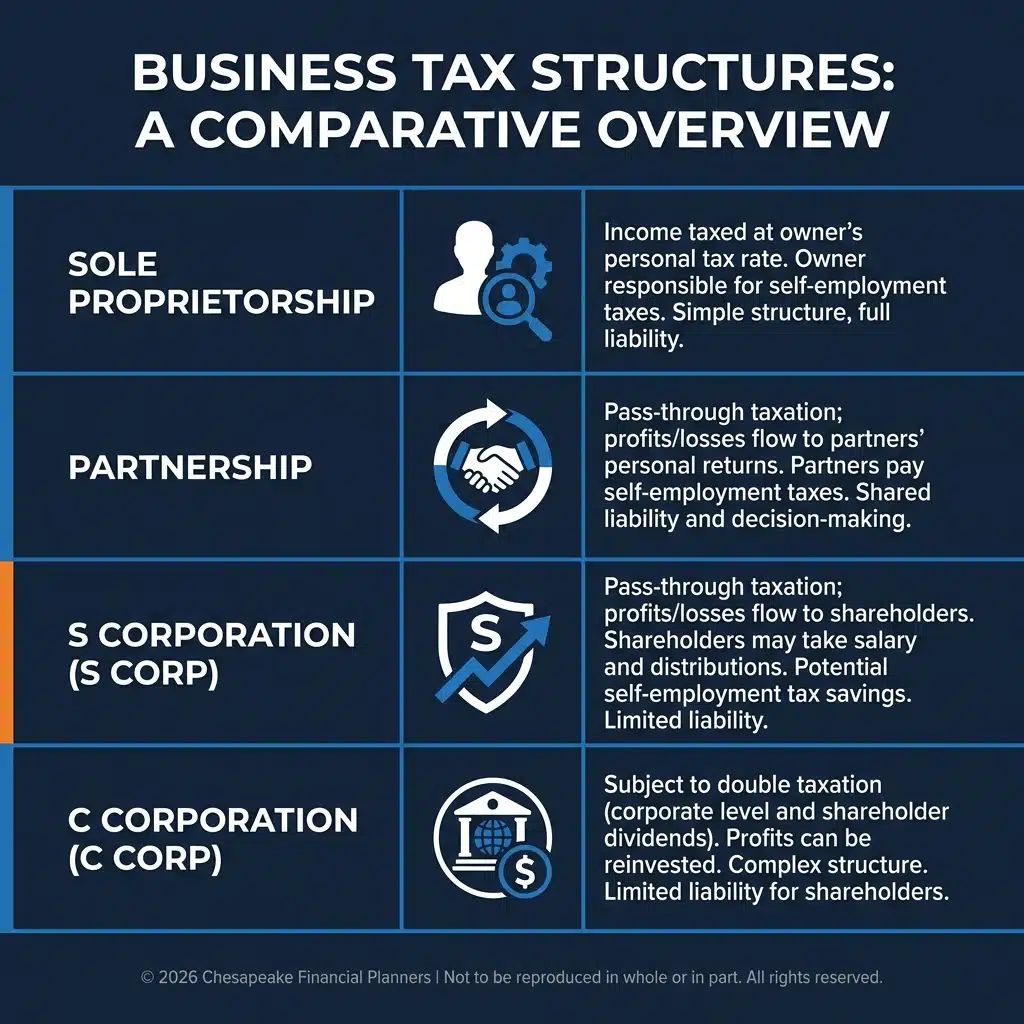
Business owners should approach tax planning as a year-round, structural exercise rather than an April event, because the way a business is organized and operated drives the tax bill more than any single deduction. The biggest levers are entity structure, the qualified business income deduction, and the timing of income and contributions.
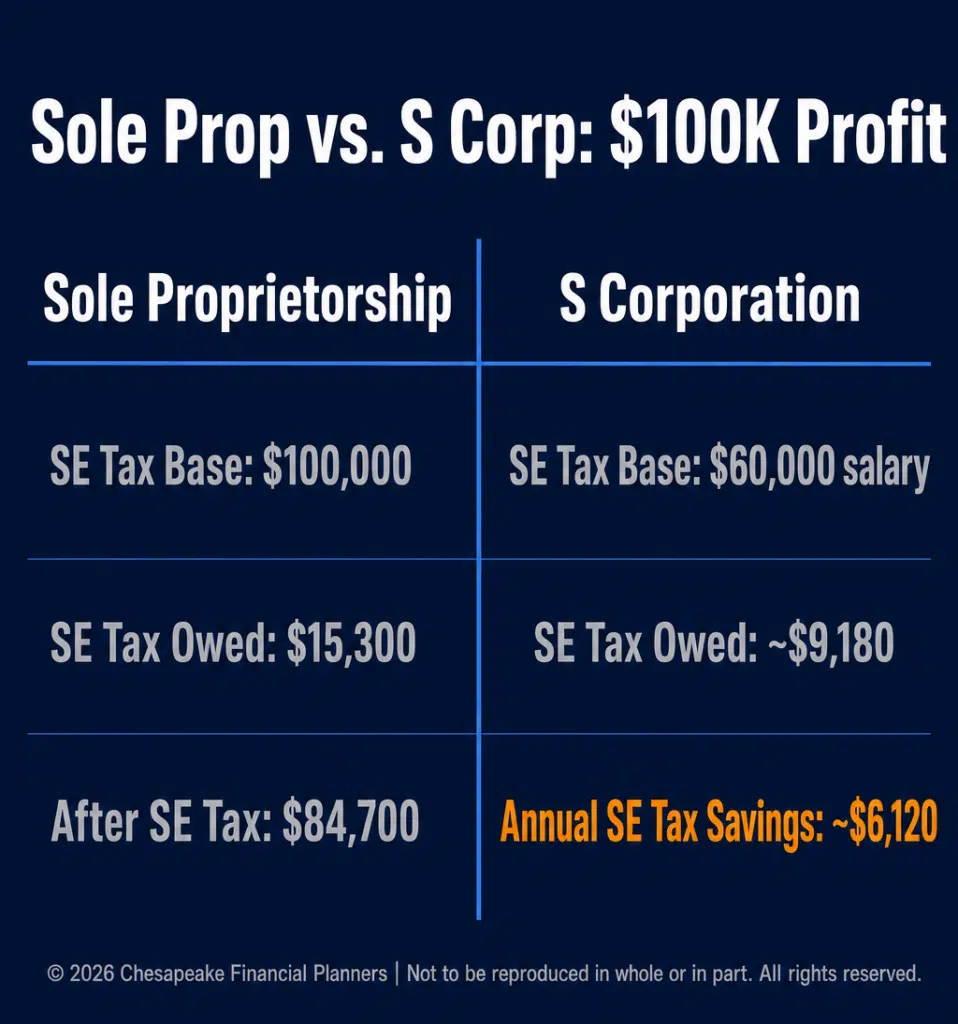
Entity structure comes first. How a business is taxed, as a sole proprietorship, partnership, S corporation, or C corporation, shapes self-employment taxes, owner compensation, and access to certain deductions, and the right structure can change as the business grows. For pass-through owners, the 20% qualified business income (QBI) deduction is a central consideration; it was made permanent by the One Big Beautiful Bill Act in 2025, removing the uncertainty that had surrounded its scheduled expiration, though it phases out and is limited for certain higher-income service businesses. Retirement-plan contributions are themselves a major tax strategy, since dollars sheltered in a Solo 401(k), SEP, or cash balance plan reduce current taxable income while building your own wealth.
Beyond those big levers, owners have tools employees lack: legitimately employing a child in the business, deducting genuine business expenses, and timing income or large purchases to manage brackets across years. The key is coordination, because an S corporation election affects the QBI deduction, which affects how much salary versus distribution makes sense, which affects retirement-plan contributions. This interconnected, multi-variable work is exactly what the R.U.D.D.E.R. Method™ is built for. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and a business owner's tax strategy lives in Design and Develop, where structure, deductions, and contributions are aligned, working alongside your CPA.
How do business owners plan an exit or succession?
Business owners plan an exit or succession by deciding how they will eventually leave, valuing the business realistically, and preparing it to transfer well, ideally years before the actual exit. Because the business is often the largest source of retirement funding, the exit plan and the retirement plan are the same conversation.
There are a handful of common paths: selling to an outside buyer, selling to a partner or co-owner through a buy-sell agreement, transferring to family, selling to employees (including through an ESOP), or simply winding the business down. Each carries different tax, timing, and valuation consequences, and each takes preparation, a business that depends entirely on the owner is hard to sell, while one with documented systems, a capable team, and clean financials commands a better price. A current, realistic valuation is essential, because owners frequently overestimate what their business is worth and build retirement assumptions on that inflated number.
The biggest risk is waiting too long. An owner who plans the exit five or ten years out can groom a successor, reduce the company's dependence on them, time the sale for favorable conditions, and structure the proceeds tax-efficiently. An owner forced to sell suddenly, by health, burnout, or a downturn, usually gets far less. The U.S. Small Business Administration notes that "Many small business owners will face a time when they need to transfer their ownership rights to another person or entity," and it underscores how much preparation a good transition requires. Jeff Judge often reminds owners that the exit is not the end of planning but one of its central events, and the earlier it is designed, the more the business can actually deliver.
How do estate planning and risk protection fit in?
Estate planning and risk protection complete a business owner's plan by protecting the business and family from disruption, lawsuits, and the complications of passing on an illiquid asset. These areas are easy to defer and costly to neglect, because they address exactly the events an owner cannot control.
On estate planning, a business creates complications a simple will does not solve: how to value and divide an illiquid asset among heirs, how to treat children who work in the business versus those who do not, how to provide liquidity so the estate is not forced to sell the company to pay taxes, and how to keep ownership transitions from triggering disputes. Tools like buy-sell agreements, trusts, and life insurance for liquidity are common, and federal estate tax exposure matters for larger estates, though the federal exemption remains high. Maryland owners face an added layer, since Maryland imposes its own estate tax at a lower exemption than the federal one, making state-level planning important.
On protection, owners need to insure against the risks that threaten both the enterprise and their personal finances. Adequate business and personal liability coverage, often including an umbrella policy, guards against lawsuits that could otherwise reach personal assets. Disability insurance is critical, since an owner who cannot work may see the business falter, and key person insurance can protect a company from the loss of an owner or essential employee. Buy-sell agreements funded with insurance ensure a smooth ownership transition if an owner dies or becomes disabled. Together, estate and protection planning make sure that an unexpected event does not unravel everything the owner built, which is the entire point of treating the business as one part of a coordinated plan rather than the whole plan itself.
Related Topics Worth Reading
Business-owner planning connects to taxes, retirement, and estate strategy. These related topics go deeper.
- Comparing the retirement plans owners can use to shelter income. Should I Choose a Solo 401(k) or SEP IRA for My Business?
- Setting a defensible salary under an S corporation. How much salary do I have to pay myself in an S-corp?
- How to invest the proceeds after you sell the business. How should I invest the proceeds after selling my business?
- The agreement that governs a co-owner transition. What Is a Buy-Sell Agreement and Why Do Business Partners Need One?
- A tax strategy for owners with college-age children. Hiring Your Children Tax Strategy: Can I Legitimately Hire My Kids?
Frequently Asked Questions
What does financial planning for a business owner include?
Financial planning for a business owner includes five coordinated areas: retirement saving through owner-friendly plans like a Solo 401(k), SEP-IRA, or cash balance plan; tax strategy built around the business structure and the QBI deduction; exit or succession planning for when the owner leaves; estate planning that handles an illiquid business; and risk protection through liability, disability, and key person insurance. The defining feature is coordination, because the business sits at the center of all five areas.
What is the best retirement plan for a small business owner?
The best plan depends on your income, whether you have employees, and how much you want to contribute. A Solo 401(k) suits owners with no employees and allows both employee and employer contributions; a SEP-IRA is simple and allows up to 25% of compensation; and defined benefit or cash balance plans let high earners contribute well beyond the standard limits. For 2026, the overall defined contribution limit is $72,000, with additional catch-up contributions available at age 50 and older.
How does the QBI deduction work for business owners?
The qualified business income (QBI) deduction lets eligible owners of pass-through businesses, such as sole proprietorships, partnerships, and S corporations, deduct up to 20% of their qualified business income. It was made permanent by the One Big Beautiful Bill Act in 2025. The deduction phases out and is limited for certain higher-income specified service businesses, so how it interacts with your entity structure and income level is an important planning consideration to work through with your advisor and CPA.
When should a business owner start succession planning?
A business owner should start succession planning years before the intended exit, ideally five to ten years out. Early planning allows time to groom a successor, reduce the company's dependence on the owner, improve financial records, obtain a realistic valuation, and structure the eventual sale tax-efficiently. Owners forced to sell suddenly because of health, burnout, or a downturn typically receive far less than those who prepared, which is why the exit is treated as a central planning event rather than an afterthought.
Why do business owners need extra estate and insurance planning?
Business owners need extra estate and insurance planning because an illiquid business complicates passing wealth to heirs and exposes the family to risks an employee does not face. Estate planning addresses how to value and divide the business, provide liquidity for taxes, and treat heirs fairly, while protection planning, liability and umbrella coverage, disability insurance, key person insurance, and funded buy-sell agreements, guards against lawsuits, disability, or death derailing both the company and the family's finances. Maryland owners also face a state estate tax with a lower exemption than the federal one.
Building a plan as ambitious as your business
A business owner's financial plan has to do more than an employee's, because the business is the income, the largest asset, and often the retirement plan all at once. Coordinating retirement saving, tax strategy, an exit plan, estate planning, and risk protection is what turns that concentrated bet into durable, diversified security, with value and protection deliberately built outside the company as well as in it. Jeff Judge and the Chesapeake Financial Planners team help owners across Harford County and the Baltimore metro build that kind of coordinated plan, working alongside their CPAs and attorneys. Schedule a free fit call at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
CFP Board owns the marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the U.S.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


