
Published: | Last reviewed: July 2026 by Jeff Judge, CFP®
Estate planning for Maryland residents means dealing with two state-level death taxes that most of the country doesn't face: a $5 million estate tax exemption and a separate 10% inheritance tax. According to the Maryland Comptroller, Maryland's estate tax exemption sits at $5 million per person, far below the federal exemption. That gap is where most Maryland families get caught. If your estate is worth more than $5 million, or you plan to leave assets to anyone other than a spouse, child, or close relative, you have planning to do well before anything happens.
On This Page
- Key Takeaways
- Why Is Estate Planning Different for Maryland Residents?
- How Does the Maryland Estate Tax Work?
- What Is the Maryland Inheritance Tax?
- Should Maryland Residents Use a Will or a Trust?
- How Can Maryland Residents Avoid Probate?
- What Should Maryland Business Owners Know About Estate Planning?
- Frequently Asked Questions
- Next Steps for Your Maryland Estate Plan
- Disclosures
Key Takeaways
- Maryland levies both an estate tax and an inheritance tax, one of only a handful of states that does, per the Tax Foundation.
- Maryland's estate tax exemption is $5 million, far below the 2026 federal exemption of $15 million.
- Maryland's inheritance tax is 10% on transfers to non-exempt beneficiaries like nieces, nephews, and friends.
- A revocable living trust can keep your estate out of Maryland probate, which is public and can take months.
- Married couples should plan deliberately because Maryland allows portability of a deceased spouse's unused Maryland exclusion only with its own election on a timely filed Maryland estate tax return (MET 1, Schedule F); it is not automatic.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate estate planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff sees the same surprise over and over: families assume the federal exemption protects them, then learn Maryland starts taxing estates at a fraction of that number.
Why Is Estate Planning Different for Maryland Residents?
Maryland is one of only a handful of states that imposes both an estate tax and an inheritance tax. According to the Tax Foundation, most states have repealed their death taxes entirely over the past two decades. Maryland kept both. That makes estate planning here a different exercise than it would be for someone in Virginia or Florida.
What does that mean for a typical Harford County family?
It means the federal exemption is not your finish line. The 2026 federal estate tax exemption is $15 million per individual, raised under the One Big Beautiful Bill Act. A family with a $4 million estate owes no federal estate tax and feels safe. But Maryland's exemption is only $5 million, and Maryland spousal portability is not automatic. A surviving spouse can claim the deceased spouse's unused exemption only if the first spouse's estate files a timely Maryland estate tax return and elects it. Jeff Judge often tells clients in Bel Air and Forest Hill that the planning isn't about avoiding a federal problem most of them will never have. It's about the state-level taxes that hit estates a quarter of the size.
This is exactly the kind of situation the Maryland estate tax exemption explained resource walks through in detail.
How Does the Maryland Estate Tax Work?
The Maryland estate tax applies to estates that exceed the $5 million exemption, and the tax is calculated on the amount above that threshold. According to the Maryland Comptroller, the Maryland estate tax is computed at a 16% rate. The tax is owed by the estate itself, paid before assets pass to heirs.
Here is where married couples in Maryland need to pay attention. The federal system lets a surviving spouse inherit the deceased spouse's unused exemption through portability. Maryland allows a surviving spouse to use a deceased spouse's unused Maryland exclusion, but only if the executor elects it on a timely filed Maryland estate taxA federal (and sometimes state) tax on the transfer of assets to heirs at death, assessed on the total estate value above the applicable exemption. The federal exemption is $15 million per person in 2026: the 2025 law known as the One Big Beautiful Bill Act set it at that level, indexed for inflation after 2026, with no scheduled sunset. return (MET 1, Schedule F). If a husband dies, leaves everything to his wife, and no one files that election, his $5 million Maryland exemption can be wasted. When she later passes, her estate gets only her own $5 million exemption, not the combined $10 million the couple could have sheltered with proper planning.
Can a married couple protect both Maryland exemptions?
Yes, but it takes deliberate structure, usually a credit shelter trust (sometimes called a bypass trust) built into the estate plan. The first spouse's assets fund the trust up to the $5 million Maryland exemption rather than passing outright to the survivor. The surviving spouse can still benefit from those assets during life, but they stay out of her taxable estate at the second death. This is one of the most common fixes Jeff builds for couples with combined estates between $5 million and $10 million. Without it, a couple can hand Maryland a tax bill that simple planning would have erased.
This planning connects directly to the credit shelter trusts for married couples strategy, which deserves its own conversation.
What Is the Maryland Inheritance Tax?
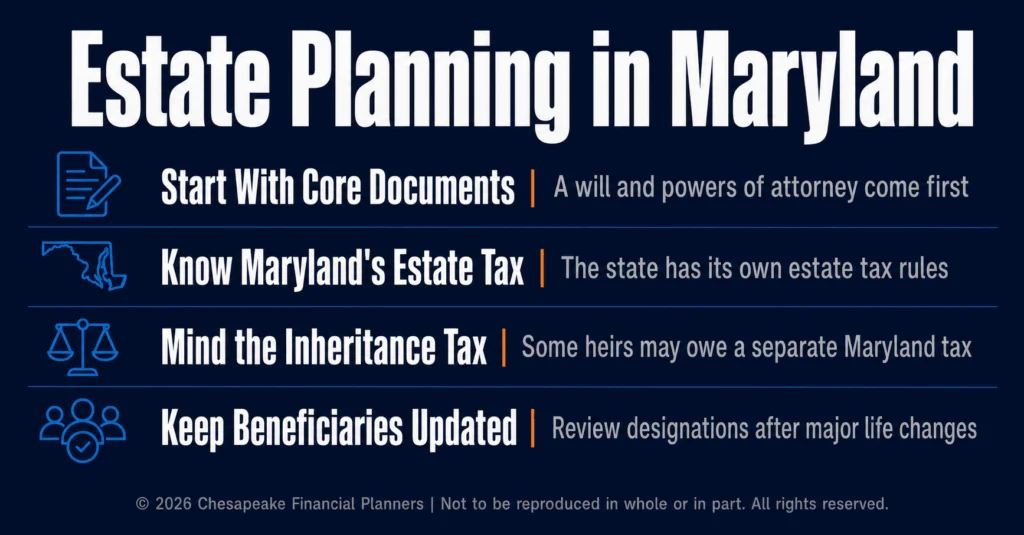
The Maryland inheritance tax is a 10% tax on the value of property passing to certain beneficiaries, and it is completely separate from the estate tax. According to the Maryland Comptroller, the tax depends on who inherits, not on the size of the estate.
The good news for most families: close relatives are exempt. Spouses, children, grandchildren, parents, grandparents, and siblings pay no Maryland inheritance tax. The 10% rate hits everyone else, which in practice means nieces, nephews, cousins, friends, and unmarried partners.
Who actually pays the Maryland inheritance tax?
The 10% applies to transfers to non-exempt beneficiariesThe people or entities designated to receive your assets when you die — through retirement accounts, life insurance policies, or trusts. Keeping beneficiary designations current is one of the simplest but most overlooked parts of estate planning, and outdated designations can completely override what your will says.. A Forest Hill resident who leaves $200,000 to a favorite niece triggers a $20,000 inheritance tax on that gift, even if the estate is far below the estate tax exemption. Jeff has watched this catch people off guard repeatedly, because the inheritance tax has no minimum threshold. It applies to the first dollar passing to a non-exempt person. For clients who want to leave money to nieces, nephews, or close friends, this single rule reshapes how the plan should be written.
The Maryland inheritance tax beneficiary rules breakdown covers exactly who is exempt and who is not.
Should Maryland Residents Use a Will or a Trust?
A will directs where your assets go but still passes through probate; a revocable living trustA trust you create and maintain full control over during your lifetime, with assets transferring seamlessly to heirs at death — bypassing probate. You can change or dissolve it at any time, though unlike an irrevocable trust, it doesn't offer estate tax reduction or creditor protection. can move assets to your heirs privately and avoid the Maryland probate process entirely. Both have a place, and the right Maryland estate plan often uses both.
A will is the foundation. It names guardians for minor children, designates an executor, and directs assets that aren't otherwise titled. Every adult in Maryland should have one. But a will alone means your estate goes through probate, a court-supervised process that is public record and can take several months in Harford County.
A revocable living trust changes that. Assets titled in the trust pass to beneficiaries under the trust terms without probate. For Maryland families, the trust also creates the framework for tax planning, including the credit shelter trust structure that preserves both spouses' estate tax exemptions.
| Feature | Will | Revocable Living Trust |
|---|---|---|
| Avoids probate | No | Yes, for funded assets |
| Public record | Yes | No |
| Names guardians for minors | Yes | No (handled by will) |
| Enables Maryland estate tax planning | Limited | Yes |
| Effective during incapacity | No | Yes |
| Cost to set up | Lower | Higher |
The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Estate documents fall into the Design and Develop and Execute and Empower stages, but the work starts earlier, with understanding what you actually own and how it's titled.
This is where the Should I Get a Trust or Is a Will Enough? guide goes deeper on the tradeoffs.
How Can Maryland Residents Avoid Probate?
Maryland residents avoid probate primarily by titling assets so they pass outside the probate estate, through trusts, beneficiary designations, and joint ownership. Probate in Maryland is handled by the Register of Wills in each county, and according to the Maryland Register of Wills, the process involves court filings, creditor notice periods, and public record.
The main tools to keep assets out of probate:
- Fund a revocable living trust. Assets titled in the trust avoid probate entirely.
- Use beneficiary designations. Retirement accounts, life insurance, and annuities pass directly to named beneficiaries.
- Add payable-on-death or transfer-on-death designations. Bank and brokerage accounts can pass directly to a named person.
- Hold property jointly with right of survivorship. Jointly titled property passes to the surviving owner automatically.
Does avoiding probate also avoid Maryland estate tax?
No, and this is a critical distinction. Avoiding probate is about how assets transfer, not about whether they're taxed. Assets in a revocable trust, jointly held property, and accounts with beneficiary designations are all still part of your taxable estate for Maryland estate tax purposes. Jeff makes this point with nearly every client who walks in believing a living trust eliminates the tax. It eliminates the probate process. The $5 million exemption still applies to everything you owned at death. Probate avoidanceLegal strategies that allow assets to transfer directly to heirs without going through the court-supervised probate process. Techniques include beneficiary designations, joint tenancy, revocable living trusts, and transfer-on-death accounts — all of which can save your family time, money, and public scrutiny. and tax avoidance are two different jobs that require two different plans.
For families weighing these tools, the How Can I Avoid Probate for My Estate in Maryland? resource lays out each option.
What Should Maryland Business Owners Know About Estate Planning?
Business owners in Maryland face a layered estate planning challenge because the business is often the largest, least liquid asset in the estate. According to the Small Business Administration, succession planning is one of the most overlooked parts of running a closely held company. For a Harford County business owner, the estate tax and the business exit decision are the same conversation.
The problem is liquidity. If a business owner dies with a $6 million estate, much of it tied up in the company, Maryland estate tax is owed in cash within nine months. The family may have a tax bill but no easy way to pay it without selling or borrowing against the business. This is the scenario Jeff works hardest to prevent.
How do Maryland business owners create liquidity for estate taxes?
The most common solution is life insurance held inside an irrevocable life insurance trust (ILIT), which provides tax-free cash to pay the estate tax without inflating the taxable estate further. Other tools include buy-sell agreements funded with insurance, family limited partnerships, and gifting strategies that move business value out of the estate over time. For a business owner in Forest Hill or Bel Air, getting this right protects both the family and the business they spent decades building. The [Maryland business succession planning] question deserves its own deep dive, which the business succession planning in Maryland guide provides.
Business owners weighing a sale should also review the estate tax liquidity strategies options before assuming insurance is the only answer. And anyone with a closely held company should understand how What is an ILIT, and how does it keep life insurance out of my estate? fit into a Maryland plan.
At Chesapeake Financial Planners, we sit at 2402 Scotlon Ct in Forest Hill, and most of the families we work through estate planning with live right here in Harford County and the surrounding Baltimore metro. The Maryland estate tax and inheritance tax aren't abstract for our clients. They're the specific reason a Bel Air family with a paid-off home, a brokerage account, and a small business can cross the $5 million line without realizing it. That local lens is why we treat Maryland estate planning as its own discipline, not a national template with a Maryland sticker on it.
Frequently Asked Questions
What is the Maryland estate tax exemption for 2026?
Maryland's estate tax exemption is $5 million per individual, according to the Maryland Comptroller. Estates that exceed $5 million owe Maryland estate tax on the amount above that threshold, at 16%. This exemption is far below the 2026 federal exemption of $15 million per person.
Does Maryland have an inheritance tax?
Yes, Maryland imposes a 10% inheritance tax on property passing to certain beneficiaries, separate from the estate tax. Spouses, children, grandchildren, parents, and siblings are exempt. The 10% rate applies to transfers to nieces, nephews, cousins, friends, and unmarried partners, with no minimum threshold.
Can married couples in Maryland double their estate tax exemption?
Yes, but it requires deliberate planning: Maryland allows spousal portability only when the first spouse's estate files a timely Maryland estate tax return and elects it. A credit shelter trust built into the estate plan can preserve the first spouse's $5 million exemption, allowing a couple to shelter up to $10 million. Without the election or this structure, the first exemption is often wasted.
Does a living trust avoid Maryland estate tax?
No, a revocable living trust avoids probate but does not avoid Maryland estate tax. Assets in a revocable trust remain part of your taxable estate. The trust keeps your estate private and out of court, but the $5 million Maryland exemption still applies to everything you owned at death.
How long does probate take in Maryland?
Probate in Maryland is handled by the Register of Wills in each county and typically takes several months to over a year, depending on the estate's complexity. The process involves court filings, a creditor notice period, and public record. Funding a revocable living trust is the most common way to avoid it entirely.
Do Maryland business owners need special estate planning?
Yes, Maryland business owners need estate planning that addresses liquidity, because the business is often the largest and least liquid asset. Estate tax is owed in cash within nine months of death. Tools like irrevocable life insurance trusts and buy-sell agreements create the cash needed without forcing a sale of the company.
Who is exempt from Maryland inheritance tax?
Spouses, children, grandchildren, parents, grandparents, and siblings are exempt from the Maryland inheritance tax. The 10% tax applies only to transfers to more distant relatives and non-relatives, including nieces, nephews, cousins, friends, and unmarried partners. There is no minimum threshold before the tax applies.
Next Steps for Your Maryland Estate Plan
Maryland's combination of a $5 million estate tax exemption and a 10% inheritance tax means estate planning Maryland residents rely on has to be built for this state specifically, not borrowed from a national checklist. At Chesapeake Financial Planners, we work through these exact decisions with families and business owners across Harford County and the Baltimore metro every week. If you're weighing how the estate tax, inheritance tax, and your business exit fit together, a conversation costs you nothing. Schedule a free fit call at chesapeakefp.com.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


