
What do Maryland residents need to know about taxes and benefits before retiring?
Last reviewed: July 2026
Retiring in Maryland is more tax-friendly for retirees than many people assume: the state does not tax Social Security benefits, and residents 65 and older can exclude a meaningful amount of pension income. Maryland still taxes most other retirement income and adds a county tax on top of the state rate, so the picture is mixed rather than simply good or bad. Knowing which income Maryland taxes, which it exempts, and how the local rules in places like Harford County apply is the key to planning your retirement income efficiently.
On This Page
- Key Takeaways
- Does Maryland tax Social Security and retirement income?
- How does Maryland's pension exclusion work?
- What about Maryland estate and inheritance taxes?
- Related Topics Worth Reading
- Frequently Asked Questions
- Planning a Maryland retirement that keeps more of your money
- Disclosures
Key Takeaways
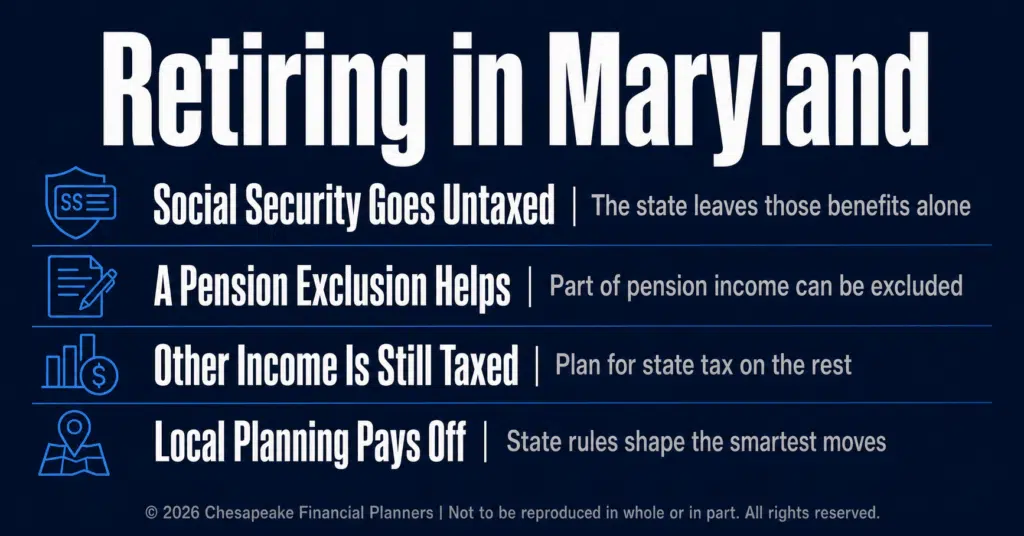
- Maryland does not tax Social Security benefits, so that income is fully exempt from state income tax.
- Residents 65 or older may exclude up to $40,600 of qualifying pension income in 2026 under Maryland's pension exclusion.
- Maryland taxes most other retirement income, with a top state rate of 5.75% plus a county income tax that varies by jurisdiction.
- Maryland is one of the few states with both an estate tax and an inheritance tax, which matters for Harford County families with larger estates.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has spent more than a decade helping Harford County and Baltimore-area families plan their retirement income, and Maryland's specific rules are part of nearly every conversation, by using Chesapeake Financial Planners' signature process, the R.U.D.D.E.R. method™. Jeff's view: the biggest Maryland retirement surprise he corrects is the belief that the state taxes Social Security; it does not, and that single fact changes a lot of plans for the better.
Does Maryland tax Social Security and retirement income?
Maryland does not tax Social Security benefits at all, but it does tax most other retirement income, which makes the state moderately friendly rather than a true tax haven for retirees. If a neighbor told you Maryland taxes Social Security, they were mistaken; the state fully exempts those benefits from income tax, the same as most states do.
Beyond Social Security, the rules shift. Withdrawals from traditional IRAs and 401(k)s, most pension income, and annuity payments are generally subject to Maryland income tax. The state's rates run from a low bracket up to a top marginal rate of 5.75%, and every Maryland resident also pays a county income tax on top of that, which varies by jurisdiction. You can see the current brackets on the Maryland Comptroller's tax rate page. For a Harford County retiree, the 2026 local income tax rate of 3.06% sits on top of the state rate, so that combined number is what actually matters when planning withdrawals.
The practical takeaway is that where your retirement income comes from changes your Maryland tax bill. A retiree living mostly on Social Security owes Maryland very little; one drawing heavily from a traditional 401(k) owes considerably more. That difference is exactly what good withdrawal planning can manage.
How does Maryland's pension exclusion work?
Maryland's pension exclusion lets residents who are 65 or older, or totally disabled, subtract a portion of their qualifying pension income from state taxable income, which can meaningfully lower the tax on retirement income. For 2026, the maximum pension exclusion is $40,600.
The details matter, because not all retirement income qualifies. The exclusion applies to pensions and annuities from an employee retirement system, such as qualified defined benefit and defined contribution plans, 401(k)s, 403(b)s, and 457(b) plans. Income from a traditional IRA, a Roth IRA, a SEP, or a Keogh plan does not qualify for this particular exclusion. There is also an interaction with Social Security: because Maryland already exempts Social Security, the amount of Social Security you receive reduces the pension exclusion you can claim, which the state's worksheet calculates for you.
This is one of those rules where a small amount of planning pays off. As Jeff Judge tells Harford County clients, "The pension exclusion rewards retirees who understand which accounts feed it, so coordinating IRA and pension withdrawals around it is a routine part of building a Maryland retirement income plan."
What about Maryland estate and inheritance taxes?
Maryland is one of the few states that levies both an estate tax and an inheritance tax, which makes estate planning especially important for Harford County families with larger or more complex estates. These are separate from income tax and apply at death rather than during retirement, but they belong in any complete Maryland retirement plan.
The Maryland estate tax applies to estates above the state exemption, which sits at $5 million per person, well below the federal exemption, so a family can owe Maryland estate tax while owing nothing federally. The Maryland inheritance tax is different: it taxes certain beneficiaries based on their relationship to the deceased. According to the Maryland Register of Wills, "For decedents dying on or after July 1, 2000, direct or lineal heirs are exempt from inheritance tax," while more distant heirs face a tax on what they inherit. The combination means a Maryland estate plan has to consider both layers.
For most retirees this is a planning opportunity, not a crisis. Tools like trusts, lifetime gifting, and charitable strategies can reduce or eliminate Maryland estate tax exposure, and the inheritance tax can often be planned around by how assets are structured and who is named to receive them. A repeatable process keeps it organized. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine, and Maryland's estate and inheritance rules get addressed in the Design and Develop step alongside the income plan.
Related Topics Worth Reading
Retiring in Maryland touches income tax, estate tax, and Social Security timing. These related topics go deeper on each.
- The specifics of Maryland's estate and inheritance tax and who pays. How do Maryland's estate tax and inheritance tax work together, and how do you plan around both?
- How Maryland's inheritance tax treats different heirs. Who owes Maryland's 10% inheritance tax and what planning options protect non-lineal heirs?
- How to build retirement income that lasts across a long retirement. What is the best retirement income planning strategy?
- When delaying Social Security makes sense as part of your plan. How do you maximize Social Security and Medicare benefits in retirement?
- Tax planning specific to Maryland retirees. How Can Maryland Retirees Reduce Their State Tax Burden?
Frequently Asked Questions
Does Maryland tax Social Security benefits?
No, Maryland does not tax Social Security benefits. They are fully exempt from Maryland state income tax, so retirees living primarily on Social Security owe little or no state income tax on that income. This puts Maryland in line with most states. Note that Maryland still taxes most other retirement income, such as IRA and 401(k) withdrawals and most pensions.
How much is the Maryland pension exclusion in 2026?
The maximum Maryland pension exclusion for 2026 is $40,600 for residents who are 65 or older or totally disabled. It applies to qualifying pension and annuity income from an employee retirement system, such as a 401(k), 403(b), or defined benefit plan. Traditional and Roth IRAs do not qualify, and your Social Security income reduces the exclusion you can claim.
Is Maryland a good state to retire in for taxes?
Maryland is moderately tax-friendly for retirees, not a tax haven and not punishing. It fully exempts Social Security and offers a pension exclusion of up to $40,600 in 2026, but it taxes most other retirement income at rates up to 5.75% plus a county tax, and it has both an estate and an inheritance tax. Whether it works well for you depends heavily on your income sources and estate size.
What is the Harford County income tax rate for retirees?
Harford County, like every Maryland county, levies a local income tax that is added on top of the state income tax and applies to taxable retirement income such as IRA and pension withdrawals. Social Security remains exempt at both levels. Because county rates change and are set locally, retirees should confirm the current Harford County rate with the Maryland Comptroller when planning withdrawals.
Does Maryland have an estate tax?
Yes, Maryland has both an estate tax and an inheritance tax, making it one of the few states with both. The Maryland estate tax applies to estates above the state exemption of $5 million per person, which is well below the federal exemption. The inheritance tax applies to certain heirs based on their relationship to the deceased, with close family members generally exempt.
Planning a Maryland retirement that keeps more of your money
Retiring in Maryland works well when your plan takes advantage of what the state exempts and manages what it taxes, from coordinating withdrawals around the pension exclusion to addressing the estate and inheritance tax before it becomes your family's problem. The rules are specific, but they reward planning. Jeff Judge and the Chesapeake Financial Planners team serve retirees across Harford County and the Baltimore metro, and a conversation about your Maryland retirement plan costs you nothing. Schedule a free fit call at chesapeakefp.com.
Estate planning requires legal assistance. Neither LPL Financial nor its registered representatives offer legal advice.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


