

How Can You Build Predictable Retirement Income Without Risk?
Last reviewed: July 2026
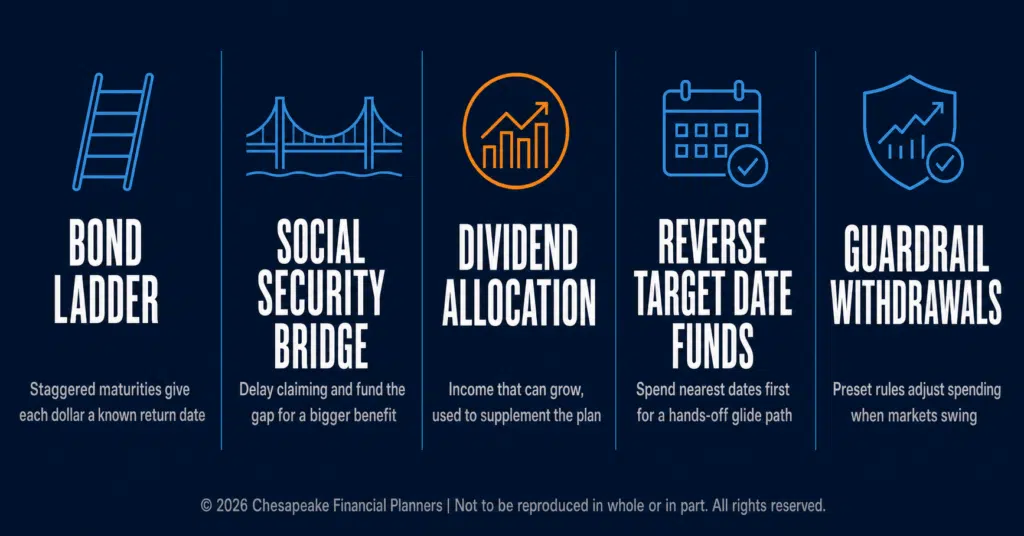
You build predictable retirement income by assembling several income sources that each behave differently, so no single market move can sink your paycheck. The five strategies that do this best are a bond ladder, a Social Security bridge, a dividend stock allocation, target date funds used in reverse, and a percentage withdrawal with guardrails. Each one turns a piece of your savings into cash flow you can count on, without locking everything into low rates or leaving everything exposed to a downturn.
The hard part of retirement is not the math. It is replacing a steady paycheck with money pulled from accounts that rise and fall. According to research from the Stanford Center on Longevity, retirees consistently prefer dependable income over a flexible lump sum, even when the lump sum is larger on paper. The strategies below give you that dependability while keeping enough growth to outrun a 30-year retirement.
Key Takeaways
- Predictable retirement income comes from layering five income sources, not from picking one safe product and hoping it lasts.
- Delaying Social Security past full retirement age raises your benefit by 8% each year, up to age 70.
- A bond ladder gives each dollar a known maturity date, so you know when principal returns rather than guessing at a fund's price.
- Maryland exempts Social Security and lets eligible retirees age 65 and older subtract up to $40,600 of other retirement income in 2026.
- Guardrail withdrawals set spending rules in advance, which removes emotion when markets swing.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate predictable retirement income since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched more retirees lose sleep over the shape of their income than over the size of their balance, and the fix is almost always adding a second or third source that does not move with the stock market.
On This Page
- How Does a Bond Ladder Create Predictable Income?
- Can a Social Security Bridge Buy You More Dependable Income?
- How Do Dividend Stocks Add Income and Growth Together?
- How Can Target Date Funds Be Used in Reverse for Income?
- What Is a Percentage Withdrawal With Guardrails?
- How Do You Combine These Into One Income Plan?
- Frequently Asked Questions
How Does a Bond Ladder Create Predictable Income?
A bond ladder creates predictable retirement income because every rung has a known maturity date, so you know exactly when principal is scheduled to come back. You buy individual bonds, Treasuries, high quality municipals, or investment grade corporates, with staggered maturities, then spend or reinvest each one as it comes due. A simple ladder might hold bonds maturing in 1, 3, 5, 7, and 10 years. When the first matures, you either use the cash for that year's spending or roll it into a new 10-year rung to keep the ladder going.
This is where individual bonds beat bond funds for income planning. A bond fund never matures, so when rates rise its share price can fall and stay down. According to Fidelity, a ladder of individual bonds is built to deliver scheduled cash flow over time, which is the whole point when you are funding a grocery bill rather than chasing a return. You hold each bond to maturity and collect the face value, barring a default, so the day-to-day price swings stop mattering.
The ladder also spreads interest rate risk across time instead of betting on one rate environment. If rates climb, your next maturing rung reinvests at the higher yield. If they fall, your longer rungs are already locked in.
What kind of bonds belong in a Maryland retiree's ladder?
For higher-bracket Maryland households, municipal bonds deserve a close look, because the interest is generally exempt from federal income tax and, when the bond is issued in your state, often exempt from Maryland income tax too. That double exemption can make a 4% muni beat a higher-yielding taxable bond after tax. The trade-off is that municipal bonds carry their own market and interest rate risk if sold before maturity, and some interest can fall under the alternative minimum tax. In Jeff's experience with retirees across Bel Air and Fallston, the ladder works best when it is sized to cover only the spending you can predict, with the rest of the portfolio doing the growing.
Can a Social Security Bridge Buy You More Dependable Income?
A Social Security bridge lets you delay claiming and capture a larger lifetime benefit by funding the gap years with safe, short-term money. Delaying past your full retirement age earns delayed retirement credits, and according to the Social Security Administration, those credits add 8% to your benefit for each year you wait, up to age 70. For someone with a full retirement age of 67, claiming at 70 instead produces a benefit 24% higher for life, and that larger number is inflation-adjusted every year afterward.
The practical obstacle is the income gap between the day you retire and the day you claim. A bridge fills it by setting aside several years of spending in low-risk instruments that mature in sequence: Treasury bills, CDs, or short-term bonds, each timed to a year you need it. Say you retire at 65 and plan to claim at 70. You estimate the annual income you need after any pension, then earmark five years of that gap in a dedicated account, with one tranche maturing each year.
This turns delaying into a conservative move rather than a gamble. You are not forced to sell stocks in a down market to cover living costs, and you are effectively converting portfolio dollars into more inflation-adjusted, government-backed income for the rest of your life. That is a trade most bonds cannot match.
Does the bridge strategy fit federal and military retirees near Aberdeen?
It fits especially well. Aberdeen Proving Ground anchors a large population of federal and military retirees across Harford County, and a FERS annuity or a military pension already provides dependable lifetime income alongside Social Security. For these households, the bridge often only needs to cover a smaller gap, because the pension and TSP are already doing heavy lifting. A federal retiree in Forest Hill might use a two or three year bridge from the TSP G Fund or short CDs, claim Social Security at 70, and lock in the larger benefit without ever touching equities at a bad time. See What Is the Best Social Security Claiming Age Strategy for Retirees? and What is the best strategy for withdrawing from my TSP when I retire? for the mechanics.
How Do Dividend Stocks Add Income and Growth Together?
A dividend stock allocation can supply an income stream that also has room to grow, which is what makes it different from a bond. The income comes from the dividends companies pay; the growth comes from the underlying shares appreciating over a long retirement. According to research from Hartford Funds, dividend growers and initiators have historically delivered greater total return with less volatility than companies that paid no dividend. That combination, income now plus appreciation later, is hard to get from a single instrument.
The practical build is a diversified slice of the portfolio in dividend-focused funds or a broad set of high quality companies with long, consistent dividend histories. You are not reaching for the highest yield on the screen; you are after durability of the payout. Two cautions matter and both come from real client experience. First, dividends can be cut, so diversification across many payers is essential rather than optional. Second, dividend income should supplement your other sources, never stand alone as the whole plan.
There is a tax angle that helps in retirement. If your dividends are qualified, they are taxed at the lower long-term capital gains rates rather than as ordinary income. The IRS applies long-term capital gains rates of 0%, 15%, or 20% depending on taxable income, and many retirees in the early, lower-income years land in the 0% band. REITs can add real estate income to the mix, though their distributions vary and are not guaranteed, so they belong inside a diversified sleeve rather than as a centerpiece.
Should dividend stocks replace bonds for income?
No, and treating them as interchangeable is a common mistake. A dividend stock can fall 30% in a bad year even while it keeps paying, so it does not deliver the principal certainty a maturing bond does. The right role is complementary: bonds and the bridge cover the income you must have, while dividend stocks cover income you would like to grow. Jeff often tells clients that the dividend sleeve is the part of the plan allowed to be patient, because you are not spending its principal next year. See How Do I Build a Dividend Income Portfolio for Retirement? for position sizing.
How Can Target Date Funds Be Used in Reverse for Income?
Target date funds can be used in reverse to build time-segmented spending buckets, turning a tool designed for savers into one that serves retirees. A target date fund automatically shifts from stocks toward bonds as its target year approaches. Instead of owning one fund pegged to a single year, you hold several with staggered target dates and spend them in order, nearest date first.
Here is the logic. A near-dated fund is already conservative, heavier in bonds and cash, so it can support the next few years of withdrawals with less volatility. A later-dated fund still holds more equities, so it keeps compounding while you leave it alone. A disciplined plan spends from the most conservative fund first and lets the longer-dated funds grow, creating a simple, rules-based glide path without you making constant rebalancing decisions. The fund's own design helps manage risk for you over time as the target year nears.
The trade-offs are real. You give up customization, since you accept the fund family's allocation choices, and you pay ongoing fund expenses. For a retiree who wants structure without a spreadsheet, that simplicity can be worth the cost. For one who wants precise control over every holding, a bond ladder or a managed allocation usually fits better.
Who is the reverse target date approach best for?
It suits a retiree who values simplicity and is comfortable delegating the allocation glide path to a fund. Someone managing their own accounts in retirement, without an advisor handling rebalancing, often gets more consistent behavior from staggered target date funds than from trying to time moves themselves. The structure removes the temptation to tinker during a scary market. It is less ideal for high-net-worth households where tax-lot control and municipal bonds change the after-tax math meaningfully.
What Is a Percentage Withdrawal With Guardrails?
A percentage withdrawal with guardrails is a spending rule that starts at a set withdrawal rate and then adjusts up or down only when your withdrawal rate crosses pre-set boundaries. It replaces a rigid fixed-dollar rule with one that responds to how the portfolio is actually doing, which both protects the portfolio in bad markets and lets you enjoy more in good ones.
The mechanics are straightforward. You set an upper and a lower guardrail around your starting withdrawal rate. If markets perform well and your withdrawal rate drifts below the lower guardrail, you give yourself a modest raise. If markets fall and your rate climbs above the upper guardrail, you trim spending temporarily until the rate comes back into range. Research on this approach, popularized by planner Jonathan Guyton, is summarized by Morningstar, which notes the Guyton-Klinger method "adjusts retirement portfolio withdrawals in line with portfolio performance" without forcing extreme swings in your cash flow. The discipline comes from deciding the rules before the emotion hits.
That last point is the entire value. When the rules are written down in advance, a 25% market drop becomes a pre-planned spending adjustment instead of a panic. You already know which discretionary line items, travel, gifts, a hobby, you will pause and for how long.
How do guardrails compare with the classic 4% rule?
The two answer different questions, so a table helps:
| Feature | Fixed 4% rule | Percentage withdrawal with guardrails |
|---|---|---|
| How spending is set | Fixed dollar amount, inflation-adjusted yearly | Percentage of current portfolio, adjusted at guardrails |
| Response to a downturn | None; spending continues regardless | Temporary cut when rate exceeds the upper guardrail |
| Response to strong markets | None; no raise beyond inflation | Modest raise when rate falls below the lower guardrail |
| Main weakness | Can overspend in bad markets, underspend in good ones | Requires the discipline to actually cut when triggered |
Guardrails are the more resilient framework for most retirees because they react to reality. The 4% rule is simpler to explain but ignores what the market is doing. Jeff has seen the guardrail conversation defuse a client's fear faster than any chart, because it answers the real worry, what will I actually do if this keeps dropping, with a concrete, pre-agreed plan. See What Is the 4% Rule and Does It Still Work in Retirement? for the underlying research.
How Do You Combine These Into One Income Plan?
You combine these five strategies by assigning each one a job, so that essential spending rests on the most dependable sources and growth assets stay free to grow. Social Security, claimed at the right time and bridged if needed, forms the inflation-adjusted base. A bond ladder covers scheduled, predictable cash needs. Dividend stocks and reverse target date funds supply income with growth potential for the long haul. A guardrail withdrawal rule governs how much you actually pull each year. Cash reserves buffer the near term so you never sell into a crash.
This is also where a defined process keeps the moving parts aligned. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. Applied to income, it means we map your sources, stress-test the plan against a bad market and the Maryland tax rules, then revisit it as rates, tax law, and your spending change. If you prefer the framing of time-based layers rather than income sources, our companion guide on How Do You Structure Retirement Income in Maryland? walks through the bucket approach in detail.
Maryland's tax treatment shapes how these sources fit together. The state does not tax Social Security at all, and eligible retirees age 65 and older can subtract up to $40,600 of other qualifying retirement income for the 2026 tax year, per the Maryland Comptroller, with that exclusion phasing down as Social Security rises. Because required minimum distributions begin at age 73 under SECURE 2.0, the years before 73 are often the best window to draw from tax-deferred accounts or convert to Roth at a low bracket. See When does a Roth conversion make financial sense and how do you execute it? and What are the rules and strategies for required minimum distributions? for the sequencing, and How do I choose a fee-based fiduciary financial advisor in Harford County? for help assembling the whole plan. Jeff Judge notes: "Maryland's full retirement income exclusion and the zero tax on Social Security make the years between retirement and age 73 a narrow but genuinely valuable window to draw down tax-deferred accounts or convert to Roth before RMDs stack on top and compress your bracket room."
How often should this income plan be reviewed?
Review the income plan once a year and after any major change, a market move of roughly 20%, a health event, a death in the family, or a tax law shift. The annual review confirms the guardrails are still set correctly, checks whether a Roth conversion makes sense that year, and re-times the next bond ladder rung. Jeff has watched a written, reviewed income plan let a surviving spouse keep the household running without a single missed payment, and that durability is the real product.
Frequently Asked Questions
What is the safest way to create predictable retirement income?
The safest approach is to combine several income sources that behave differently rather than relying on one. Pair Social Security, a bond ladder for scheduled cash, and a guardrail withdrawal rule, then keep a cash reserve so you never sell stocks in a downturn. Diversifying the sources, not just the investments, is what protects your paycheck.
How much of my retirement income should be guaranteed?
Most retirees aim to cover their essential, non-negotiable expenses, housing, food, healthcare, insurance, and utilities, with dependable lifetime income such as Social Security and any pension. Discretionary spending like travel and gifts can lean on growth assets and dividends. The exact split depends on your spending, your other income, and your comfort with market swings, so it is worth modeling before you commit.
Is a bond ladder better than a bond fund for retirement income?
For predictable income, a bond ladder usually has an edge because each individual bond has a maturity date, so you know when principal returns. A bond fund never matures, and its price can fall when interest rates rise and stay down. A ladder lets you hold each bond to maturity and collect face value, barring default, which makes scheduled spending easier to fund.
Should I delay Social Security to get more income?
Delaying often produces the largest dependable raise available in retirement. Each year you wait past full retirement age adds 8% to your benefit through age 70, and the higher amount is inflation-adjusted for life. Delaying makes the most sense when you have other assets or a Social Security bridge to fund the gap and when longevity is likely, especially for the higher earner in a married couple.
How does Maryland tax retirement income?
Maryland does not tax Social Security benefits, and it lets eligible taxpayers age 65 and older subtract up to $40,600 of qualifying retirement income for the 2026 tax year through the pension exclusion. The exclusion shrinks as Social Security income rises. Withdrawals from IRAs and 401(k)s are generally taxable at Maryland rates, so the source and timing of each withdrawal affects your state tax bill.
Can dividend stocks provide reliable retirement income?
Dividend stocks can provide a useful income stream that also grows, but they are not a substitute for bonds or Social Security. Dividends can be reduced, and the share price can drop sharply in a bad year, so diversification across many payers is essential. Use a dividend allocation to supplement dependable income, not to carry the entire plan on its own.
What is a guardrail withdrawal strategy?
A guardrail withdrawal strategy starts with a set withdrawal rate and adjusts spending only when the rate crosses pre-set upper or lower limits. If markets fall and your withdrawal rate climbs too high, you trim spending temporarily; if markets do well and the rate drops low, you give yourself a modest raise. Setting these rules in advance removes emotion when markets swing.
Ready to put a real structure around your predictable retirement income? Jeff Judge and the Chesapeake Financial Planners team serve families, federal retirees, and business owners across Forest Hill, Bel Air, and the wider Harford County and Baltimore metro area. Schedule a free fit call and we will map your income sources, your Social Security timing, and your Maryland tax picture together.
A version of this article originally appeared in Kiplinger.
Want to go deeper? Our Retirement Income Blueprint Workbook walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Growth investments may be more volatile than other investments because they are more sensitive to investor perceptions of the issuing company's growth of earnings potential.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


