

What Should You Tell Family After Winning the Lottery?
Last reviewed: July 2026
After winning the lottery, tell your spouse first, tell no one else until you have hired an advisory team, and never name the exact dollar amount to anyone. Effective lottery winner family communication means leading with your values and timeline, not a number. The first 72 hours set the tone for every relationship you have, so a quiet, deliberate approach protects both your money and the people you love.
Key Takeaways
- Tell your spouse or partner first and privately; everyone else waits until your advisory team is in place.
- Never disclose the exact amount won; vague generosity invites pressure and resentment.
- Roughly 70% of lottery winners and others who receive a windfall lose it within a few years according to financial literacy research.
- Federal tax withholding on lottery winnings starts at 24%, and your actual rate can reach the top bracket of 37%.
- Only a handful of states let you claim a major prize anonymously, so plan as if your name will become public.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate sudden wealth events since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched a single careless phone call to a relative turn a private windfall into a public spectacle within 48 hours, and he tells clients the quiet plan almost always beats the fast one.
A sudden windfall does not just change your bank balance. It changes how every person around you sees you, sometimes overnight. The good news is that sudden wealth communication is a skill you can plan for. Below are the questions winners ask most, answered directly.
Who Should You Tell First After Winning the Lottery?
Tell your spouse or partner first, and tell them privately. If you share finances and a life with someone, they need to know before anyone else, but even this conversation should be calm and forward-looking rather than celebratory chaos. Agree together on two things immediately: keep the news confidential until you meet with advisors, and make no financial promises to anyone.
Beyond your spouse, the honest answer is that no one else needs to know yet. Adult children, parents, and close friends can wait until you have a plan. The more people who know early, the harder lottery winner privacy becomes to maintain, and the faster expectations harden into demands.
Jeff Judge often tells clients that the instinct to share good news immediately is exactly the instinct that gets winners into trouble. The money is not going anywhere in the next two weeks. Your relationships, on the other hand, can shift permanently in a single afternoon.
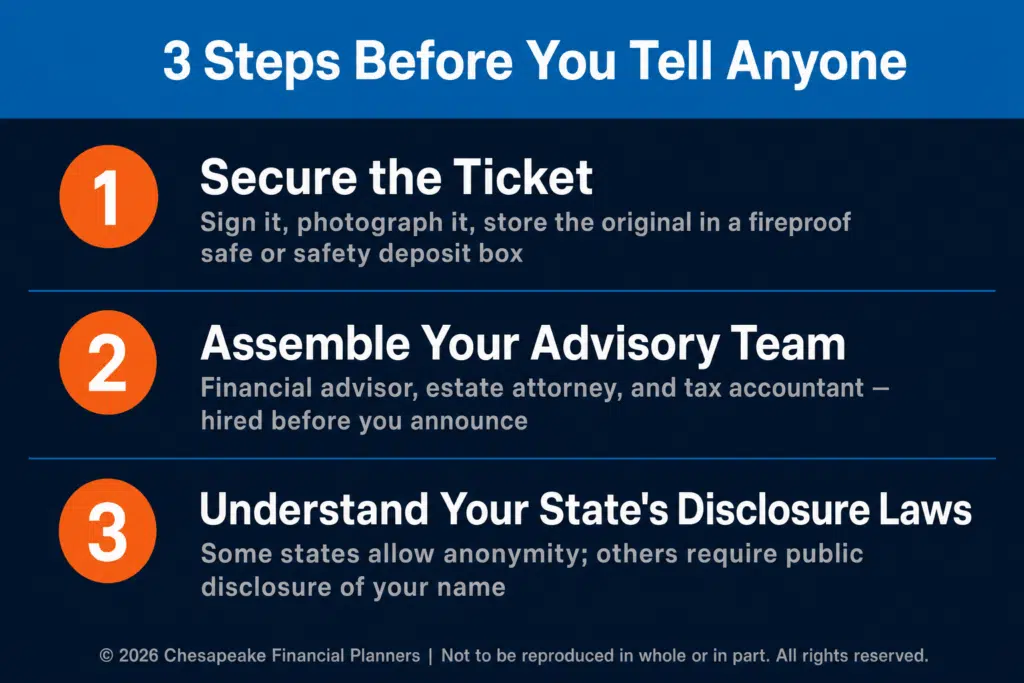
What Should You Do Before Telling Family About Money?
Before you tell family about money, secure the ticket, assemble an advisory team, and confirm your state's disclosure rules. These three steps create a structure that protects you when the questions start coming. Sign the back of the winning ticket, photograph it, and store the original somewhere fireproof and secure. That ticket is your only proof of ownership.
Next, hire professionals before family expectations solidify. Most winners need at least three: a financial advisor experienced with sudden wealth, an estate planning attorney, and a tax accountant who understands windfall events. The R.U.D.D.E.R. Method™ is Chesapeake Financial Planners' six-step planning process: Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine. A windfall sits squarely in the first two steps before any money moves.
Finally, understand your state's rules. Only a small number of states allow major lottery winners to stay fully anonymous, and the FTC regularly warns that publicly named winners become immediate targets for scams and solicitations. If your name will be published, your family communication plan matters even more, because the news will reach people before you can.
How Do You Set Boundaries Without Damaging Relationships?
Set boundaries by leading with your values and your timeline rather than a dollar figure. The goal is to be clear and warm at the same time. When you finally tell close family, schedule individual conversations instead of announcing at a gathering, and frame the news around how you intend to make decisions, not what you plan to give.
A simple script works better than a long explanation. Try: "I've had a significant windfall, and I'm working with advisors before making any commitments. I want to be generous in a thoughtful, sustainable way, and I'll share more once I have a clear plan." That sentence handles windfall family pressure without making a promise you may regret. Jeff Judge notes: "Telling family you're working with advisors before making commitments isn't a brush-off — it's the only script that keeps you from being held to a number you said in an emotional moment."
What you avoid matters as much as what you say. Never mention the exact amount, never say "I'll take care of everyone," and never describe specific purchases or gifts before your plan is finalized. Vague promises are the most expensive words a winner can speak, because relatives remember them precisely even when you meant them loosely.
In Jeff's experience working with clients through liquidity events, the winners who keep their relationships intact are the ones who treat generosity as a decision to plan, not a reflex to perform. Saying less early gives you room to be genuinely generous later, on your terms.
How Do You Manage Family Expectations Over Time?
Manage expectations by deciding your giving framework before you respond to any individual request. Ongoing pressure is normal after a windfall, and the families who handle it best have a process rather than a case-by-case emotional negotiation. Decide in advance how you will say yes, how you will say no, and who helps you screen requests.
Putting your advisor between you and the requests protects both your finances and your relationships. "Let me run that by my financial team" is a complete answer, and it removes you from being the personal gatekeeper of every conversation. The CFPB notes that sudden wealth recipients are frequent targets for predatory financial schemes, which is one more reason to route requests through professionals.
Structured giving also gives the money a job. Donor-advised funds, formal gifting plans, and education trusts let you be generous in a way that lasts. Telling family about money becomes much easier when "yes" has a structure behind it instead of resting entirely on your goodwill in the moment.
Frequently Asked Questions
Should I tell my whole family right away after winning the lottery?
No. Tell your spouse or partner first and privately, then wait until your advisory team is assembled before telling anyone else. The more people who know early, the harder it becomes to protect your privacy and manage expectations. A short delay of a few weeks costs you nothing and gives you a plan before the requests start.
Should I tell people the exact amount I won?
No, never disclose the exact amount to family or friends. Specific numbers create specific expectations and invite pressure you cannot easily undo. Instead, describe the win generally as "a significant windfall" and explain that you are working with advisors. Vague generosity gives you flexibility, while a precise figure becomes a benchmark everyone measures their requests against permanently.
Can I stay anonymous as a lottery winner?
It depends on your state. Only a limited number of states allow major lottery winners to claim a prize anonymously or through a trust or LLC, while many require public disclosure of your name and city. Confirm your state's rules with an attorney before claiming. If disclosure is mandatory, build your family communication plan assuming the news will spread.
How much tax will I owe on lottery winnings?
Lottery winnings are taxed as ordinary income. The IRS requires 24% federal withholding upfront, but your actual federal rate can reach the top bracket of 37% for large prizes, plus any applicable state tax. This is why hiring a tax professional before you spend or gift anything is essential to avoid a painful surprise at filing time.
What should I say when family members ask for money?
Lead with your timeline, not a yes or no. A reliable response is: "I'm still working with my financial team on a plan, and I'm not making any commitments yet." Routing requests through your advisor protects both your finances and the relationship, because it removes you from being the personal gatekeeper for every individual conversation.
Why do so many lottery winners lose their money?
Many winners lose their money because they make large, fast, emotional decisions before building any plan or structure. Research on financial literacy has long highlighted how quickly sudden wealth can disappear without professional guidance. Combining unmanaged family pressure, generous but unstructured gifting, and a lack of tax planning is the most common path from windfall to financial trouble.
A Quiet Plan Beats a Fast One
The single most valuable thing you can give yourself after winning the lottery is time. Tell your spouse, hire your team, and say very little to everyone else until you know what you are doing. If you want a deeper guide to handling a major windfall the right way, our What should you do when you suddenly receive a large sum of money? resource walks through the full process step by step. For more on the professionals you will need, see What professionals does a lottery winner need to hire first?, and to understand the broader financial picture, read What happens to my finances after a liquidity event?. Download our windfall planning guide at chesapeakefp.com to start with a clear, calm framework.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


