

What Should I Do First After Inheriting Money or Property?
Last reviewed: July 2026
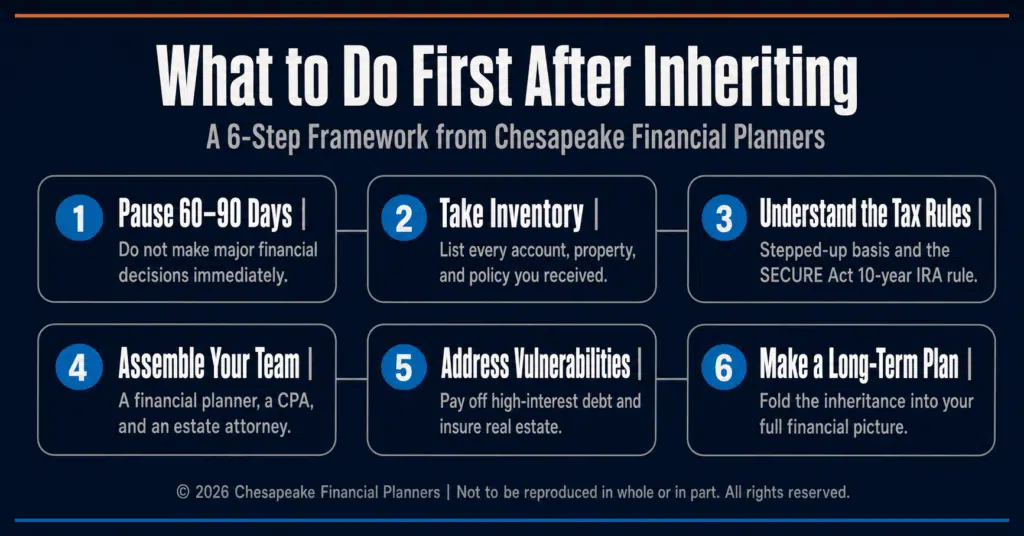
The first thing to do after inheriting money is nothing. Park the funds somewhere safe, leave them alone for 60 to 90 days, and resist every urge to invest, spend, or give it away. That pause protects you from the most expensive mistakes people make with inheriting money, because the worst decisions almost always happen in the first three months while grief and pressure are running the show.
Key Takeaways
- Do not make major financial moves for 60 to 90 days; park liquid funds in a high-yield savings or money market account.
- Most non-spouse heirs must empty an inherited IRA within 10 years under SECURE Act rules.
- The 2026 federal estate tax exemption is $15 million per person, so estate tax affects very few families.
- Inherited investments and property usually receive a stepped-up cost basis, which can erase decades of capital gains.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate inheritances and wealth transitions since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff has watched heirs lose more money to rushed decisions in the first 90 days than to bad markets over the following decade.
Why Should You Pause Before Doing Anything?
The 60 to 90 days after an inheritance arrives are the most dangerous window for your money. You're grieving. You may be holding more cash than you've ever managed. And suddenly everyone has an opinion about what you should do with it.
Resist all of it. Unless you're facing a genuine emergency or a hard tax deadline, you have time. Park liquid funds in a high-yield savings account or money market fund where they stay safe and accessible. As of 2026, many such accounts pay meaningfully more than a standard checking account, so the money keeps working while you think.
Jeff Judge tells clients the same thing every time: "The inheritance isn't going anywhere. The bad decisions are the ones that move fast." This pause isn't procrastination. It's the single most valuable financial move you'll make, because it buys you the time to plan instead of react. At Chesapeake Financial Planners, this is where the R.U.D.D.E.R. Method™ begins: the firm's six-step planning process of Review and Recognize, Uncover and Understand, Design and Develop, Discuss and Decide, Execute and Empower, and Reassess and Refine.
How Do You Take Inventory of What You Inherited?
Before you plan anything, you need a complete picture of what you actually received. Inheritances rarely arrive as a single tidy check. They show up as a mix of asset types, each with its own tax treatment and rules.
Build a written inventory. Document every inherited asset: bank accounts, taxable investment accounts, retirement accounts, real estate, vehicles, business interests, life insurance proceeds, and personal property of real value. Note the institution, account number, approximate value, and the names on each title.
Pay close attention to inherited retirement accounts. These carry the most complex rules and the steepest penalties for getting them wrong. If you inherited real estate, a business, or valuable collectibles, you'll likely need a professional appraisal to establish fair market value as of the date of death. That valuation sets your cost basis, and it matters enormously when you eventually sell.
What Are the Tax Rules on Inherited Retirement Accounts?
Inherited retirement accounts are where most heirs get burned. Under the SECURE Act, most non-spouse beneficiaries must empty an inherited IRA or 401(k) within 10 years of the original owner's death. The old "stretch IRA" that let heirs spread distributions across a lifetime is gone for most people.
The IRS treats these accounts differently based on your relationship to the deceased, their age at death, and whether they had already begun required minimum distributions. Spouses get more flexible options, including rolling the account into their own IRA. Some heirs must take annual distributions during the 10-year window; others can wait. Guessing wrong triggers penalties.
Here's the planning angle most people miss: emptying a large inherited traditional IRA can push you into a higher tax bracket if you cram the withdrawals into a few years. Spreading them deliberately across the full 10 years often saves real money. This is exactly the kind of inherited retirement accounts decision worth modeling before you touch the account.
What Happens to the Tax Basis on Inherited Property and Investments?
Most inherited taxable assets receive a "stepped-up" cost basis equal to their fair market value on the date of death. This is one of the most valuable features in the tax code for heirs.
Say a parent bought stock for $10,000 decades ago and it's worth $100,000 when you inherit it. Your basis steps up to $100,000, which wipes out $90,000 of unrealized capital gains. If you sell shortly after inheriting, you may owe little or no capital gains tax. That's why understanding basis before you sell anything is critical.
The same step-up applies to inherited property. Inherited real estate generally gets a basis equal to its appraised value at death, which is why that appraisal matters. Be aware that inherited property can trigger property tax reassessment in some states, and the inheritance tax implications vary widely by state. As of 2026, the federal estate tax exemption sits at $15 million per person under the One Big Beautiful Bill Act, so federal estate tax touches very few families. But a handful of states impose their own inheritance or estate taxes at much lower thresholds, so estate planning after inheritance should always include a check on your specific state's rules.
Who Should Be on Your Advisory Team?
Complex inheritances call for coordinated professional guidance. Trying to manage a mix of accounts, property, and tax deadlines alone usually leads to expensive gaps. According to FINRA, working with credentialed, vetted professionals is one of the strongest defenses against costly errors and scams during a wealth transition.
Depending on what you inherited, your team may include an estate attorney for title transfers or a still-settling estate, a CPA to handle the inheritance tax implications and plan retirement account distributions, and a financial advisor to invest liquid assets and keep everyone coordinated. Managing inherited wealth well is largely a coordination problem. Uncoordinated advice from three professionals who never talk to each other creates conflicts and contradictions.
Jeff Judge often sees heirs hire good individual advisors who give good individual advice that collectively makes no sense. The fix is one quarterback who keeps the plan whole.
Frequently Asked Questions
What should I do first after inheriting money?
Do nothing major for 60 to 90 days. Move liquid funds into a high-yield savings or money market account, then build a written inventory of everything you inherited. This pause prevents the rushed, emotional decisions that cause most inheritance regret, and it gives you time to assemble advisors before committing to anything permanent.
How long do I have to empty an inherited IRA?
Most non-spouse beneficiaries must empty an inherited IRA within 10 years of the original owner's death under SECURE Act rules. Spouses have more flexible options, including rolling the account into their own IRA. Some heirs must also take annual distributions during the 10-year window, so confirm your specific requirement with a tax advisor before withdrawing.
Do I have to pay taxes on inherited property?
You typically owe no income tax simply for receiving inherited property, and most assets get a stepped-up cost basis to their value at the date of death. That step-up can eliminate decades of capital gains if you sell soon after inheriting. Some states impose separate inheritance or estate taxes, so check your state's rules.
Will I owe federal estate tax on my inheritance?
Almost certainly not. The 2026 federal estate tax exemption is $15 million per person, so federal estate tax applies only to very large estates, and the tax is paid by the estate, not the heir. A small number of states levy their own inheritance or estate taxes at lower thresholds, so confirm your state's specific rules with a CPA.
Should I pay off debt with my inheritance?
Paying off high-interest debt is often one of the smartest early moves. Eliminating a credit card balance charging 20% or more delivers a guaranteed return that investment markets rarely match. After you've parked the funds and built your inventory, retiring high-rate debt and shoring up your emergency fund are reasonable steps to take before larger investment decisions.
How do I protect inherited money from scams and pressure?
Tell as few people as possible, work only with credentialed and vetted professionals, and refuse to make fast decisions. A simple line like "I'm working with my advisors" ends most uncomfortable conversations. You are not obligated to share your inheritance or explain your plans to anyone, and slowing down is your strongest defense against both manipulation and fraud.
If you're sitting on a recent inheritance and feel the pressure to act, you don't have to figure it out alone. At Chesapeake Financial Planners, we walk clients through inheriting money decisions every week, coordinating with their attorney and CPA so the plan actually holds together. A second opinion costs you nothing. Visit chesapeakefp.com to learn more.
What should I do with money I inherited from a relative?
How Can I Protect Inherited Money from Scams and Bad Decisions?
What should you do when you suddenly receive a large sum of money?
Want to go deeper? Our What to Do After You Inherit Money or Property walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
Contributions to a traditional IRA may be tax deductible in the contribution year, with current income tax due at withdrawal. Withdrawals prior to age 59 ½ may result in a 10% IRS penalty tax in addition to current income tax.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


