

What Types of Trusts Should High Net Worth Families Consider?
Last reviewed: July 2026
High net worth families should consider revocable living trusts as the foundation, then layer in irrevocable trusts such as ILITs, GRATs, QPRTs, and generation-skipping trusts to reduce estate tax, protect assets from creditors, and control how wealth passes to the next generation. The right mix depends on your estate size relative to the federal exemption, your asset types, and your family goals. No single trust does everything, which is why most wealthy families use two or three working together.
Key Takeaways
- A revocable living trust avoids probate and plans for incapacity but provides no asset protection or estate tax savings.
- The 2026 federal estate and gift tax exemption is $15 million per individual, so irrevocable strategies matter above that line.
- Irrevocable trusts trade control for protection: once funded, assets leave your taxable estate and your creditors' reach.
- GRATs, QPRTs, and ILITs move appreciating assets, homes, and life insurance out of your estate at discounted gift values.
- The federal estate tax rate tops out at 40%, making proactive trust planning worth hundreds of thousands of dollars.
About the Author: Jeff Judge, CFP®, AEP®, ChFC®, CLU® is Managing Partner of Chesapeake Financial Planners in Forest Hill, Maryland. He has been helping families and business owners in Harford County and the Baltimore metro area navigate trust and estate planning since earning his CFP® certification in 2013, by using Chesapeake Financial Planners’ signature process, the R.U.D.D.E.R. method™. Jeff often reminds clients that a trust document is only as good as the assets actually titled into it, and that the most common estate planning failure he sees is a perfectly drafted trust left unfunded.
Why Trusts Matter for High Net Worth Families
Trusts solve three problems at once for wealthy families: asset protection, estate tax reduction, and control over how and when heirs receive money. A revocable trust handles probate and incapacity. Irrevocable trusts shield assets from lawsuits and creditors. The most aggressive structures remove future appreciation from your taxable estate before it ever happens.
The math is what drives the urgency. The IRS sets the 2026 federal estate and gift tax exemption at $15 million per individual, or $30 million for a married couple using portability. Estates above that face a top federal rate of 40%. For a family with $25 million in assets, that exposure can run into the millions, and most of it is avoidable with planning done years ahead.
Trusts for high net worth families are not a one-time purchase. They are a layered system. Jeff has watched clients assume a single revocable trust covers everything, only to discover at the worst possible moment that it offered zero protection from a creditor judgment.
How can I potentially optimize my taxes as my income grows?
What Does a Revocable Living Trust Do?
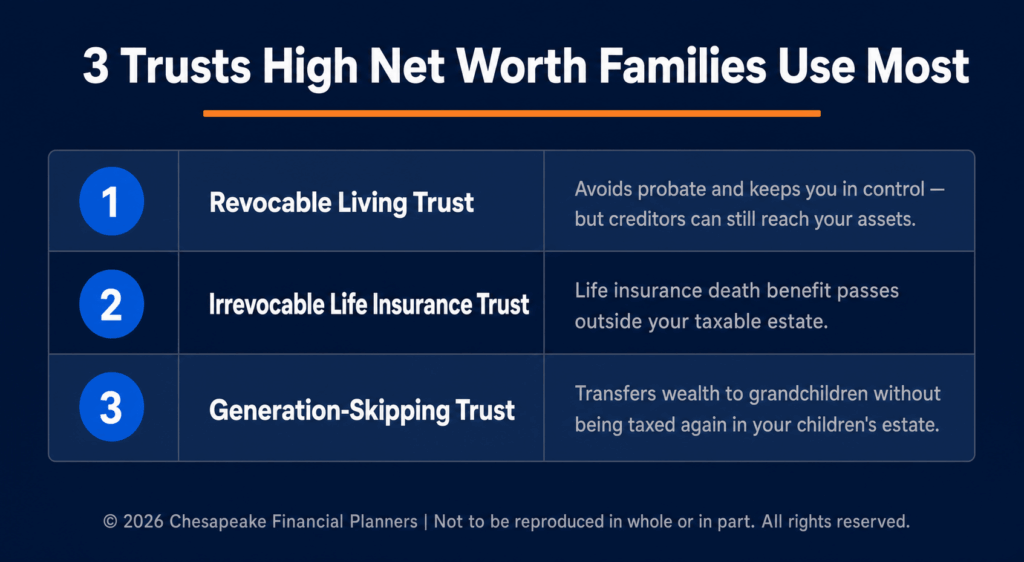
A revocable living trust is the baseline. You create it, move assets in, and serve as your own trustee while you are alive and well. You keep complete control: change beneficiaries, add or remove assets, or dissolve it entirely whenever you like.
Its real value is avoiding probate, the public and often slow court process that settles an estate. It also plans for incapacity, because your named successor trustee can step in and manage everything without a court appointing a guardian.
What it does not do matters just as much. A revocable trust gives you no asset protection, because you control the assets, so creditors can still reach them. It also provides no estate tax savings, since the assets remain part of your taxable estate. It is the foundation, not the finished structure.
How Do Irrevocable Trusts Protect Assets and Cut Estate Taxes?
Irrevocable trusts work precisely because you give up control. Once you transfer assets into one, they legally stop being yours. That single feature is what removes them from your taxable estate and puts them beyond the reach of most creditors and lawsuits.
The trade-off is real. You generally cannot undo the transfer or freely change terms. For high-risk professionals such as physicians, real estate developers, and business owners, that loss of flexibility buys meaningful protection. Domestic asset protection trusts in certain states even let you remain a discretionary beneficiary while keeping creditor protection.
Which irrevocable trusts move the most value?
Several irrevocable structures specialize in shifting specific assets out of your estate:
| Trust Type | Best For | Primary Benefit |
|---|---|---|
| ILIT | Families with large life insurance policies | Keeps death benefit out of taxable estate |
| GRAT | Owners of appreciating assets or business interests | Passes future growth gift-tax-free |
| QPRT | Owners of valuable primary or vacation homes | Transfers home at a discounted gift value |
| GST Trust | Multi-generational wealth above the exemption | Skips a layer of estate tax |
How do you create a family wealth governance structure for long-term success?
How Do ILITs, GRATs, and QPRTs Actually Work?
An Irrevocable Life Insurance Trust (ILIT) owns your life insurance policy so the death benefit pays out free of estate tax. Life insurance proceeds are income-tax-free but normally counted in your taxable estate. A $5 million policy you own personally could add up to $2 million in federal estate tax at the 40% rate. The same policy inside an ILIT is excluded. Beneficiaries must receive annual Crummey notices, and if you transfer an existing policy and die within three years, it gets pulled back into your estate.
A Grantor Retained Annuity Trust (GRAT) moves appreciating assets to heirs with minimal gift tax. You fund the GRAT, take fixed annuity payments for a set term, and any growth above the IRS-assumed rate passes to beneficiaries gift-tax-free. Business owners expecting a sale and investors with concentrated stock positions use these heavily.
A Qualified Personal Residence Trust (QPRT) transfers your home at a reduced gift value. You keep living there rent-free for a set term, often 10 to 15 years, after which the home passes to your heirs. The gift value is discounted because beneficiaries must wait. The risk is the same as a GRAT: die before the term ends and the asset returns to your estate.
According to the American Bar Association, irrevocable trusts remain among the most reliable tools for removing appreciating assets from a taxable estate when funded correctly and well in advance.
How Do I Leave Money to a Disabled Child Without Losing Benefits?
When Should You Use a Generation-Skipping Trust?
A generation-skipping transfer (GST) trust passes wealth to grandchildren while skipping the estate tax that would otherwise hit at your children's generation. Your children can receive income during their lifetimes; the principal then flows to grandchildren without being taxed again in your children's estates.
The 2026 GST exemption matches the estate exemption at $15 million per individual, so families with estates well above that line benefit most. Without a GST trust, the same dollars can be taxed twice as they move down two generations. With one, they are taxed once and then pass cleanly.
This is the structure for families thinking in 50-year horizons rather than one inheritance. It pairs naturally with broader family wealth governance and is rarely a do-it-yourself project.
Who owes Maryland's 10% inheritance tax and what planning options protect non-lineal heirs?
Frequently Asked Questions
What is the difference between a revocable and an irrevocable trust?
A revocable trust lets you keep full control, change terms, and dissolve it anytime, but offers no asset protection or estate tax savings. An irrevocable trust requires you to give up control permanently, which is exactly what removes the assets from your taxable estate and shields them from most creditors and lawsuits.
How much money do you need to justify a trust?
Most families with assets above $500,000 benefit from a revocable living trust for probate avoidance and incapacity planning. Irrevocable estate tax strategies become relevant as you approach the 2026 federal exemption of $15 million per individual. Asset protection trusts make sense earlier for high-risk professionals regardless of net worth.
Do trusts avoid estate taxes for high net worth families?
Revocable trusts do not avoid estate taxes because you retain control of the assets. Irrevocable trusts can, since transferring assets out of your name removes them from your taxable estate. Strategies like ILITs, GRATs, QPRTs, and GST trusts each target different assets and can collectively shield millions from the 40% federal estate tax.
What is an ILIT and who needs one?
An Irrevocable Life Insurance Trust owns your life insurance so the death benefit stays out of your taxable estate. Families with large policies and estates near or above the federal exemption need one most. Without it, a multi-million-dollar policy can add hundreds of thousands in unnecessary estate tax at the 40% federal rate.
Can I change an irrevocable trust after creating it?
Generally no, which is the point: giving up control is what delivers the tax and asset protection benefits. Some flexibility exists through trust protectors, decanting in certain states, or specific drafting provisions. Anyone considering an irrevocable trust should work with an estate attorney and advisor to build in appropriate flexibility before funding it.
What happens if I die during a GRAT or QPRT term?
If you die before a GRAT or QPRT term ends, the assets are pulled back into your taxable estate, undoing the planned tax benefit. This term risk is why these trusts work best when you are reasonably confident of outliving the term. Many families use shorter or rolling GRAT terms to manage this exposure.
Where to Go From Here
The right trust structure depends on the size and makeup of your estate, your tolerance for giving up control, and how many generations you want your wealth to reach. Trusts for high net worth families work best when planned years ahead, not assembled in a crisis. If you want a clear picture of which structures fit your situation, our estate planning guide walks through the decisions step by step. Download it at chesapeakefp.com.
Want to go deeper? Our Estate Document Locator walks through this step by step.
Disclosures
The information provided is for educational purposes only and should not be construed as investment advice. Investment strategies should be tailored to individual circumstances, risk tolerance, and goals. Past performance doesn't guarantee future results. Consult with qualified financial professionals regarding your specific situation.
This information is not intended to be a substitute for specific individualized tax, investment or legal advice. We suggest that you discuss your specific situation with a qualified tax, legal or financial advisor.
Advisors associated with Chesapeake Financial Planners may be either (1) LPL Financial Registered Representatives offering securities through LPL Financial, Member FINRA and SIPC, and investment advisor representatives offering investment advice through Great Valley Advisor Group; or (2) solely investment advisor representatives offering investment advice through Great Valley Advisor Group and not affiliated with LPL Financial. Great Valley Advisor Group, and Chesapeake Financial Planners are separate entities from LPL Financial.


